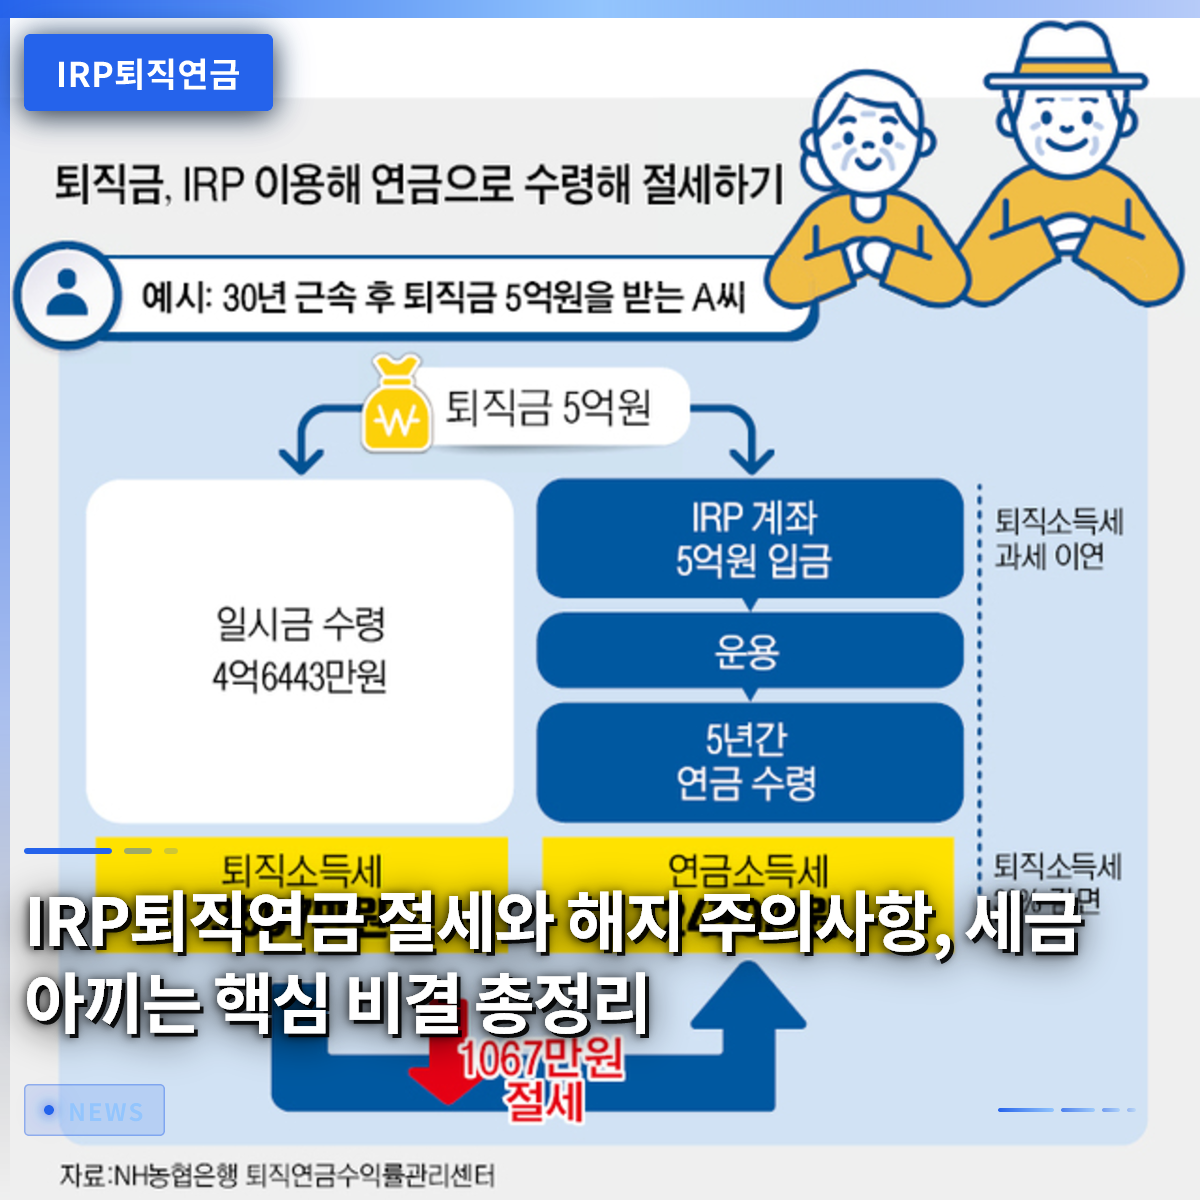
If you want to save on taxes when receiving your severance pay, the wise choice is to always receive it into an Individual Retirement Pension (IRP) account. Recently, many employees, upon changing jobs or retiring, immediately transfer their lump sum to a regular savings account or spend it right away. However, statistics show that a significant portion of the amounts transferred to IRP accounts over the past several years has been withdrawn early, causing people to miss out on valuable tax benefits and savings. In this article, we will thoroughly examine how to safely protect and grow your severance pay, as well as practical tips for reducing your tax burden. If you are looking for your first job or planning a career change, this content is essential. If you want to build a solid financial foundation for your retirement, please pay close attention to the information provided below.
=
IRP Retirement Pension: Tax Savings, Cancellation Precautions, and Key Strategies to Save on Taxes
1. Why You Must Receive Your Severance Pay in an IRP Account

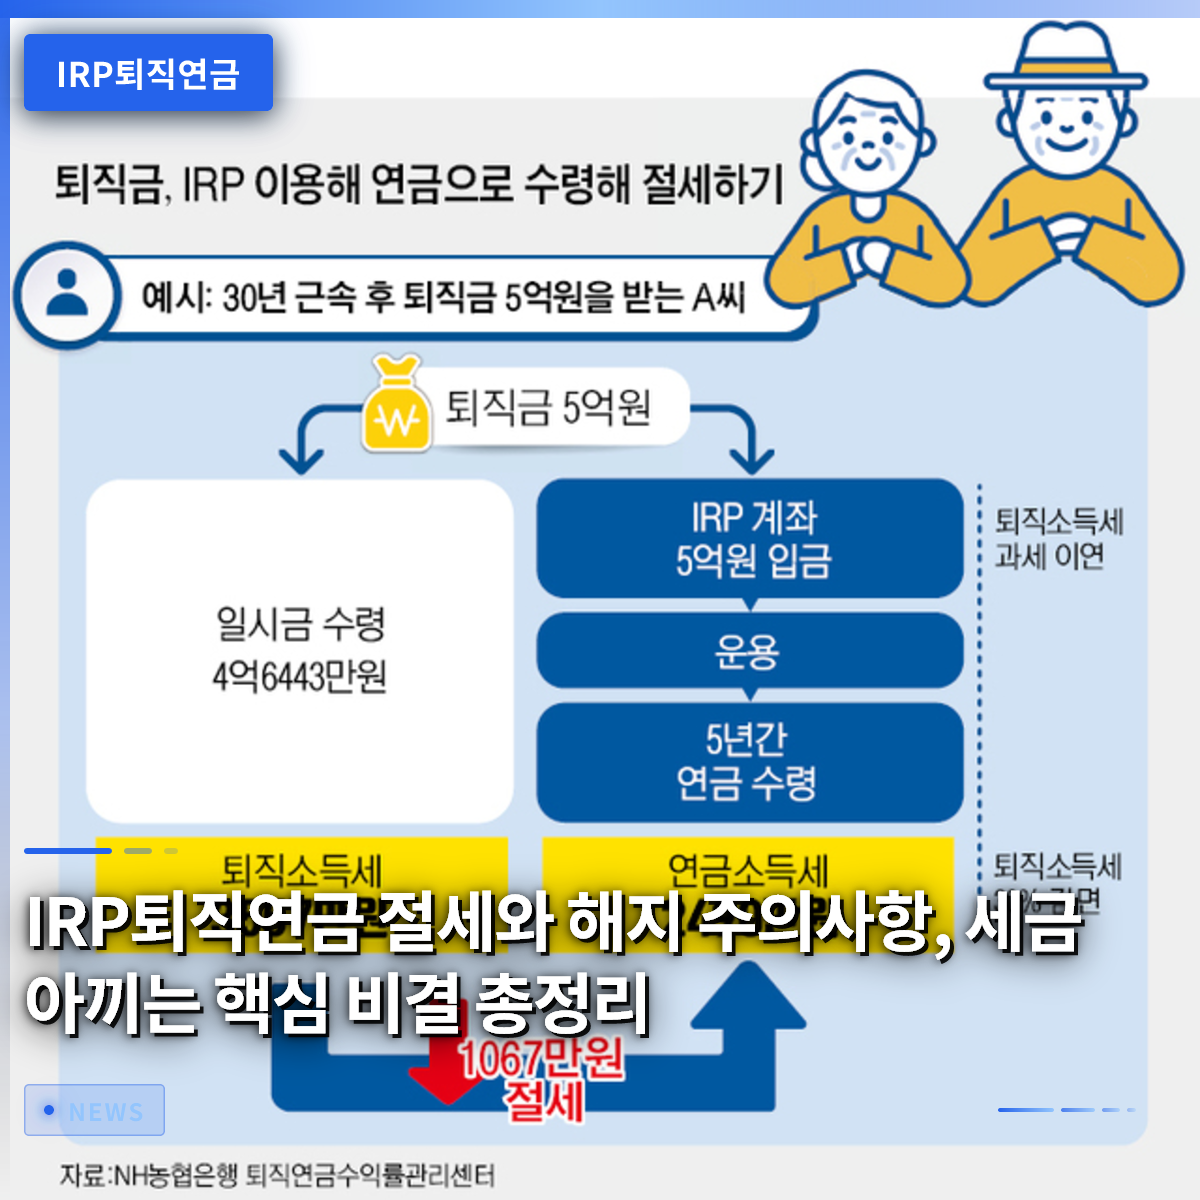
When you leave or change jobs, it is advantageous to transfer your severance pay to an Individual Retirement Pension (IRP) account rather than a regular bank account. If you receive your severance pay in a regular account simply because you need immediate cash, you will be subject to withholding tax on retirement income, inevitably resulting in a loss. On the other hand, if you transfer your severance pay directly to an IRP account, you can benefit from tax deferral, meaning taxes are not deducted immediately. The deferred taxes are paid later as pension income tax when you receive the funds as a pension after the age of 55, which is significantly lower than the tax you would have paid originally. A common trait among employees who save more than 100,000 won in taxes is their active utilization of this system. The most certain first step to turning taxes into profit is receiving your severance pay via account transfer to an IRP.
If you make additional contributions while maintaining the account, you can also enjoy tax deduction benefits during your year-end tax settlement. Since taxes are refunded at a certain rate based on the amount contributed each year, it is considered an essential wealth management tool for employees. Instead of just envying colleagues who receive large refunds during their year-end tax settlement, you should check your own account contributions. It is rare to find a structure that allows you to secure tax benefits while simultaneously growing your retirement funds. Therefore, once you hear the news of your retirement or job change, the first step is to open a dedicated account and provide the account number to the relevant department at your company.
Receiving your severance pay in an IRP account defers taxation until pension receipt, which greatly helps in effectively increasing your assets.
2. The Trap of a 60% Cancellation Rate: Why Early Withdrawal Is Dangerous

It is very common for many people facing retirement or a job change to cancel their accounts because they cannot withstand financial pressure. In fact, statistics show that while vast sums of money have been transferred to dedicated accounts over the years, more than half of these funds have been withdrawn early and lost. If you break into your account to put out an immediate financial fire, all the tax benefits you have received up to that point are rendered useless. The moment you withdraw the funds as a lump sum rather than as a pension, a high tax rate is applied under the category of miscellaneous income tax.
The disadvantages incurred from early redemption or cancellation are far more fatal and severe than one might think. This is because your precious retirement funds, which should grow slowly through the power of compound interest, are rapidly eroded by taxes and surcharges. You may see people around you easily canceling their accounts because they are in a hurry for money, but this is no different from giving up on your retirement. Quietly maintaining the account until the designated age is the most beneficial action in the long run. If you need emergency funds, you need the wisdom to prioritize considering alternatives such as policy loans or other methods rather than canceling the account.
Canceling the account early requires you to return the tax deduction benefits you have received, and a high miscellaneous income tax is applied, resulting in significant losses.
3. Management Strategies: From Principal and Interest Guaranteed Products to AI Investing

Once you have opened a retirement pension account, you must seriously consider how to manage the money inside. If you dislike the risk of losing your principal, it is best to keep your funds in safe products such as fixed-rate deposits or government bonds. Recently, various financial institutions have introduced robo-advisor services based on AI algorithms and big data. These services analyze the investor’s profile and objectives to propose an optimal asset allocation portfolio and assist with periodic rebalancing.
In fact, pension management methods utilizing AI are evaluated as lowering the maximum loss rate and improving risk-adjusted returns compared to conventional methods. This opens up a path to pursue both stability and profitability through systematic management, even in volatile market conditions. If you are unsure about which products to invest in, you can actively utilize these automated asset management services. However, no matter how good the system is, it cannot be perfect during short-term market crashes, so you must maintain a long-term perspective. Accurately understanding your investment profile and appropriately adjusting the ratio between safe and risky assets is the key to successful management.
By utilizing AI-based asset management services or appropriately allocating safe assets, you can increase returns and reduce the risk of loss.
4. Pension Savings vs. IRP: The Order of Choice for Newlyweds and Early-Career Professionals
Early-career professionals and newlyweds often wonder whether they should fill their Pension Savings account or their Individual Retirement Pension (IRP) account first. Both products are excellent tools for retirement preparation and tax deductions, but there are clear differences in their purposes and characteristics. Pension Savings is a method where individuals voluntarily contribute their surplus funds, and the conditions for early withdrawal are relatively flexible. In contrast, the IRP account is a more comprehensive retirement pension account that is mandatory for receiving severance pay and allows for additional contributions.
Therefore, early-career professionals with limited surplus funds may find it advantageous to start with Pension Savings, as it is easier to manage and contribute to. For employees who are already working and steadily accumulating severance pay, it is naturally a priority to fill the limit of their IRP account. Maximizing the tax deduction limit by operating both accounts simultaneously is also a widely used tax-saving strategy among employees. You should carefully consider your income level and liquidity needs before deciding the order to avoid regret. The action you should most avoid is forcing yourself to max out the limits only to find yourself in a situation where you need to cancel the account due to an urgent need for cash.
It is wise to adjust the order of joining Pension Savings and IRP based on individual financial situations and liquidity needs.
5. Tips to Reduce Health Insurance Burden and Avoid Tax Bombs
One of the expenses that employees approaching retirement fear most is the monthly deduction of health insurance premiums and various taxes. Fortunately, receiving your retirement pension as a pension rather than a lump sum can significantly reduce your tax burden. Additionally, funds in pension accounts that meet certain conditions are not included in the income calculation for health insurance premiums, helping you avoid a spike in insurance costs. The core of asset management is preventing your hard-earned retirement funds from leaking out through taxes and insurance premiums.
You should also consider the strategy of switching from a Defined Benefit (DB) to a Defined Contribution (DC) plan when your salary decreases, to defend against losses in your severance pay. Remember that actively utilizing a dedicated account when receiving a voluntary retirement allowance can also maximize tax reduction benefits. Just as important as accumulating a large amount of money is thoroughly plugging the holes where money leaks out, which determines the quality of life after retirement. Do not rely on hearsay; understanding the exact tax laws and financial systems is the true beginning of wealth management. Starting today, please gradually check where your retirement pension funds are invested and how they are being managed.
By receiving funds as a pension and effectively utilizing related systems, you can reduce the burden of health insurance income calculation and wisely avoid tax bombs.
6. Final Check and Action for a Successful Retirement
We have examined in detail various methods and precautions for smartly protecting and growing your retirement pension. As retirement approaches, the shield protecting our assets must become stronger, and emotional cancellations are strictly prohibited. The first step is to choose account transfer receipt without hesitation when changing jobs or retiring to prevent tax leakage. After that, you should select products that match your investment profile and seek the help of AI asset management services if necessary.
Retirement funds are not a sprint but a long, tedious marathon that you must run for a lifetime. The sincerity of making small monthly contributions accumulates to become a sturdy pillar that creates a prosperous and stable life after retirement. Please log in to your financial institution’s app today to check the status of your retirement pension account and make necessary adjustments. Never forget that small attention and action combine to gift you economic freedom in your old age. If you continue to manage your assets wisely in line with changing financial systems, anyone can welcome retirement with a smile.
Only by managing your retirement pension account with consistent attention and a long-term perspective can you achieve a stable retirement and economic freedom.
Frequently Asked Questions
=