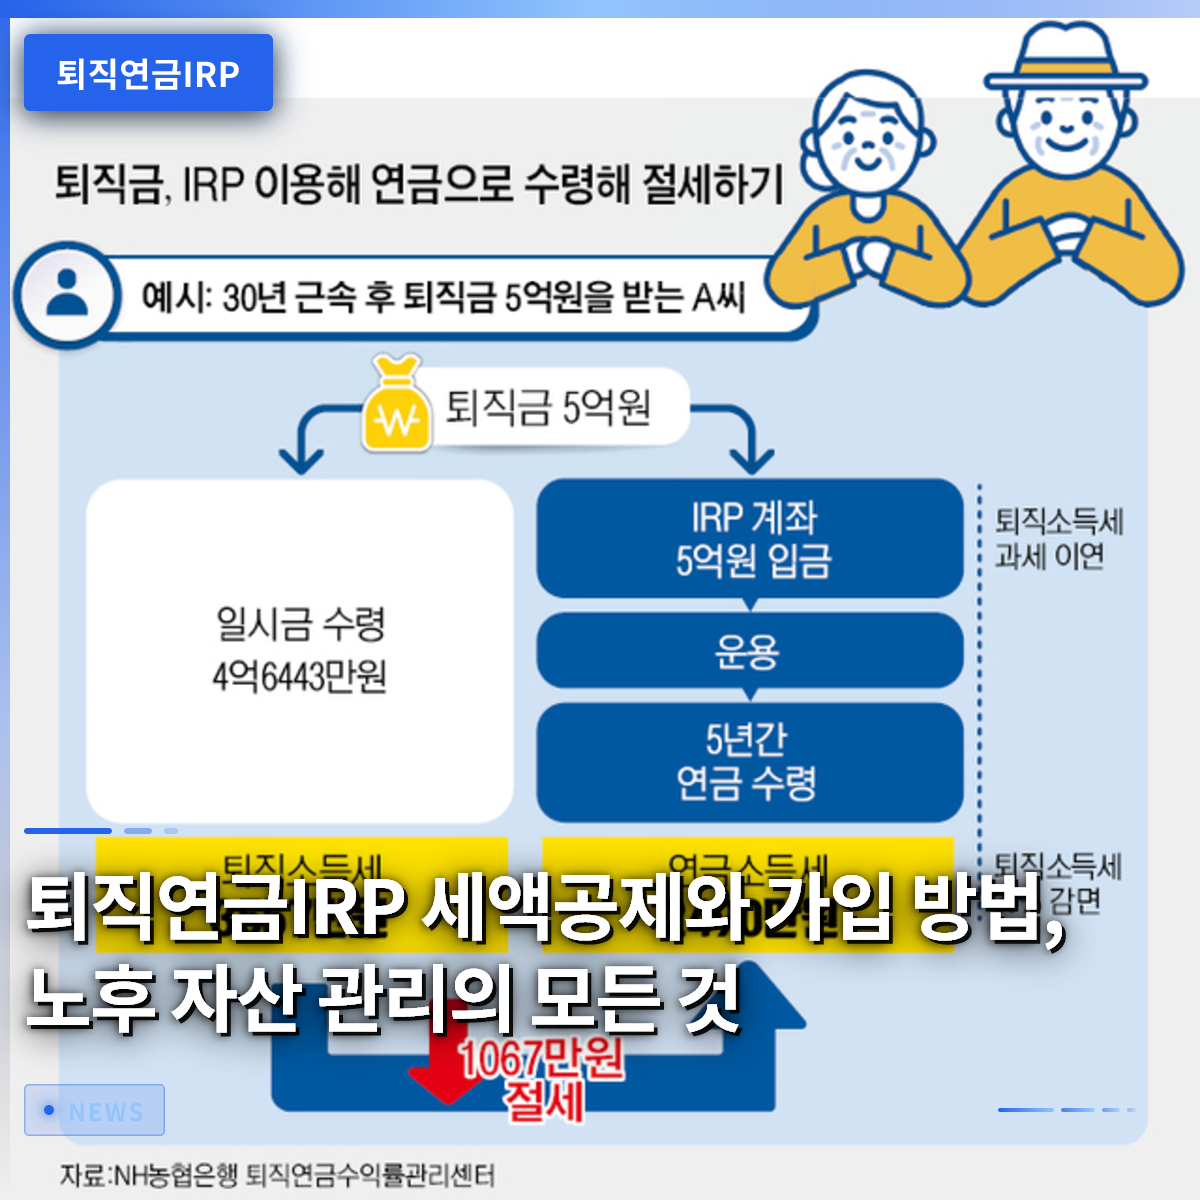
The Retirement Pension IRP (Individual Retirement Pension) account is an essential financial product that offers powerful tax deductions during annual tax settlement while simultaneously allowing you to build a stable retirement asset. Mr. Kim, an office worker, is steadily accumulating a lump sum by setting up automatic transfers of a fixed amount from his salary account to his IRP account on his payday every month. Beyond simply saving on taxes, it is gaining popularity among office workers because it allows them to secure their own living expenses for old age. However, when it comes to actually opening an account, many people feel overwhelmed by questions such as which financial institution to choose and how to manage the investments. Recently, various incentives have emerged, with some banks offering mobile gift vouchers to new customers. In this article, we will thoroughly examine the core benefits of the IRP, smart ways to utilize automatic transfers, and tips for safe asset management.
=
Retirement Pension IRP: Tax Deductions, How to Enroll, and Everything You Need to Know About Managing Your Retirement Assets
1. What is the Retirement Pension IRP and Why Should You Enroll?

The IRP, known as the Individual Retirement Pension, is a retirement account where employees can voluntarily enroll during their employment or continue to accumulate and manage their severance pay after changing jobs. Because it is a system established by the government to bolster income security in old age, it offers tax benefits that are on a completely different level from regular savings accounts or funds. You can receive tax deductions on a certain percentage of your annual contributions, making it a highly effective product for boosting your “13th month salary.” The eligibility has been broadened so that not only office workers but also self-employed individuals, public officials, and all economically active people with income can enroll. As retirement approaches, it is advantageous to start preparing early to reduce tax burdens and systematically grow your assets.
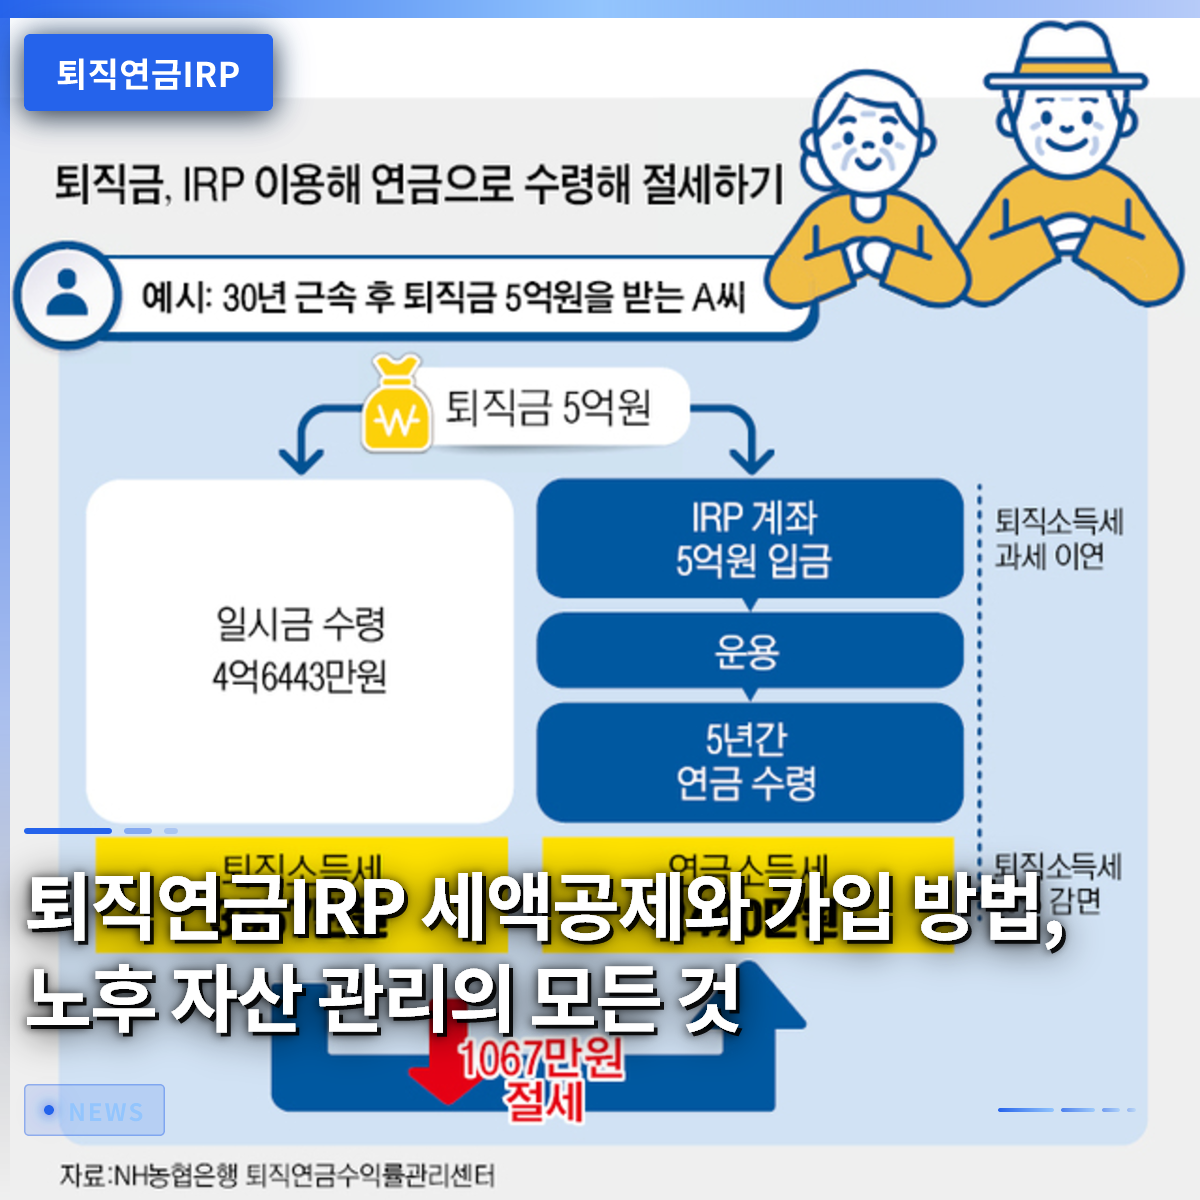
A significant advantage is that when you receive the funds as a pension after retirement, you are subject to a much lower pension income tax rate compared to general financial products. If you withdraw the entire amount as a lump sum, you may face a heavy tax burden, but receiving it in installments as a pension can save you a substantial amount in taxes. Recently, financial institutions have been actively running new enrollment events and mobile gift voucher giveaways to attract customers. By carefully taking advantage of these benefits, you can enjoy the bonus of earning some extra income. Opening an account now and starting small monthly contributions is the wisest investment you can make for your future self.
The Retirement Pension IRP is an essential account for retirement preparation, offering powerful tax deductions and favorable pension income tax rates.
2. Building Your Pension Seed Money with Payday Automatic Transfers

For successful asset building, it is crucial to create a system rather than relying solely on willpower. Setting up automatic transfers so that funds are deducted immediately on payday can effectively force you to save. For example, you can set an automatic transfer of 500,000 KRW from your salary account to your IRP account on the 25th of every month. Following that, you can set up transfers to a pension savings fund account, and finally, to an emergency fund or housing subscription account. By establishing this automated flow, money is saved before it even hits your hands, fundamentally blocking unnecessary spending.
Even for young professionals or beginners in wealth management, sticking to these automatic transfer rules can result in a noticeably increased balance after a few years. If starting with a large amount feels burdensome, there is no problem starting with a smaller amount, such as 50,000 or 100,000 KRW. The key is to develop the habit of consistent contributions without interruption to enjoy the magic of compound interest. While colleagues focus on consumption, the person who quietly builds assets will ultimately be the one smiling at retirement. Open your bank or securities app today and set your automatic transfer date to the day after your payday.
Setting up automatic transfers to your IRP immediately after payday helps reduce expenses and forces you to accumulate a lump sum.
3. Management Strategies: From Principal and Interest Guaranteed Products to Performance-Based Funds

The money deposited in your IRP account must be invested and managed by the subscriber, who gives specific instructions on which products to choose. Conservative investors can select deposits or fixed-term deposits that guarantee principal and interest to safely protect their capital. On the other hand, aggressive investors seeking higher returns can allocate assets to equity funds or Exchange-Traded Funds (ETFs). Recently, asset management programs equipped with artificial intelligence have emerged, allowing portfolios to be monitored automatically without the investor’s direct intervention. However, since some products eligible for tax benefits may be excluded from certain monitoring targets, it is essential to carefully review the specific regulations before enrolling.
If a subscriber does not give specific management instructions for a long period, a system activates where the financial institution manages the assets in designated products. This prevents idle assets from sitting as cash and helps ensure a minimum rate of return. It requires wisdom to appropriately adjust the ratio of safe assets to risky assets by considering your investment style and the remaining time until retirement. Rather than chasing high returns blindly, a balanced perspective that prioritizes both tax benefits and stability is important. You need to periodically check your account status and make slight adjustments to your portfolio according to market conditions.
You should appropriately mix principal and interest guaranteed products like deposits with performance-based products like funds and ETFs, according to your investment style.
4. Depositor Protection Limits and Standards for Safe Asset Management
The first factor to consider when choosing a financial product is whether your principal can be kept safe. Many people believe bank deposits are always safe, but there is a limit to the amount protected per financial institution. According to the Depositor Protection Act, the state protects up to 100 million KRW per person, including principal and a certain amount of interest. IRP accounts are also safely covered by this protection only when managed as deposits or protected products. Therefore, it is wise to diversify your investments across multiple institutions rather than concentrating too much money in a single one.
Foreign currency deposits and various retirement pension products can also benefit from depositor protection if they meet specific criteria. However, not all financial products are automatically protected, so it is essential to clearly confirm whether a product is eligible for protection before enrolling. Since you are dealing with your precious retirement assets, a meticulous attitude that checks every detail is fundamental to wealth management. If you understand the depositor protection limits and diversify your assets, you can withstand economic crises with peace of mind. Assets built up steadily within the safe fence of protection are the most powerful weapon for a secure old age.
Assets managed as deposit products within an IRP are eligible for depositor protection up to 100 million KRW per financial institution.
5. Maximizing Tax Deduction Limits and Year-End Settlement Tax-Saving Tips
As the year-end tax settlement season approaches, the biggest concern for office workers is how to get more tax refunds. The IRP, when combined with pension savings accounts, offers exceptional tax deduction benefits up to a certain annual limit. Since up to 13% to 16% of your contributions can be directly deducted from your final tax amount, the perceived tax-saving effect is significant. The deduction rate varies based on your total income, so it is advantageous to accurately assess your salary level and plan your contributions accordingly. Rather than rushing to fill the limit at the end of the year, spreading contributions consistently throughout the year is the best way to reduce financial burden.
To maximize tax benefits, a strategy of combining pension savings and IRP to reach the optimal contribution limit is widely used. For example, you can maximize tax efficiency by first filling your pension savings limit and then using the remaining limit for the IRP. If you reinvest the taxes saved this way, you can create a virtuous cycle that further enhances compound interest effects. Instead of relying on hearsay from acquaintances, you should calculate accurately based on guidance from the National Tax Service or reliable financial information. Reducing taxes is equivalent to increasing returns, so utilizing tax-saving products is not optional but essential.
By utilizing the IRP, you can receive tax deductions of up to 16% of your contributions during year-end settlement, saving valuable taxes.
6. Long-Term Investment Mindset and Practice for a Successful Retirement
Retirement is a future milestone everyone will face, but the quality of life varies greatly depending on how it is prepared. Instead of reacting emotionally to short-term stock price fluctuations, you need the attitude to quietly accumulate assets while looking toward the distant future of 10 or 20 years away. Like Mr. Kim, the simple habit of consistently practicing automatic transfers and periodically checking your account will ultimately make a big difference. Only those who recognized the importance of pension accounts in their early careers and started preparing little by little can enjoy a comfortable and abundant old age. Open your wallet now, cut unnecessary spending, and open an account with the mindset of investing in your future self.
While the financial market is always volatile and unstable, investing in assets that trend upward in the long term will eventually lead to success. You should smartly grow your assets by actively utilizing government institutional support and various financial institution event benefits. Planning asset reallocation strategies in advance to wisely bridge the retirement gap is also an important part of retirement preparation. Based on what you have learned today, turn your postponed pension account opening and automatic transfer setup into action right now. Your wise choice today will return as a solid and warm retirement asset years from now.
With a long-term perspective and consistent accumulation of pension assets, anyone can achieve a stable and abundant retirement.
Frequently Asked Questions
=