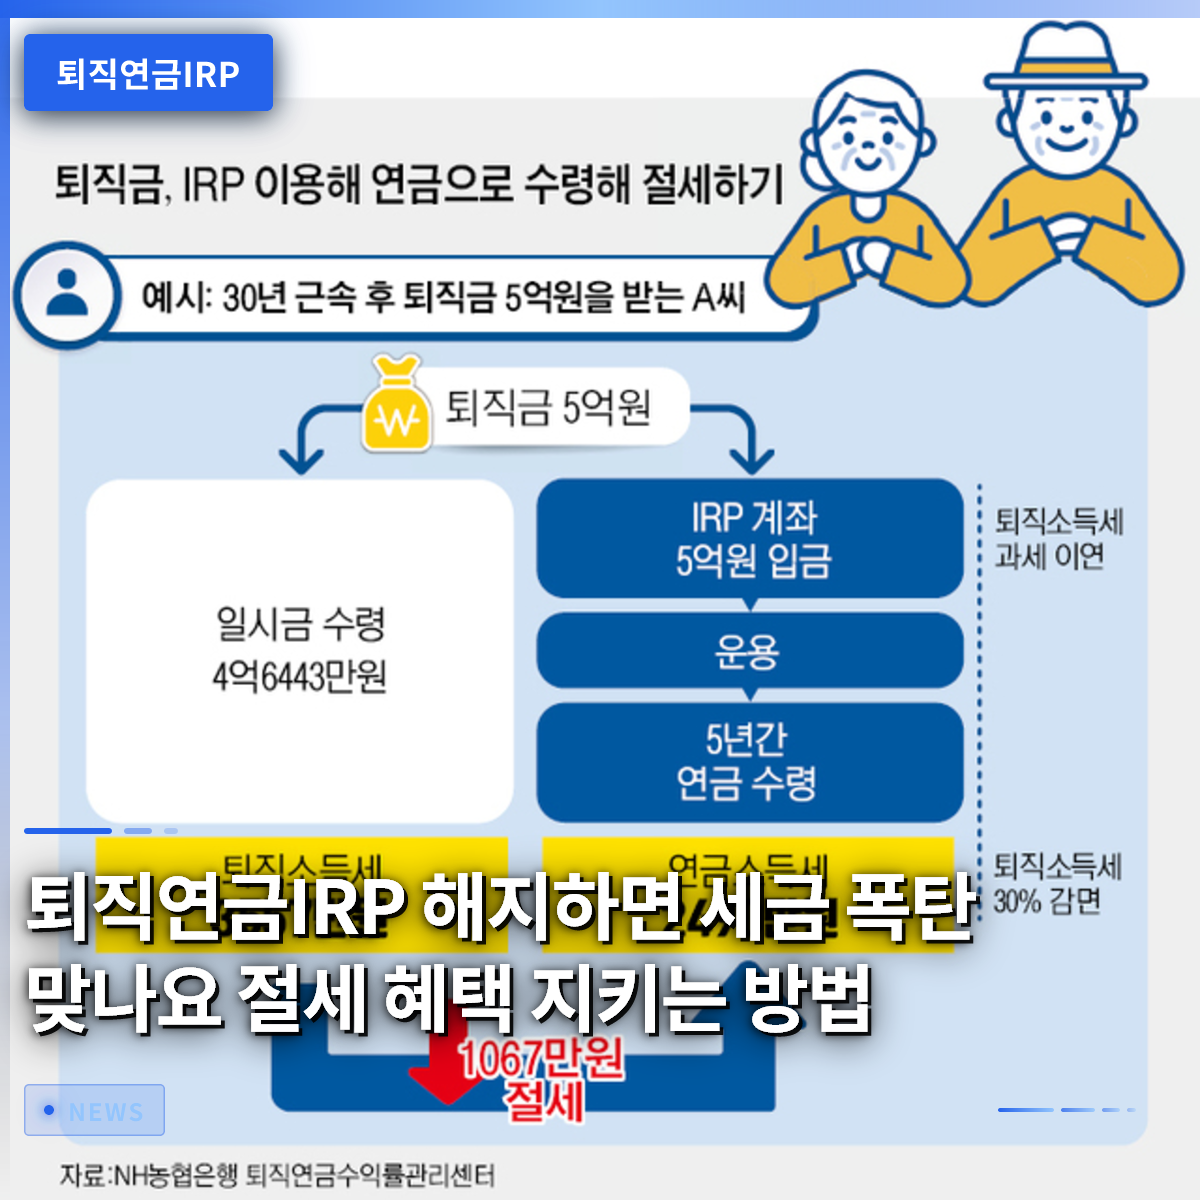
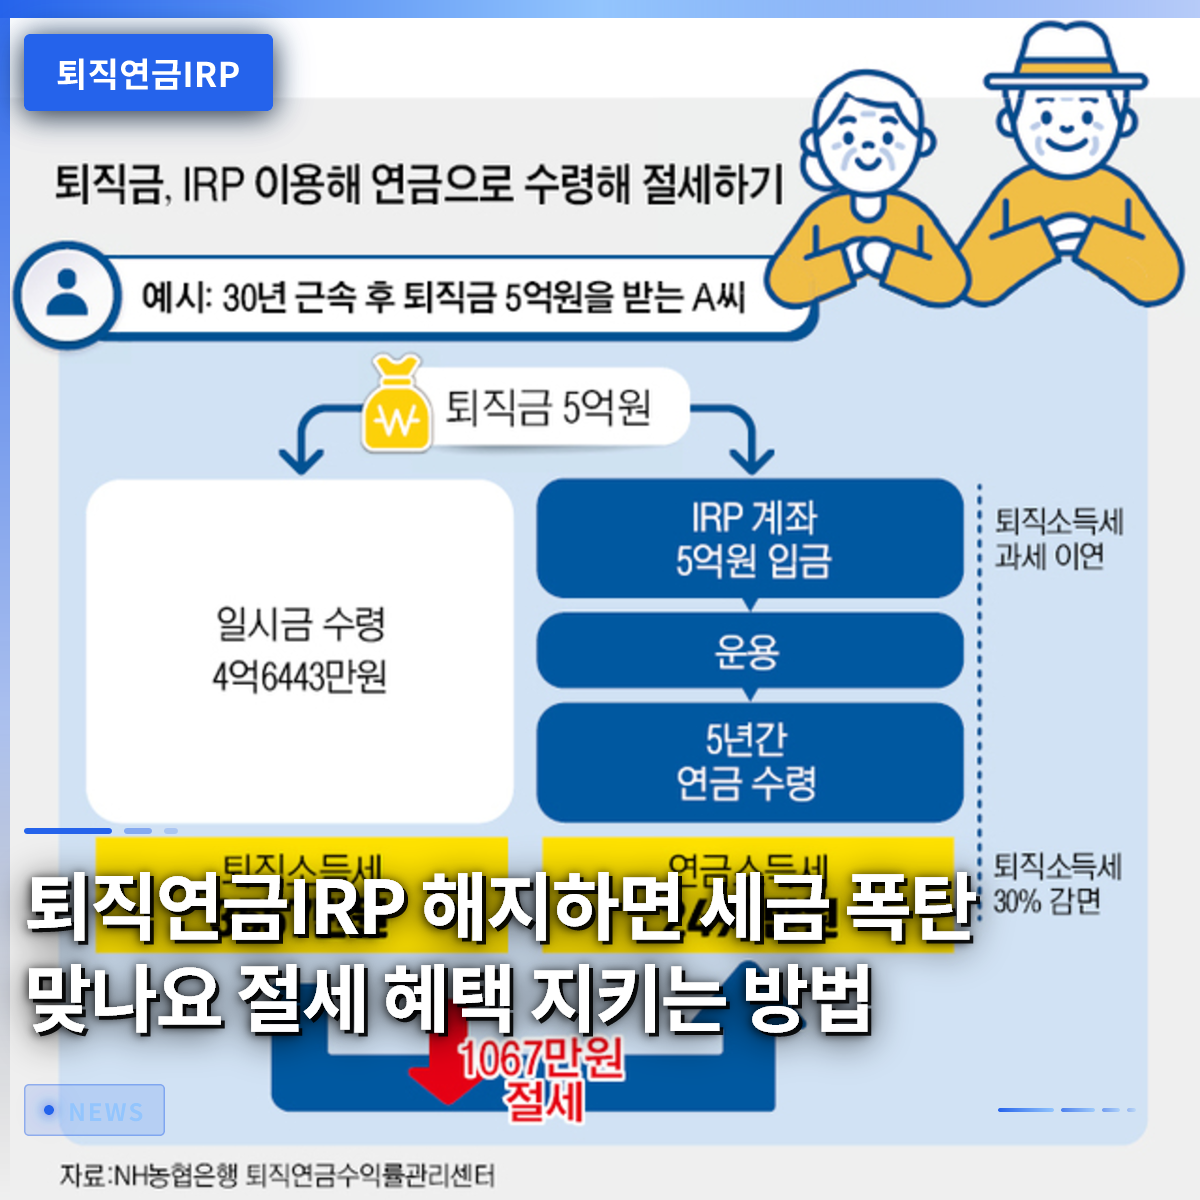
If you suddenly close your Individual Retirement Pension (IRP) account, you will be required to return all the tax deduction benefits you have received and pay severance income tax all at once. Therefore, it is absolutely forbidden to close the account without careful consideration just because you need cash urgently. Mr. Kim, an office worker, transferred his severance pay to an IRP account but closed the entire account because he needed a lump sum. As a result, he faced a back-tax assessment of several million won during his comprehensive income tax filing the following year and deeply regretted his decision. Since pension accounts serve as a sturdy fence for your retirement and a core tool for tax savings, it is wiser to utilize the system intelligently rather than breaking it midway. In this article, we will thoroughly examine the correct methods for receiving funds from an IRP, tax-saving strategies, and recently introduced convenient systems. Let us explore specific ways to protect your valuable retirement funds and significantly reduce your tax burden through wise asset management.
=
Will Cashing Out Your IRP Trigger a Tax Bomb? How to Preserve Your Tax Benefits
1. What is an IRP and Why Is It Necessary?

An IRP is an essential personal pension account that allows you to pool your company-paid severance pay with additional personal contributions, grow them safely until retirement, and enjoy tax deduction benefits. In the past, it was common to receive severance pay directly into a bank account upon leaving a job and use it for living expenses. However, now it is mandatory to transfer and manage these funds in a pension account under your own name. You can easily hear laments from people around you about their retirement funds being insufficient because their severance pay melted away every time they changed jobs; this account prevents such leakage. The reason more office workers are making additional contributions to get tax refunds during year-end settlement is precisely due to the powerful tax-saving appeal of this product. Since it is a system strongly recommended by the state to create a stable cash flow in old age, understanding its structure is of utmost importance. By consistently contributing a fixed amount each month, you can enjoy the double benefit of saving on taxes and preparing for the future. Mr. Park, who actively utilized this account from the start of his career, reinvested the money he received back through tax deductions each year, significantly growing his retirement assets. As such small habit differences can create enormous asset gaps in just a few years, you should open an account and start contributing immediately.
An IRP is an essential personal pension account that handles severance pay management and tax deductions simultaneously to prepare for retirement.
2. The Fearsome Tax Bomb You Face Upon Early Termination

If you withdraw funds early or terminate your IRP, you must give back all the tax-saving benefits you have enjoyed, so special caution is required. Under tax law, a very low tax rate is applied when receiving pension income, but early termination results in a withholding tax of a whopping 16.5% under the category of “other income.” Mr. Lee, an office worker, broke his pension account to withdraw money to increase his deposit for a rental housing contract, only to be stunned by the unexpectedly large tax deduction amount. It is a moment when the efforts of saving diligently to receive tax deductions are turned to dust in an instant, resulting in an outcome worse than a regular deposit. Unless there are special circumstances such as purchasing a home as a non-homeowner, bankruptcy, or a natural disaster, early termination is a deadly poison for asset growth. It is wiser to look into collateral loans or other legal funding methods first rather than breaking the account when you need a lump sum immediately. It is not hard to see people around you venting frustration over hitting a tax bomb; this is mostly because they did not properly check the details of the system. Therefore, you should maintain the account until retirement age as much as possible, and if you urgently need money, carefully consider the exceptions allowed by law.
Early termination of a pension account incurs a high 16.5% other income tax, causing you to lose all tax-saving benefits.
3. The Natural Flow from Defined Contribution to Personal Pension

Upon leaving a company, the Defined Contribution (DC) pension assets managed by the company must be transferred to a personal pension account under your own name for the formal receipt process to begin. During this process, you can enjoy the benefit of tax deferral, meaning severance income tax is not immediately imposed and taxation is delayed until you receive it as a pension. Mr. Jung, an office worker, visited a bank immediately after receiving his severance pay to go through the transfer procedure and felt greatly relieved to learn that he could let the money grow without paying taxes right away. If you skip this process and receive the funds directly into a regular bank account, you must pay severance income tax immediately, causing a significant loss in asset growth. After completing the transfer, you can choose to receive the funds as a lump sum or in monthly pension installments, depending on your lifestyle. To increase the stability of your living expenses in old age, it is much more advantageous from a tax perspective to receive the funds as a pension over a long period. It is essential to fill out documents according to the guidance of your company’s pension department and verify that the funds are accurately deposited into your personal account. Even just understanding this basic flow can perfectly prevent you from unfairly losing your valuable severance pay to taxes.
Upon retirement, DC assets must be transferred to a personal pension to enjoy tax deferral benefits and lay the foundation for pension receipt.
4. How to Use the In-Kind Transfer System to Switch Brokerages
By utilizing the recently introduced in-kind transfer system, you can move your existing stocks or funds to another financial institution without selling them when you change providers. In the past, to change management institutions, you had to sell all your holdings and convert them to cash before moving, which carried a high risk of loss depending on market conditions. Mr. Choi, an office worker interested in investing, wanted to switch to a brokerage with lower fees and a wider variety of products but hesitated due to concerns about the disadvantages of selling. However, thanks to this system, he was able to easily move to his desired financial institution while maintaining his assets, allowing him to continue with satisfactory asset management. When you wish to transfer, you can apply through the app or visit the financial institution where you want to start trading, and the complex procedures will be handled automatically. Through this system, subscribers have gained the powerful authority to freely choose institutions that offer better fee conditions or diverse automatic purchase features. In an era of prolonged high interest rates, it is advisable to actively utilize this system if you want to finely adjust the ratio of safe assets to risky assets.
Using the in-kind transfer system allows you to safely switch to a brokerage with favorable fees without selling your existing holdings.
5. Safe Asset Rebalancing Strategies in an Era of Prolonged High Interest Rates
In times like now, when interest rates remain high and financial market volatility has increased, asset allocation and rebalancing strategies within your pension account are very important. Rather than selling all equity products in your account just because the stock market is shaking, it is wiser to review the purchase settings for the funds you contribute monthly. Mr. Han, an office worker nearing retirement, was about to panic-sell everything when government bond yields spiked and the market became unstable, but he increased the proportion of safe assets after receiving expert advice. As such, rather than being swayed by market trends, you need the ability to periodically review and adjust your portfolio according to your investment style and retirement timing. Since pension accounts are funds meant to be grown over decades, investing with the discipline to stick to principles without being shaken by short-term shocks is the key to success. By maintaining a balance between safe and risky assets through regular rebalancing, you can remain relatively calm even in unexpected market crashes. The strategy of using automatic purchase features to consistently accumulate quality assets monthly is the most certain way to maximize the effect of compound interest.