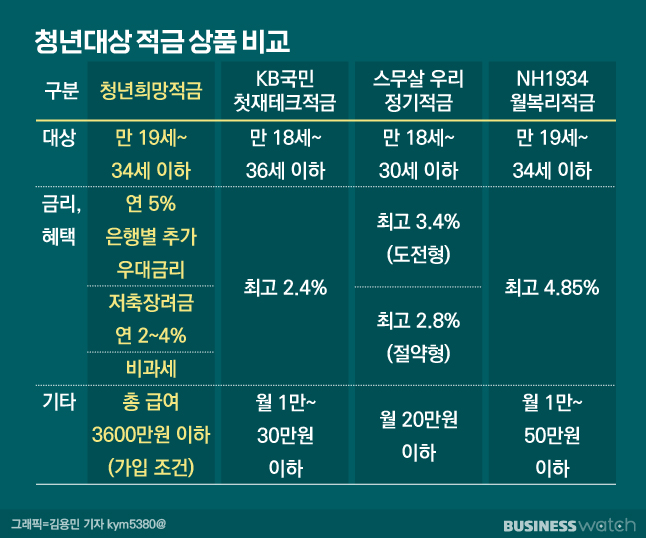
Many young people find themselves at a crossroads after their Youth Hope Savings Account reaches maturity. They hold a lump sum of savings but struggle to find a suitable investment or savings method. Since this asset was built through diligent monthly savings over the past few years, failing to manage it wisely can lead to quick disappointment. While stories of friends making money in stocks or cryptocurrencies may be tempting, it is crucial to keep an eye on government-supported products that maximize benefits while protecting the principal. In this article, we will thoroughly examine asset management strategies for those whose Youth Hope Savings Accounts have matured and how to seamlessly switch to new government-supported savings products. We will clearly compare the differences between various policy products that may look similar on the surface but differ significantly in substance. Let’s carefully explore the most reliable guide to growing your assets.
=
How to Manage Your Youth Hope Savings Account After Maturity: A Complete Guide to Switching to the Youth Future Savings Account
1. The Dilemma After the Youth Hope Savings Account Matures
Mr. Kim, an office worker, has finally completed his Youth Hope Savings Account term, depositing several tens of millions of won into his account. He has been consistently setting aside 500,000 won from his monthly salary, and seeing the balance makes him smile. However, this joy is short-lived as he hits a wall of uncertainty about where to put this lump sum. Putting it in a regular bank deposit seems futile given the low interest rates that fail to keep up with inflation. On the other hand, jumping into the volatile stock market feels risky, potentially causing sleepless nights. It is common to find young people in this situation, holding a significant amount of money but feeling lost. As the cycle of previous government products aimed at helping youth build assets comes to an end, it is time to consider the next step. Rather than impulsively increasing consumption or all-in on risky investments, one must find another channel to continue the momentum of government support. Fortunately, financial authorities are well aware of these concerns and have prepared various follow-up options. Never forget that wise asset management begins at this turning point.
A new asset formation strategy is needed to resolve the confusion of managing a lump sum after the Youth Hope Savings Account matures.
2. Utilizing Lump-Sum Deposits in the Youth Savings Account
If you have diligently saved in the Youth Hope Savings Account and secured the maturity funds, you can actively utilize the lump-sum deposit system of the Youth Savings Account. This system is a clever way to shorten the investment period and maximize interest benefits by paying the maturity amount in one go. Depositing a lump sum in advance increases the principal on which interest accrues, leading to a significant difference in the final payout compared to small monthly deposits. In fact, one of my acquaintances deposited their maturity funds into this system and achieved returns far exceeding those of regular savings accounts. Of course, there is the hassle of carefully re-checking eligibility criteria and income requirements. The process of verifying whether you qualify and obtaining income proof documents can feel tedious. However, going through this process allows you to grow your assets under much more favorable conditions than others. It is wisest to consult with bank staff or online counseling services to find a deposit method that perfectly suits your situation. A little effort and diligence can work wonders, completely changing the numbers in your account balance years down the line.
Making a lump-sum deposit of your Youth Hope Savings Account maturity funds into the Youth Savings Account can shorten the term and maximize interest income.
3. Second Application Schedule for the Youth Future Savings Account
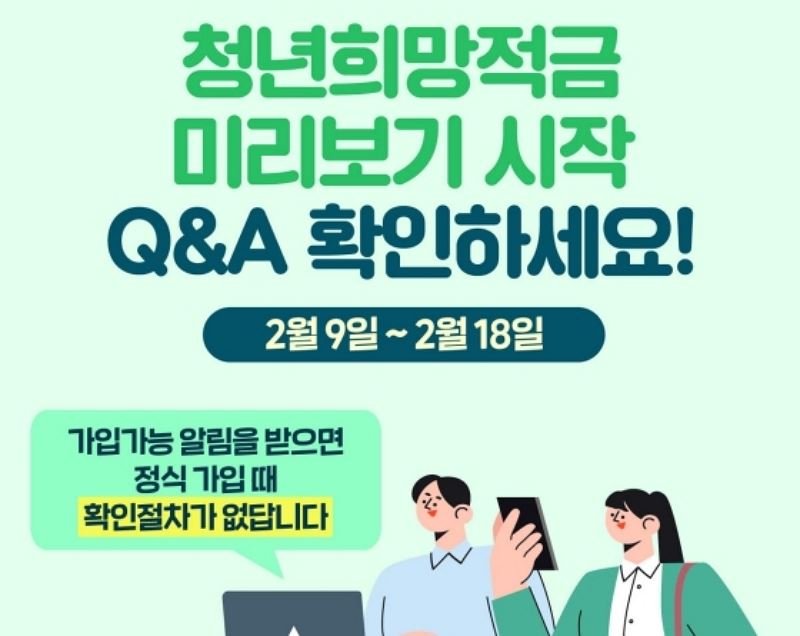
According to recent announcements from the Financial Services Commission, the second application period for a new product with enhanced benefits is approaching. Since formal applications will begin in October, young people who unfortunately missed the first recruitment round will have another chance. This round is expected to significantly reduce user inconvenience, as the application review process has been improved to be smoother and faster. In particular, the verification system for preferential benefits for young people working at small and medium-sized enterprises has been strengthened, allowing more people to enjoy the benefits. If you fail to check the schedule in advance and miss the application period again, you will likely feel deep regret. It is advisable to check the required documents in advance and set up pre-notifications through the relevant bank’s mobile app. Share information with friends and act one step ahead of others to ensure you never miss this valuable opportunity. Since government-supported products often have limited budgets or strict conditions, quick decision-making and execution are paramount. Prepare thoroughly for the upcoming period to firmly grasp this second golden opportunity to grow your assets.
You can secure an application opportunity by understanding the second recruitment schedule starting in October and preparing your documents in advance.
4. Switching Procedures and Points to Note
If you wish to switch from an existing product to a new one, you must strictly follow the designated procedure. If you rashly cancel your existing account, you may fail to receive the full government subsidy or face disadvantages, so extreme caution is required. First, you must complete the application and review for the new product and receive confirmation of eligibility. Only after opening the new account should you apply for a special early withdrawal from the existing product. If this order is reversed or any step is missed, you may face the unpleasant situation of having to restart the procedure from scratch at the bank counter. In fact, many young people post regretful stories on communities about how they hastily canceled their existing accounts first and ended up missing out on some benefits. While managing administrative procedures step-by-step in a busy daily life can be tiring, being meticulous is when attention translates into money. It is safest to carefully read the official guides provided by financial institutions and call the customer service center directly if you have any questions. Even a complex process can be completed without difficulty if you follow it step by step.
To avoid losses, you must first obtain approval for the new product before canceling your existing one.
5. Realistic Alternatives for Low-Income Youth
No matter how good the government-supported savings system is, there are certainly young people for whom paying a fixed amount every month is a heavy burden. In fact, data from the Ministry of Health and Welfare shows that the primary reason for early account cancellation is giving up on one’s own goals. Balancing soaring living costs such as rent and food while also saving is far more exhausting and stressful than one might think. If you set an unreasonably high amount and give up midway, breaking the savings account, all the effort and time invested will be wasted. Therefore, flexibility is needed to set a monthly deposit amount that is realistically sustainable given your economic situation. It is far more advantageous to proceed steadily and long-term according to your own financial circumstances rather than worrying about others’ opinions or trying to fill the maximum amount. The government is also taking these hardships into account, with trends toward increasing matching subsidies and expanding customized systems for small business owners and SME workers. Warm concern from the community and institutional support must go hand in hand to help young people enduring difficult times avoid despair and achieve self-reliance. Simply maintaining the habit of consistent saving without losing your own pace means you have already succeeded halfway.
To prevent early cancellation, you should set a realistic amount that matches your income rather than forcing excessive savings.
6. Future Directions for Asset Management
How you carry forward the spark of saving started with the Youth Hope Savings Account will determine our economic freedom in the coming years. Actively utilizing the various government financial support systems for youth is no longer an option but an essential strategy. Rather than just planning to spend the maturity funds in the short term, you must conceive a portfolio to grow your assets from a long-term perspective. You should use asset management tools via mobile apps to check your monthly income and expenses and cultivate the habit of reducing unnecessary spending. It is important to act quickly in line with upcoming recruitment schedules and diligently collect useful information from your surroundings. If it is difficult to find all financial information on your own, consistently check news from youth communities or reliable financial media. Small practices will eventually build a solid economic foundation, serving as a sturdy support during the challenging early years of your career. Starting today, check your account balance and maturity date, and take a strong first step toward a new leap. We cheer for wise choices and consistent saving habits for a bright and stable future for young people.
You should actively utilize government support systems and build an asset management portfolio from a long-term perspective.
Frequently Asked Questions
=