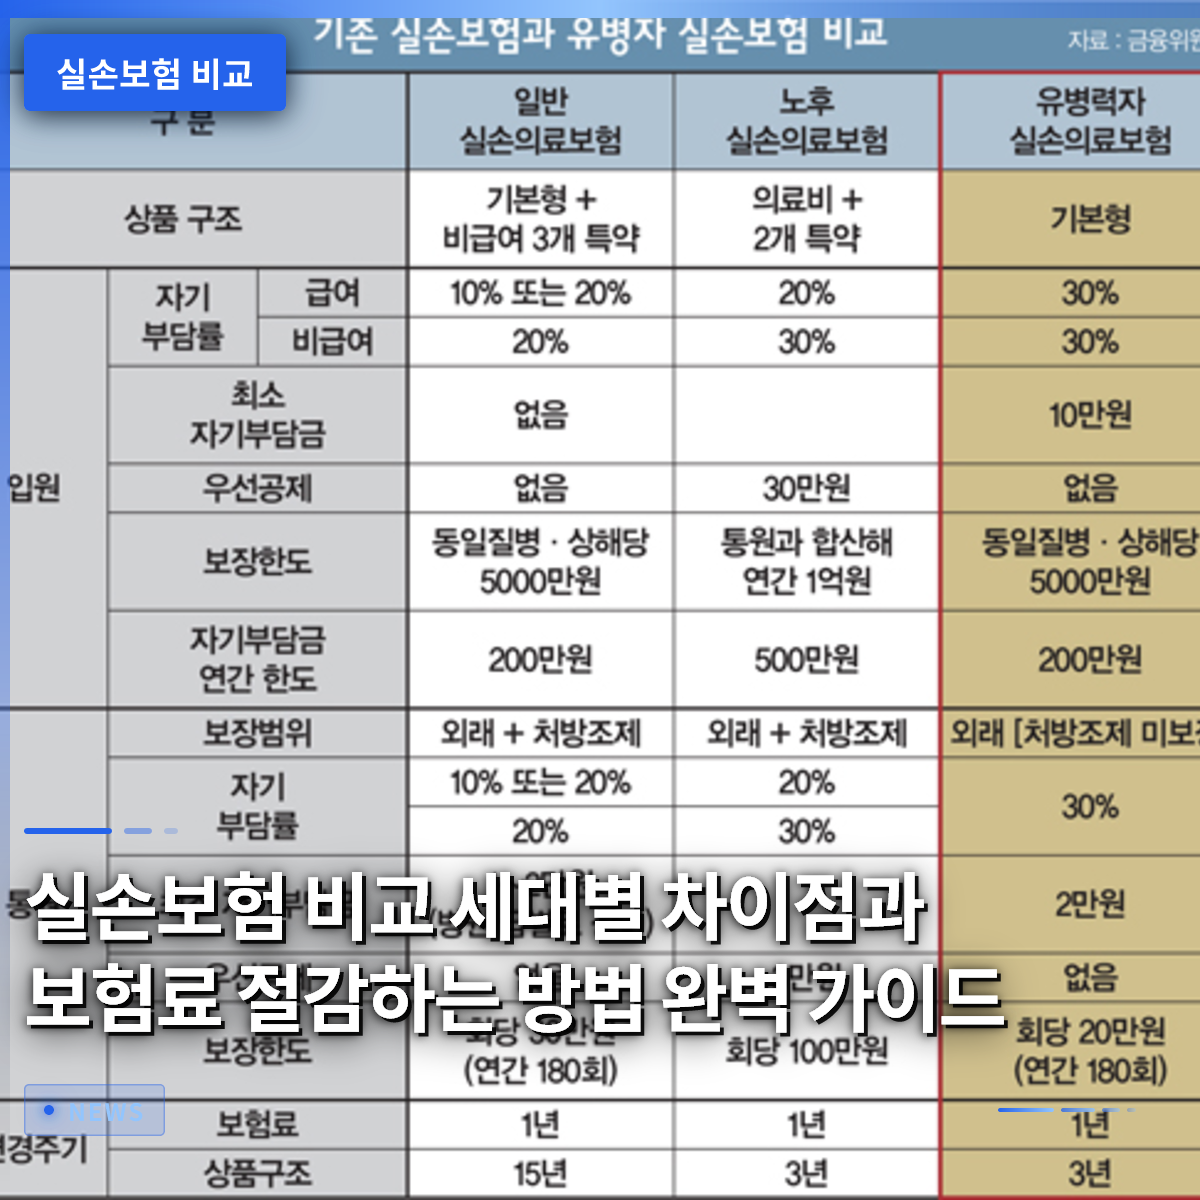
Just because the premiums for your existing out-of-pocket medical insurance have risen significantly, you should absolutely not cancel your policy and switch to the latest product without careful consideration. As of 2026, many people are attempting to compare out-of-pocket medical insurance plans to reduce their hospital bill burdens, but failing to understand the differences in coverage scope and co-payments across different generations can actually lead to significant financial losses. In fact, I have frequently seen cases where people casually canceled their older policies because the premiums felt burdensome, only to regret it later when they faced a massive surgical bill. Therefore, meticulously comparing the terms of your current contract with the pros and cons of the latest products is of utmost importance. In this article, we will trace the evolution from the first generation of policies to the latest products and examine specific criteria for making the most advantageous choice for you. Let’s break down a smart enrollment strategy that protects your wallet without being misled by complex terminology.
=
A Complete Guide to Comparing Out-of-Pocket Medical Insurance: Generational Differences and How to Save on Premiums
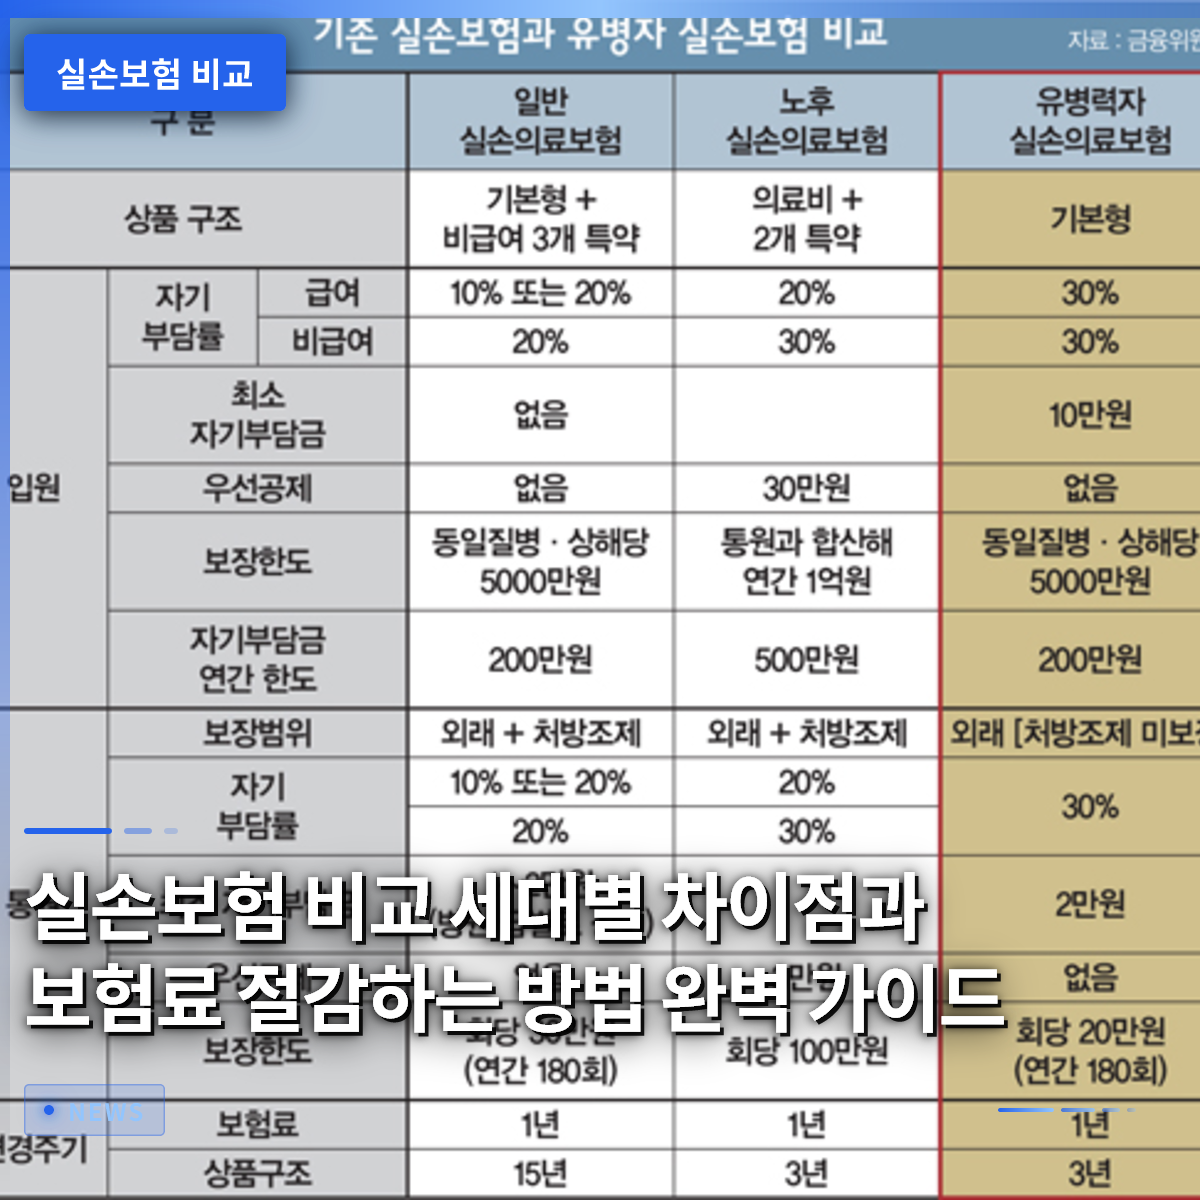
1. The Evolution of Out-of-Pocket Medical Insurance by Generation and Key Differences
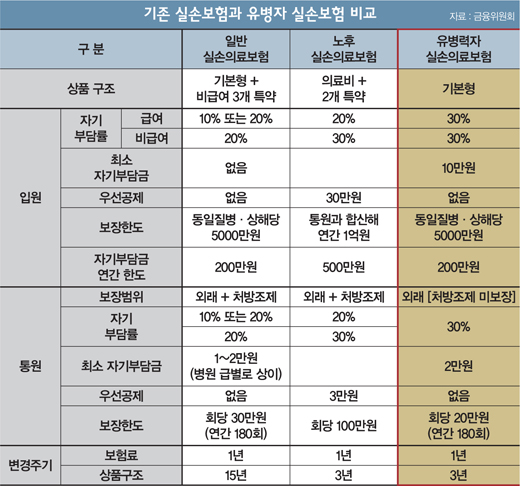
Out-of-pocket medical insurance has evolved significantly in terms of coverage conditions and co-payment structures, ranging from the first generation to the latest generation depending on the enrollment date. Past first and second-generation products offered negligible or very low out-of-pocket costs for hospital bills, providing overwhelming benefits from the patient’s perspective. However, due to this high level of coverage, insurance companies’ loss ratios soared, ultimately causing renewal premiums for all policyholders to skyrocket to unmanageable levels. In contrast, the latest products from the fourth generation onward have been completely restructured to prevent over-treatment, featuring a system where premiums are discounted or surcharged based on the volume of non-covered medical services used. As a result, healthy policyholders who rarely receive non-critical non-covered treatments can significantly lower their premiums by switching to the latest products. Conversely, for those who frequently visit hospitals or require consistent treatment for chronic diseases, maintaining their older contracts may be far more advantageous. Ultimately, accurately understanding the differences between generations and comparing them against your own health status and frequency of hospital visits is the starting point for any comparison. It is not necessarily true that a cheaper premium is better; you must weigh the extent of coverage you will receive against your fixed monthly expenses.
Co-payments and coverage scopes vary significantly depending on the enrollment date, so you should compare the characteristics of each generation according to your hospital usage habits.
2. Essential Items to Check Before Canceling an Existing Contract

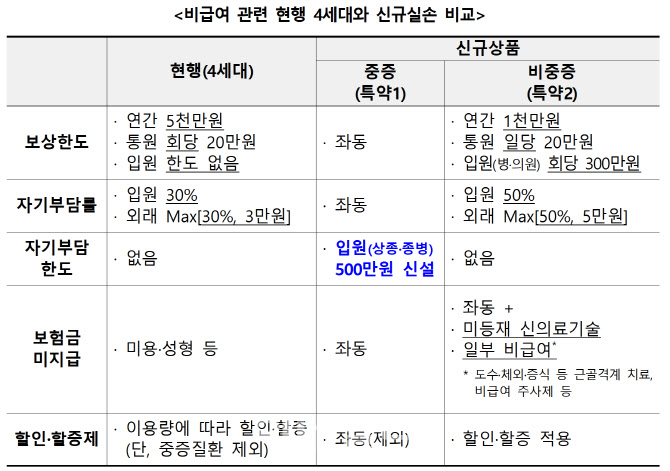
When considering whether to keep or switch an older out-of-pocket medical insurance policy, the first thing to examine is the currently applicable co-payment ratio. Older products required patients to pay for the full amount or a very small portion of hospital bills, whereas the latest products require patients to cover a significant percentage of non-covered items. For example, if you frequently receive non-critical non-covered treatments such as physical therapy or vitamin injections, your actual hospital expenses could surge if you switch to the latest product. Additionally, you must carefully consider the renewal cycle of your existing contract and the expected magnitude of future premium increases to calculate the long-term profit and loss. Many customers regret having impulsively applied for a switch based solely on simple rankings or promotional articles found online. You need the wisdom to meticulously compare your current conditions with the new conditions item by item, either through consultation with an insurance agent or via comparison websites. The most reliable method is to look through your hospital receipts from the past year and visually confirm exactly how much you spent on which treatments. A product that others say is good can be a poison for you, so you must focus thoroughly on your individual medical consumption patterns.
Rather than simply comparing premiums, you should meticulously cross-reference your past hospital usage history with changes in co-payments and make a careful decision.
3. Tips for Claiming Insurance Payouts Easily Without Documents
Surprisingly, there are many people around us who give up on claiming hospital bills because they find the complex document preparation process for out-of-pocket medical insurance a hassle. The past method of individually issuing medical receipts and detailed statements, then mailing them or uploading photos, is gradually disappearing. Recently, major hospitals and insurance companies have connected their computer systems, allowing claims to be processed immediately with just simple identity verification, without the need for separate documents. Large hospitals adopted this convenient claiming method relatively early, greatly enhancing patient convenience. However, for small local clinics or pharmacies, the integration rate has not yet reached 100%, so there are still occasional cases where you need to collect receipts directly. Nevertheless, non-face-to-face claiming technology using smartphone apps is developing daily, and it is expected to become common in the future for patients to receive reimbursement immediately upon leaving the hospital. If you are missing out on insurance payouts you are rightfully entitled to simply because it is a hassle, please open your smartphone today and try using the easy claim feature.
As computer system integration expands, you can easily claim insurance payouts via smartphone without documents, so you should actively utilize this feature.
4. The Relationship Between Specific Diseases, New Treatments, and Out-of-Pocket Medical Insurance
With the rapid advancement of medical technology, prescriptions in new areas, such as diabetes treatments and obesity management injections, are exploding in number. Whether these latest treatments fall within the scope of national health insurance or out-of-pocket medical insurance is a core factor determining patients’ financial burden. For example, there is a safety net that can significantly lower out-of-pocket costs if you are registered as a severe disease patient through a certain national certification system, but it is easy to miss out on these benefits if you are not well-informed about the system. People with financial leeway try to prepare for massive medical bills in advance through private out-of-pocket insurance, but they can face difficulties if they do not accurately understand the coverage criteria. The increasing number of cases where people travel abroad for “medical tourism” to find half-price injectables is ultimately due to the limitations of domestic medical costs and insurance coverage. Insurance companies adjust their terms and conditions meticulously every time a new treatment emerges, so you must frequently check whether your enrolled product covers the specific new technology treatment. You need the discernment to look beyond simple premium comparisons and assess whether the policy provides a sturdy shield against diseases you are statistically likely to develop.
You should understand the insurance coverage scope for new treatments and severe diseases and meticulously compare coverage that matches your health risk factors.
5. Smart Enrollment and Review Strategies Using Online Comparison Sites
You need the wisdom to actively utilize the numerous out-of-pocket medical insurance comparison sites available in the market to find the product that best suits you. Various online comparison platforms neatly organize estimated premiums by age and gender, as well as detailed coverage conditions, allowing you to see them at a glance. By lining up and comparing conditions from multiple companies simultaneously, you can easily identify any unnecessarily expensive special clauses. However, do not be misled solely by some promotional information that emphasizes only low prices; you must comprehensively examine the actual coverage content and the company’s solvency. It is also a good method to refer to guides for checking travel insurance or existing contracts before long holidays such as Chuseok or year-end. Rather than unconditionally eliminating old insurance, it is much more desirable to approach it from the perspective of remodeling your coverage to fit your current economic situation and health status. Seek objective advice from experts or cross-verify multiple comparison materials yourself to frugally reduce your fixed monthly expenses.
Use reliable comparison platforms to contrast conditions from multiple companies and remove unnecessary special clauses to eliminate the “bubble” in your premiums.
6. A Wise Attitude and Outlook for Dealing with Premium Increases
Every year, when the renewal period arrives and we receive premium notices that have snowballed in size, it is a common sentiment among office workers to let out a sigh. In a situation where prices are rising and income is limited, the fixed insurance premiums deducted monthly place a considerable burden on household finances. Looking ahead at changes in the medical environment, it is certain that insurance companies’ standards for preventing over-treatment will become even stricter. Therefore, rather than simply enduring, a flexible attitude is required to periodically check your frequency of hospital visits and switch to a rational generation of products. Even if it feels like a minor adjustment right now, calculating the total cost over decades from a long-term perspective will make it clear which choice is beneficial. Out-of-pocket medical insurance is a precious existence that serves as both the most basic safety net for protecting our health and a sturdy pillar in our lives. Based on the generational differences and comparison tips learned today, please make the wisest decision to protect your bank account right now.
To prepare for the premium burden during renewal periods, you should check your medical consumption patterns from a long-term perspective and respond flexibly.
Frequently Asked Questions
=