If you simply leave your retirement pension account unattended, it may fail to keep pace with inflation, causing your valuable assets to shrink significantly after retirement. Therefore, you must start managing it actively right now. The size of your assets ten years from now will vary dramatically depending on how you invest the pension funds your company accumulates for you each month. If your colleagues are already diversifying their investments across various products to secure returns while you have only kept your money in deposit products, you might feel anxious. In this article, we will thoroughly explore how to smartly manage Defined Contribution (DC) and Individual Retirement Pension (IRP) accounts, as well as the recently introduced convenient trading methods. By reading this article to the end, you will definitely gain concrete practical steps to protect and grow your retirement funds.
=
A Complete Guide to Managing DC Pension IRP Accounts and Core Strategies for Boosting Returns
1. Understanding the Basics of the Retirement Pension System
1. Understanding the Basics of the Retirement Pension System
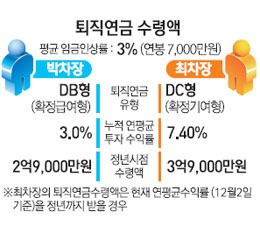
The retirement pension system is a valuable framework designed to ensure that employees can safely receive their severance pay upon retirement by entrusting it to external financial institutions. In the past, it often happened that employees could not receive their severance pay if their company went bankrupt, but now a robust legal safety net has been established. There is the Defined Benefit (DB) method, where the company manages the investments, and the Defined Contribution (DC) method, where employees must select investment products themselves to generate returns. For office workers, accurately understanding how their company operates the system is the first step in wealth management. If you pay close attention to the mandatory annual education sessions conducted by your company, you can easily understand these systemic differences. Many people make the regrettable mistake of opening a DC account and then leaving it untouched for years, even forgetting their password. If you log in to your account via a bank or securities app, you will likely start to notice a surprising variety of products. You can choose from a wide range of options, from safe principal-and-interest guaranteed products to equity funds and Exchange-Traded Funds (ETFs), according to your risk profile. In addition to the contributions made by your company each month, you can also make additional contributions to maximize tax benefits. You need the initiative to turn on your smartphone right now and check where your retirement pension account is opened in your name.
💡 Key Point You must accurately identify the type of pension system and take direct interest in any neglected accounts to begin growing your assets.
2. Strategies for Leveraging Latest Financial Services
2. Strategies for Leveraging Latest Financial Services
The same-day trading service for retirement pension ETFs, recently introduced by major financial institutions including Shinhan Bank, has completely changed the landscape of investment for office workers. In the past, if you sold a held product, you had to wait several days for the cash to appear in your account, making it difficult to respond to rapidly changing market conditions. However, now you can immediately use the proceeds from a sale to buy another product on the same day, significantly increasing capital turnover. For example, if you want to sell an ETF investing in U.S. semiconductor stocks and switch to another promising asset, you no longer need to wait anxiously for several days. By actively utilizing this convenient method, you can respond nimbly to market trends and maximize your returns. Another major advantage is that you can complete all transactions with a few touches on a mobile app without having to visit a securities firm or bank branch during busy work hours. For modern people who are extremely busy with their jobs, time is money, so these non-face-to-face convenience features are essential. Carefully checking fee structures and trading hours in advance can prevent unnecessary losses in actual investing. Rather than blindly following hearsay that a friend made a big profit on a specific stock, you should calmly consider whether it matches your investment style. You need the wisdom to make these newly introduced convenient systems work for you to grow your assets smartly.
💡 Key Point Utilizing the latest financial features, such as same-day trading services, allows you to respond nimbly to market changes and improve investment efficiency.
3. Maximizing Tax Deductions and Tax-Saving Benefits
3. Maximizing Tax Deductions and Tax-Saving Benefits
The most compelling reason to actively utilize your retirement pension account is the substantial tax-saving benefits and tax deduction effects. As the year-end tax settlement period approaches, the biggest concern for office workers is how to get a tax refund. Additional contributions to an Individual Retirement Pension (IRP) account are eligible for tax deductions at a certain rate, making it an essential course in wealth management for employees. If you fill up the annual contribution limit of 9 million won, you can enjoy the pleasure of receiving a decent refund in your bank account every spring. As the saying goes, saving on taxes is the most certain form of return, so tax savings through pension accounts are not optional but mandatory. Failing to properly utilize this good system provided by the state and investing only in general accounts is akin to deliberately incurring a huge loss. When you receive money in the form of a pension after retirement, a much lower tax rate is applied compared to general income tax, significantly reducing your tax burden. By saving a little each month while working and simultaneously saving on taxes, you achieve a two-for-one benefit. Using the Integrated Pension Portal service operated by the Financial Services Commission, you can easily check your scattered pension information at a glance, which is helpful for planning your finances. If you make a long-term plan to carefully fill up the tax deduction limit every year, you can completely free yourself from the anxiety of retirement bankruptcy.
💡 Key Point Tax deductions through pension accounts and the application of low pension income tax rates are the most reliable tax-saving strategies for growing retirement funds.
4. Finding the Balance Between Safety and Returns
The most important principle in managing retirement pensions is finding an appropriate balance between safety and returns, rather than unconditionally pursuing high yields. If you put a significant portion of your total funds into principal-and-interest guaranteed products, you may not worry about losing your principal, but considering inflation, you are effectively taking a loss. Conversely, if you put all your funds into highly volatile equity ETFs, you may experience extreme stress when the market crashes. The answer is to accurately assess the level of risk you can tolerate and diversify your investments by allocating assets appropriately. While referring to asset allocation ratios recommended by experts, you must periodically review your portfolio to match your retirement timeline and risk profile. Including high-quality products that ride the massive trend of the AI industry, such as Samsung Asset Management’s U.S. semiconductor-related products, in a portion of your portfolio is also a good method. Since you can invest long-term in these global high-quality products in pension accounts as well as general accounts, it is worth actively utilizing them. If you set up automatic purchases of high-quality products on a fixed date each month, you do not need to worry about market timing. It is forbidden to take the risk of betting all your hard-earned pension funds on one or two stocks; you must always prepare a shield that can withstand market waves. You must strengthen the resilience of your account through periodic rebalancing work that appropriately adjusts the ratio of safe and risky assets.
💡 Key Point You must build a portfolio that secures both safety and returns by appropriately diversifying between principal-and-interest guaranteed products and growth assets.
5. Collateral Loans and Handling Exceptional Situations
In life, there are moments when you suddenly need a large sum of money or urgent cash, and in such cases, arbitrarily terminating your retirement pension is the worst choice. If you terminate it midway, you not only have to return all the tax benefits you received but also lose your future retirement funds entirely. Fortunately, utilizing the retirement pension collateral loan system opens a path to safely borrow necessary funds without breaking your accumulated savings. By pledging the accumulated funds in your name as collateral, you can borrow money from financial institutions at relatively low interest rates, allowing you to overcome the crisis while maintaining your pension. This can be usefully applied in cases of special reasons specified by law, such as an increase in the deposit for a lease or long-term medical expenses for yourself or family members. Since the loan limits and conditions vary depending on the type of product and the financial institution, it is essential to carefully examine them in advance. If you fail to repay the principal and interest later, it may damage your pension assets, so you must apply only after meticulously planning your repayment. The collateral loan is an excellent institutional alternative that allows you to extinguish the immediate fire without letting go of the thread of your hard-earned retirement assets. If you have a friend who wants to terminate their pension just because they need money, you must absolutely dissuade them and guide them to this loan system. The wisdom to endure without breaking your pension account even in a crisis ultimately becomes the fork in the road that determines a prosperous life after retirement.
💡 Key Point When urgent cash is needed, you should utilize retirement pension collateral loans instead of terminating the pension to protect both tax benefits and retirement assets.
6. Integrated Inquiry and Long-Term Investment Outlook
By utilizing the Financial Services Commission’s Integrated Pension Portal service, you can grasp all your retirement assets, from the National Pension to retirement pensions and individual pensions, at a glance. Getting the big picture of how much you have saved so far and how much you can receive monthly after retirement is the core of successful retirement preparation. Since you can easily and free of charge check account information scattered across multiple financial institutions, you should develop the habit of logging in regularly to review your asset status. Only those who look ahead to the future ten or twenty years from now and consistently increase their accumulated funds can enjoy a comfortable life after retirement. It is most important to maintain the attitude of sticking to the principle of long-term investment without being disappointed or giving up just because the return rate has dropped slightly in the short term. The government and financial institutions are also continuously introducing more convenient trading systems and diverse investment products to ensure a stable retirement for citizens. Office workers themselves must not stop their efforts to actively protect and grow their assets while keeping an eye on changing financial trends. Starting today, try beginning with the small action of logging into your retirement pension account app and carefully checking which products your money is in. I am confident that if consistent interest and correct investment strategies are combined, your retirement will become a smooth and worry-free path. For a wonderful life after retirement, I hope you will treat your retirement pension account as your most valuable asset management partner from this very moment.
💡 Key Point Periodic asset checks through the Integrated Pension Portal and a long-term investment mindset complete a prosperous and stable retirement.
Frequently Asked Questions
What are the disadvantages of terminating a retirement pension midway?
You must return all the tax deduction benefits you have received, and other income tax will be imposed, significantly reducing the amount of money you actually receive. Additionally, your valuable retirement assets will disappear, potentially causing significant difficulties after retirement.
Is it safe to invest in equity products in a Defined Contribution (DC) account?
While there is a risk of principal loss compared to principal-and-interest guaranteed products, appropriate allocation of equity assets is essential to beat inflation and achieve high returns in the long term. It is important to adjust the proportion according to your investment style.
Can anyone easily get a retirement pension collateral loan?
You can borrow within a certain limit of your accumulated funds when there are special reasons specified by law, such as housing structure or lease deposits, or medical expenses, and when you meet the allowable conditions of each financial institution.
What information can I check on the Integrated Pension Portal?
You can free of charge and at a glance check the enrollment details, accumulated amounts, and expected pension receipt amounts for all individual pensions you are enrolled in, as well as the National Pension and retirement pensions.