The IRP (Individual Retirement Pension) account is an essential financial product for any employee preparing for retirement, yet many people feel overwhelmed by the complexity of the system. If you want to save on taxes starting next year, you must accurately understand the annual contribution limits and tax deduction benefits to utilize them according to your specific situation and avoid losses. In fact, Kim, a junior staff member, used to face a “tax bomb” every year during the year-end tax settlement season. It was only after opening this account late in the game that he started receiving refunds of several hundred thousand won annually, slapping his knee in realization. It is also a very wise strategy to transfer your severance pay to the account to enjoy the tax deferral benefit, rather than receiving it as a lump sum and paying a large amount of tax immediately. Recently, financial institutions have improved their services to allow customers to directly select from a variety of investment products, broadening the path to higher returns. In this article, we will carefully go through everything, from maximizing tax deductions to recent regulatory changes, in a way that is easy for anyone to understand.
=
A Complete Guide to IRP Account Tax Deduction Limits and Severance Pay Strategies
1. What is an IRP Account and Why You Must Join

The IRP account, known as the Individual Retirement Pension, is a special account where subscribers directly deposit money to grow their retirement funds and can withdraw them as a pension after retirement. You can keep your severance pay from your job in this account as is, or you can voluntarily make additional contributions to enjoy tax benefits. In the past, many people delayed opening an account because visiting a bank or securities firm was a hassle, but nowadays, you can easily open one non-face-to-face through a mobile app in just a few minutes.
The reason people around you actively recommend this account is that it effectively alleviates the burden of year-end tax settlement, which is a major concern for employees. Simply saving a certain amount from your hard-earned monthly income results in a tax refund from the government, making it a loss if you don’t participate. Since the scale of your future assets depends entirely on when you start preparing for retirement, it is wise to begin preparing early, even if you are just starting your career.
The IRP account is an essential retirement preparation account for employees that allows you to manage severance pay and secure tax deductions simultaneously.
2. Annual Tax Deduction Limits and a Wise Combination with Pension Savings

When combined, Pension Savings and IRP accounts allow for a maximum annual tax-deductible contribution of 9 million won, resulting in a significant tax-saving effect. While Pension Savings alone allows for contributions up to 6 million won, adding an IRP account allows you to fill the remaining amount to fully utilize the 9 million won limit. Employees with an annual income of 55 million won or less can apply a high deduction rate of up to 16.5%, allowing them to receive a substantial refund of up to 1.485 million won.
Even if your annual income is higher than that, you can still apply a 13.2% deduction rate and receive a considerable tax refund, making it an excellent tax-saving tool for high-income earners as well. Employees who used to stress over the taxes they had to pay every year during the tax settlement season now enjoy the pleasure of getting money back after utilizing this account. If filling the limit feels burdensome, we recommend setting up automatic monthly transfers of a fixed amount that fits your monthly disposable income to steadily build up your savings.
By combining Pension Savings and IRP accounts to contribute up to 9 million won annually, you can receive a remarkable tax deduction of up to 16.5%.
3. The Huge Difference Between Lump-Sum Severance Pay and Tax Deferral

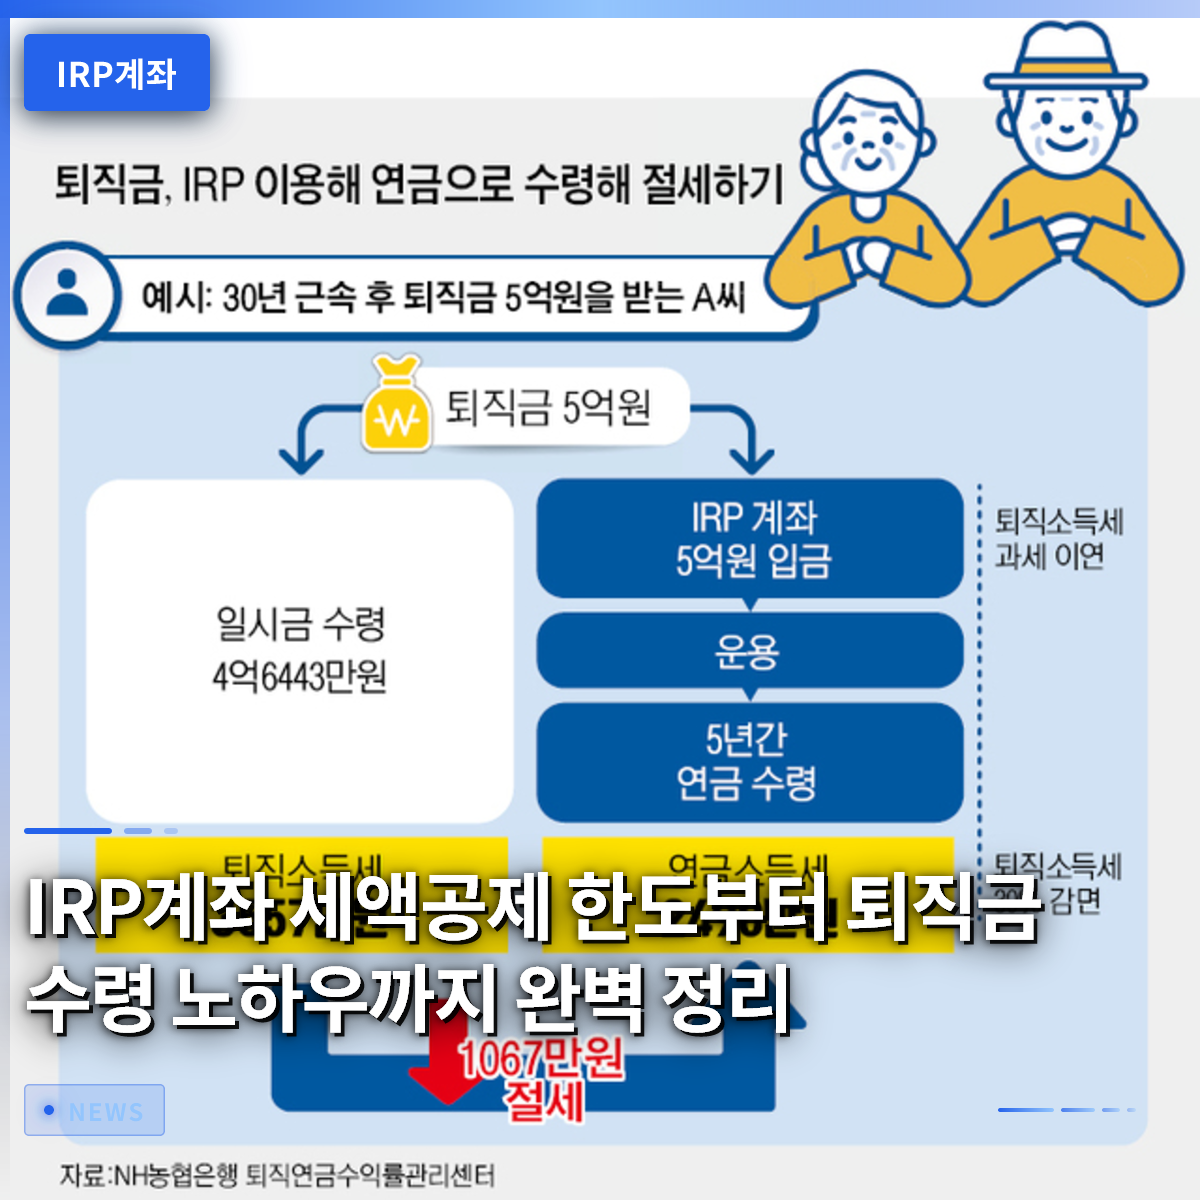
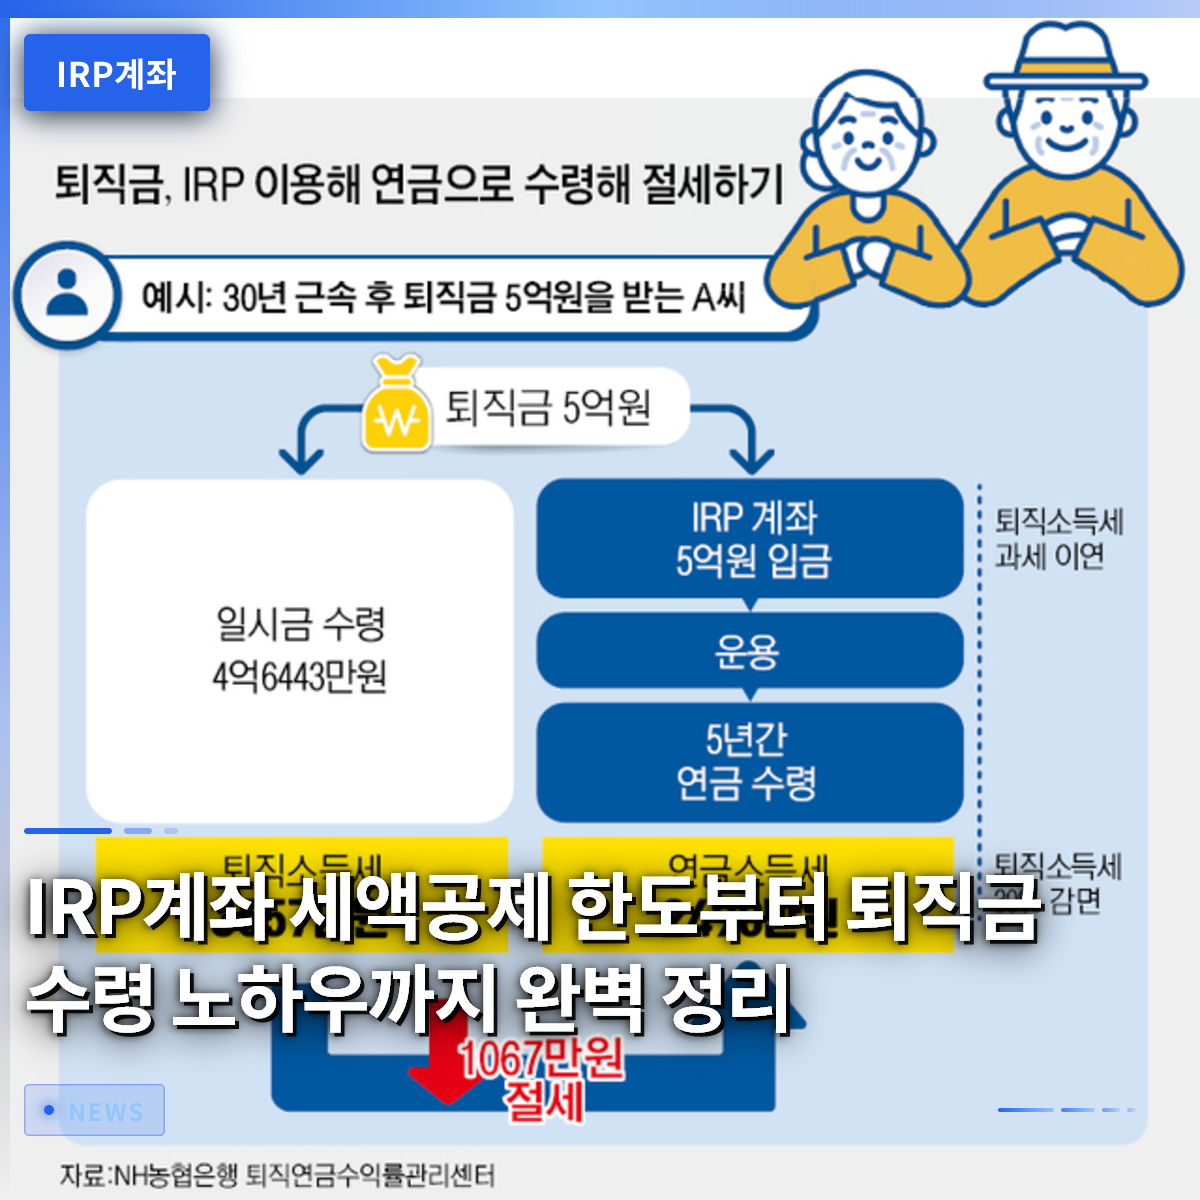
If you receive your severance pay as a lump sum in cash when you leave your company, you will immediately face a high severance income tax rate that you may not have expected. If you transfer this valuable severance pay directly to your IRP account instead of using it as is, a “magic” of tax deferral occurs, where the tax is not deducted immediately but postponed. Since the tax is not reduced but merely deferred until the point when you receive it as a pension, you can fully enjoy the compound interest effect as your principal and interest grow in the meantime.
Moreover, if you receive it in the form of a monthly pension after retirement, a much lower pension income tax rate is applied compared to the original severance income tax rate, drastically reducing the tax burden. In fact, Manager Park, who was approaching mandatory retirement age, almost paid a large amount of tax by receiving his severance pay as a lump sum. However, following advice from those around him, he transferred it to an account, saved on taxes, and is now receiving a steady monthly pension like a reliable salary. To maintain a stable life after retirement, you must not carelessly spend your severance pay in cash but must safely transfer it to a pension account.
Transferring severance pay to an IRP account allows you to save on taxes through tax deferral and enjoy a lower tax rate when receiving it as a pension.
4. Utilizing Diverse Investment Products and the Recent Same-Day Trading System
Unlike the past when money was buried only in deposits, you can now directly invest in domestic and international equity index funds or various bonds within the account to pursue higher returns. In particular, with the recently introduced same-day trading service, you can sell an index fund held in the account and immediately reinvest it in another product on the same day without waiting for the settlement date. This allows investors to respond quickly to rapidly changing financial market conditions, enabling them to seize opportunities and flexibly adjust their portfolios without missing out.
Additionally, the range of choices has broadened further as investors who prefer safe assets can now directly purchase stable products like government bonds. Holding low-cost, high-growth semiconductor-related products or high-quality bond index funds long-term can grow your retirement assets much more efficiently. However, equity assets can only make up 70% of the total accumulated funds, and the remaining 30% must be filled with safe assets, so you need to pay attention to ratio management.
The introduction of the same-day trading service has improved investment convenience, allowing you to actively grow your assets by utilizing various index funds and bonds.
5. Fearsome Penalties and Precautions for Early Termination
Since the IRP account is primarily for long-term retirement funds, terminating it midway should be absolutely avoided unless there are special reasons. If you arbitrarily terminate the account because you urgently need money, you will not only have to return all the tax deduction benefits you received but also bear additional miscellaneous income tax. It is easy to see people around you who regretted terminating their accounts to buy a house or secure a deposit for a rental, only to face a “tax bomb” of several million won.
Withdrawal at a lower tax rate is only possible in cases of unavoidable exceptions specified by law, such as home purchase by non-homeowners, bankruptcy, natural disasters, or medical treatment for more than 3 months. Therefore, when you need a large sum of money, you should carefully check if there is a system that allows partial withdrawal rather than terminating the entire account and make a prudent decision. To fully enjoy the tax benefits during the long race of retirement preparation, patience to maintain the account until the end and a thorough financial plan are essential.
Early termination requires returning all tax deduction amounts, so it is important to maintain the account until the end unless there are unavoidable reasons.
6. Practical Strategies for Successful Retirement Preparation
Based on the content reviewed so far, the wisest first step is to check your asset situation and start setting up automatic transfers starting this month. Even if you feel your monthly surplus is insufficient, if you start small and gradually increase your contribution amount, you will face significantly grown assets in a few years. As your retirement date approaches, you need strategic thinking to gradually increase the proportion of safe assets in your portfolio to safely protect your principal.
Financial systems will continue to change in a direction favorable to investors, so it is important to maintain a posture of consistently paying attention to related news. Retirement is not something to wait for amid vague anxiety, but something that only those who prepare meticulously and smartly in this very moment can welcome with ease. We hope you will actively utilize the tax-saving benefits and investment know-how learned today to beautifully complete a prosperous and stable life after retirement.
You should start automatic transfers and tax-saving contributions immediately, even with small amounts, to build a solid long-term retirement asset base.
Frequently Asked Questions
=