Hyundai Motor Securities recently issued a report projecting that LX Hausys will continue its earnings recovery, driven by the expansion of its B2C business and increased revenue in non-construction materials such as automotive materials and industrial films. The firm maintained its target price of 50,000 won and a “Buy” recommendation. With significant upside potential assessed based on the previous day’s closing price, the stock is drawing considerable attention from investors. The prevailing analysis suggests that the company’s successful diversification away from a structure that relied solely on the construction cycle has been a key factor. In fact, it is easy to observe an increasing number of consumers visiting stores directly for consultations when renovating their apartment interiors. Let’s take a closer look at how these changes are impacting the company’s earnings defense. From here, we will examine LX Hausys’s future growth drivers and securities industry forecasts one by one.
=
LX Hausys B2C and Automotive Materials Business in Focus, Target Price of 50,000 Won Forecast
1. Increased Housing Transactions and Recovery in Construction Materials Performance
Despite the challenging environment of strengthened housing regulations in the second quarter of this year, housing transaction volumes increased compared to the same period last year, leading to a significant surge in construction materials sales. Additionally, the temporary reflection of tariff refund effects in the US market resulted in a sharp rise in operating profit. In reality, even with a cooling wind blowing through the real estate market, steady demand for new wallpaper and flooring during moving season served as a foundation for improved performance. The company successfully maximized sales of key products by quickly responding to these subtle market rebounds. Conducting field-centric sales without going through complex distribution structures also greatly contributed to improved profitability. Thus, the construction materials segment continues to play a crucial role as the most solid backbone supporting the company’s total revenue.
The combination of increased housing transactions and temporary refund effects significantly improved construction materials sales and operating profit.
2. Robust Earnings Defense in the Non-Construction Materials Sector
Outlooks for the second-half housing market remain conservative, making it difficult to be overly optimistic. This is because rising benchmark interest rates and higher mortgage rates have caused consumers to tighten their belts, increasing the likelihood of a decline in housing transaction volumes. Furthermore, geopolitical instability has driven up raw material prices and ocean freight costs, placing a heavy burden on total costs. However, even amidst these headwinds, the non-construction materials sector, including automotive materials and industrial films, is serving as a sturdy shield by securing stable overseas revenue. The uninterrupted supply of components to overseas automakers is sufficiently offsetting the sluggishness in the domestic market. Thanks to this portfolio diversification strategy, the company has built a robust structure that remains unshaken by external shocks.
The non-construction materials sector is successfully defending against external headwinds and domestic housing market sluggishness based on stable overseas revenue.
3. B2C Business Expansion Driving Structural Improvement
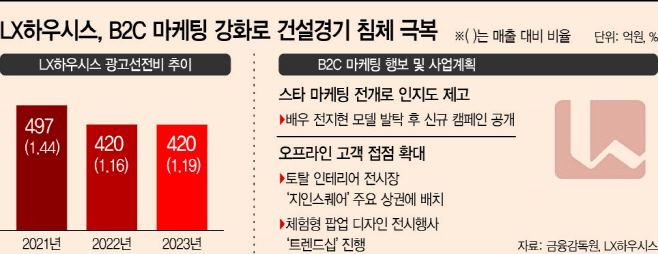
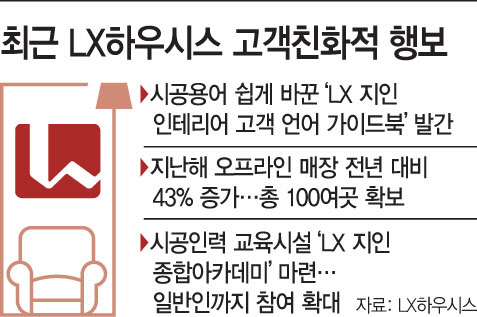
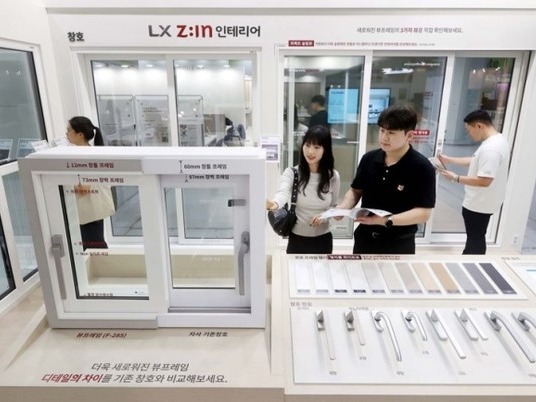
While the proportion of bulk deliveries to apartment construction sites was overwhelmingly high in the past, the company is now aggressively expanding its sales network to individual consumers. As a system has taken shape where individual consumers visit stores directly to select interior materials and entrust installation, the risk associated with construction cycle fluctuations has significantly decreased. For example, it is common to see acquaintances moving into new homes visiting large showrooms to inspect windows and flooring in person before signing contracts. This shift toward a B2C-centric distribution structure acts as a key to maximizing profitability by reducing middle margins. By consistently introducing high-value-added products tailored to discerning consumer standards, the brand value is also naturally rising. This management strategy, which reduces dependence on the construction industry, is solidifying the company’s long-term growth potential.
By expanding the B2C share and strengthening distribution competitiveness, the company is successfully overcoming structural vulnerabilities to construction cycle fluctuations.
4. Revised Earnings Forecasts and Financial Soundness
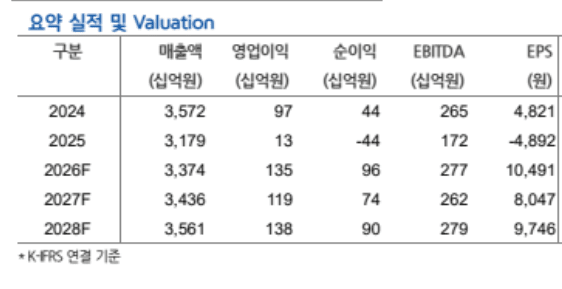
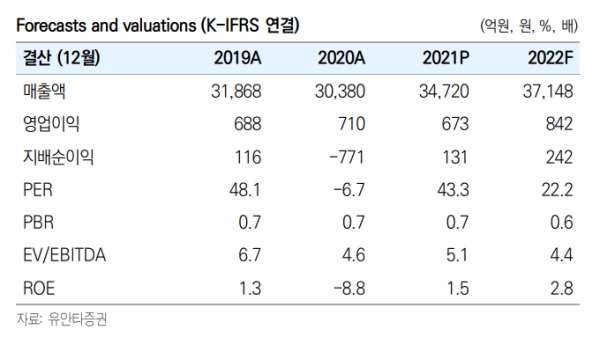
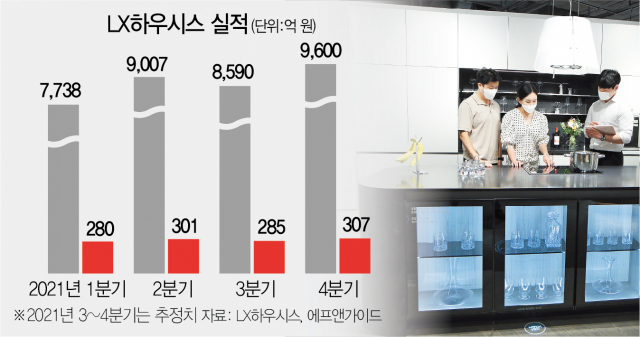
Reflecting the results of this business diversification, Hyundai Motor Securities has raised its full-year earnings forecast higher than previously projected. The company expects this year’s revenue to reach the trillions of won range, with operating profit expected to exceed market expectations. The net income forecast has also been significantly revised upward, demonstrating that the company’s overall financial soundness has become more robust. Companies that see their earnings estimates revised upward, even in an uncertain economic environment, tend to receive positive evaluations from the market. The speed of operating margin improvement is also faster than initially anticipated, driven by detailed cost-cutting efforts and production process efficiency improvements. These improvements in financial metrics are expected to serve as the strongest basis supporting future stock price appreciation.
Based on solid earnings trends, forecasts for revenue, operating profit, and net income have all been revised upward, sending positive signals.
5. Expectations for Dividend Resumption and Investment Appeal
The most welcome news for shareholders who have long waited for stock price appreciation is the possibility of resuming dividends in line with the return to profitability. The shareholder return policy, which had left shareholders disappointed due to poor performance, is expected to regain momentum alongside the gradual recovery of the industry. Because the company is showing a slow but certain trend of improving earnings, interest from investors approaching from a long-term perspective remains undiminished. Calculating the upside potential from the current stock price to the target price makes it easy to see that the investment appeal is quite high. Internally, the company is also exploring various methods to enhance shareholder value, with an atmosphere of strengthened communication. This shareholder-friendly approach acts as an important factor providing solid trust to long-term investors.
The possibility of resuming dividends due to the return to profitability, combined with high upside potential, is further highlighting the investment appeal.
6. Future Outlook and Formulating a Successful Investment Strategy
In conclusion, this securities report clearly shows that LX Hausys is evolving into a comprehensive living space company, going beyond being a simple construction materials firm. Although there are obstacles such as second-half interest rate hikes and rising raw material prices, the company has secured overseas export momentum and B2C competitiveness capable of overcoming them. Therefore, rather than reacting emotionally to short-term price fluctuations, it is wise to focus on the company’s fundamental structural improvements. Visiting interior stores personally to observe consumer reactions or consistently tracking trends in related industries are also good approaches. It is time to calmly watch what kind of stock price trajectory a company that has steadily built its internal strength will show. By establishing one’s own investment principles based on thorough analysis and approaching the market, one can achieve good results.
Despite domestic and international variables, it is necessary to review the long-term growth potential and investment strategy of LX Hausys, which has completed its structural improvement.
Frequently Asked Questions
=