Office workers struggling with multiple debts and the burden of high interest rates can significantly reduce their monthly principal and interest payments by switching to low-interest products through refinancing. It is common to hear people around you say they are suffocating under the high rates of capital companies or savings banks. In such cases, wisely utilizing the refinancing system can greatly restore financial health. I myself had the experience of finally escaping the financial pressure I had been struggling with monthly by consolidating debts scattered across various institutions into one. It is regrettable that many people do not even attempt it out of fear that the process is complicated or that their application will be rejected. In this article, based on actual experiences and changes in the financial environment, I will thoroughly examine debt management techniques that anyone can follow. If you carefully read the content introduced below, you will find the key to wisely resolving the interest bombs that have been weighing heavily on your wallet.
=
High-Interest Refinancing Review and Tips for Office Workers to Successfully Manage Multiple Debts
1. The Reality of Multiple Debts for Office Workers and the Quagmire of High Interest
There are many office workers around us who fall into the quagmire of multiple debts as small loans from various financial companies snowball. Initially, they may casually use cash services or card loans due to a lack of living expenses, but over time, the interest grows to an unmanageable level. For example, Mr. Kim, a colleague of mine, had his loans split into five separate debts from private lenders and the second financial sector, resulting in the tragic situation where his bank account was emptied as soon as his salary was deposited. When multiple debts are intertwined, not only does your credit score drop sharply, but interest calculations become complex, making normal saving or living impossible. The attitude of looking up at the high threshold of banks and accepting high interest as a matter of course must be corrected quickly to break the vicious cycle. If the state of multiple debts is left unattended, it will ultimately lead to disaster, so it is a priority to accurately assess the total scale of your debt before it is too late. You must coldly calculate your debt-to-income ratio and rank which interest rate products are the most harmful. If you leave indiscriminately increased debts as they are, even the opportunity for credit recovery will recede, so special caution and quick decision-making are required.
Multiple debts and high interest rates are the main culprits behind the collapse of office workers’ finances, so accurate debt assessment and quick decision-making are essential.
2. The Concept of Refinancing and Eligibility Conditions
Refinancing refers to a financial system where existing high-interest funds are switched to lower-interest products or multiple debts are consolidated into one. Recently, the financial sector has significantly expanded customized switching products for general office workers, in addition to self-employed individuals and freelancers, broadening the range of choices. For example, an office worker with debts from savings banks or capital companies exceeding 15% per annum can lower the interest rate to single digits by using integrated products from banks or the formal financial sector. However, to utilize this, a minimum period of employment and proof of stable income are essential, and it is advantageous to have no record of delinquency. If your credit score is too low or you have a history of serious debt default, accessing general banks may be difficult, so you should check your own status. By using financial company mobile apps or online intermediary platforms, you can easily check refinancing products suitable for your conditions without visiting branches one by one. Rather than applying blindly, you need the wisdom to objectively analyze your current income and credit status and find the financial institution offering the most favorable terms.
Refinancing, which switches high interest rates to low ones, yields the greatest effect when backed by stable income and credit status.
3. Actual Office Worker Refinancing Success Review and Procedure

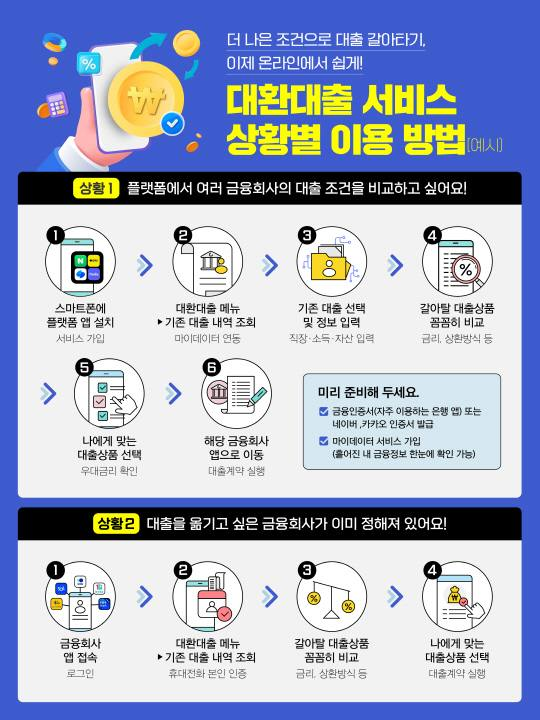
Mr. Park, an office worker enrolled in the four major social insurances, suffered from suffocating pain as his loan amount reached the limit relative to his annual salary, and he decided to boldly apply for refinancing. First, he organized the details of card loans and savings bank credit loans scattered across various places into an Excel file to easily grasp the total scale of his debt at a glance. Then, using a financial comparison app installed on his smartphone, he checked the expected interest rates and limits for integrated refinancing products he could receive with just a few touches. Surprisingly, he was able to significantly lower the interest rate from over 16% to the 9% range for the money he had borrowed at high interest rates through a capital company’s customized integrated product for office workers. In this process, he also secured additional small funds to put out the fire and succeeded in reducing the monthly interest costs by nearly half. The application procedure was not as difficult as expected, and by submitting essential documents such as a certificate of employment and income statement as electronic documents, he greatly shortened the review time. As soon as approval was granted, the financial institution directly sent money to the existing high-interest creditors to cleanly repay the debts, leaving him to manage only a new single account.
By thoroughly organizing scattered debts with documents and utilizing mobile comparison apps, you can lower interest rates and secure additional limits.
4. Customized Refinancing Strategies for Business Owners and Freelancers
An era has opened where not only office workers but also individual business owners and freelancers can enjoy significant benefits through recently strengthened refinancing intermediary products. When running a business, it is easy to resort to loans from the second financial sector or card companies due to temporary cash flow shortages, and the interest burden is no joke. As major banks and fintech companies joined hands to launch dedicated switching services for individual business owners, some have even emerged offering minimum interest rates in the 3% range. In fact, one self-employed individual saved over several hundred thousand won per month in fixed interest costs by switching a high-interest business loan to a refinancing product from the first financial sector. For business loans, limit and interest rate conditions vary greatly depending on years in business and sales volume, so you should transparently document sales evidence, such as VAT filings, in advance. Actively utilizing grace period systems that allow for a more relaxed repayment period, rather than simply lowering the interest rate, can greatly help stabilize cash flow in the early stages of a business. If small business owners who were in a blind spot make good use of the customized support systems from the government and the financial industry, they can firmly establish a stepping stone for a comeback.
Individual business owners and freelancers can also enjoy exceptional interest rate reduction benefits through transparent sales evidence and dedicated intermediary services.
5. Points to Be Careful About When Applying for Refinancing
Even if the refinancing terms are good, diving in blindly can lead to negative impacts on your credit score or the embarrassment of rejection. The first thing to guard against is leaving inquiries or pre-inquiries with multiple financial companies simultaneously, as this is a major cause of credit score drops. Also, you must carefully calculate how much prepayment penalty will be incurred; if the fee for early repayment of an existing loan is greater than the interest savings, it is actually a loss. Occasionally, fraudulent companies demand upfront payments or collect illegal fees under the guise of low-interest refinancing, so you must verify if they are a formal company registered with the Financial Supervisory Service. If your credit score is excessively low or you have a history of delinquency, there is a high risk of falling into the quagmire of high-interest private lending if you force a loan. It is most important to coldly evaluate your repayment ability and make a realistic plan to diligently repay the principal and interest on the scheduled date each month. Rather than impulsively increasing debt driven by emotion, caution is needed to go through expert counseling or prioritize looking into government support systems.
A cautious approach considering prepayment penalties, illegal companies, and your own repayment ability is the shortcut to preventing failure.
6. Future Outlook and Actions for Successful Debt Management
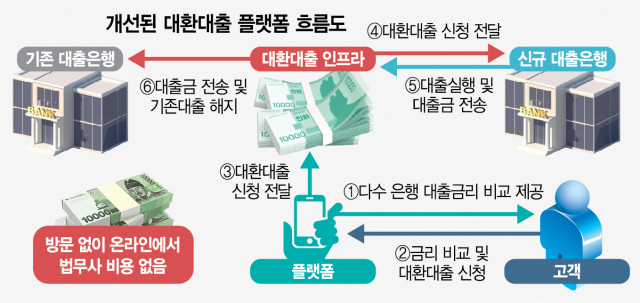
The future financial market is expected to see personal customized refinancing and asset management processes become much faster and more transparent due to the development of artificial intelligence technology and fintech platforms. You can compare all interest rates nationwide and switch in real time with just a smartphone screen, without having to visit bank counters with complex documents. In the midst of this wave of change, if financial consumers pay a little attention and put in the effort, they can easily escape the high-interest burden threatening their household economy. No longer sighing while paying high interest, please check your debt status immediately today and start by comparing interest rates on a mobile app. A little courage and wise information seeking will lighten your heavy shoulders and serve as a solid stepping stone for building strong assets. I sincerely encourage you to take action now to stop unnecessary interest leakage and move powerfully toward a new financial leap.
An attitude of actively comparing interest rates and taking action in line with the development of fintech technology is the key to resolving household debt.
Frequently Asked Questions
=