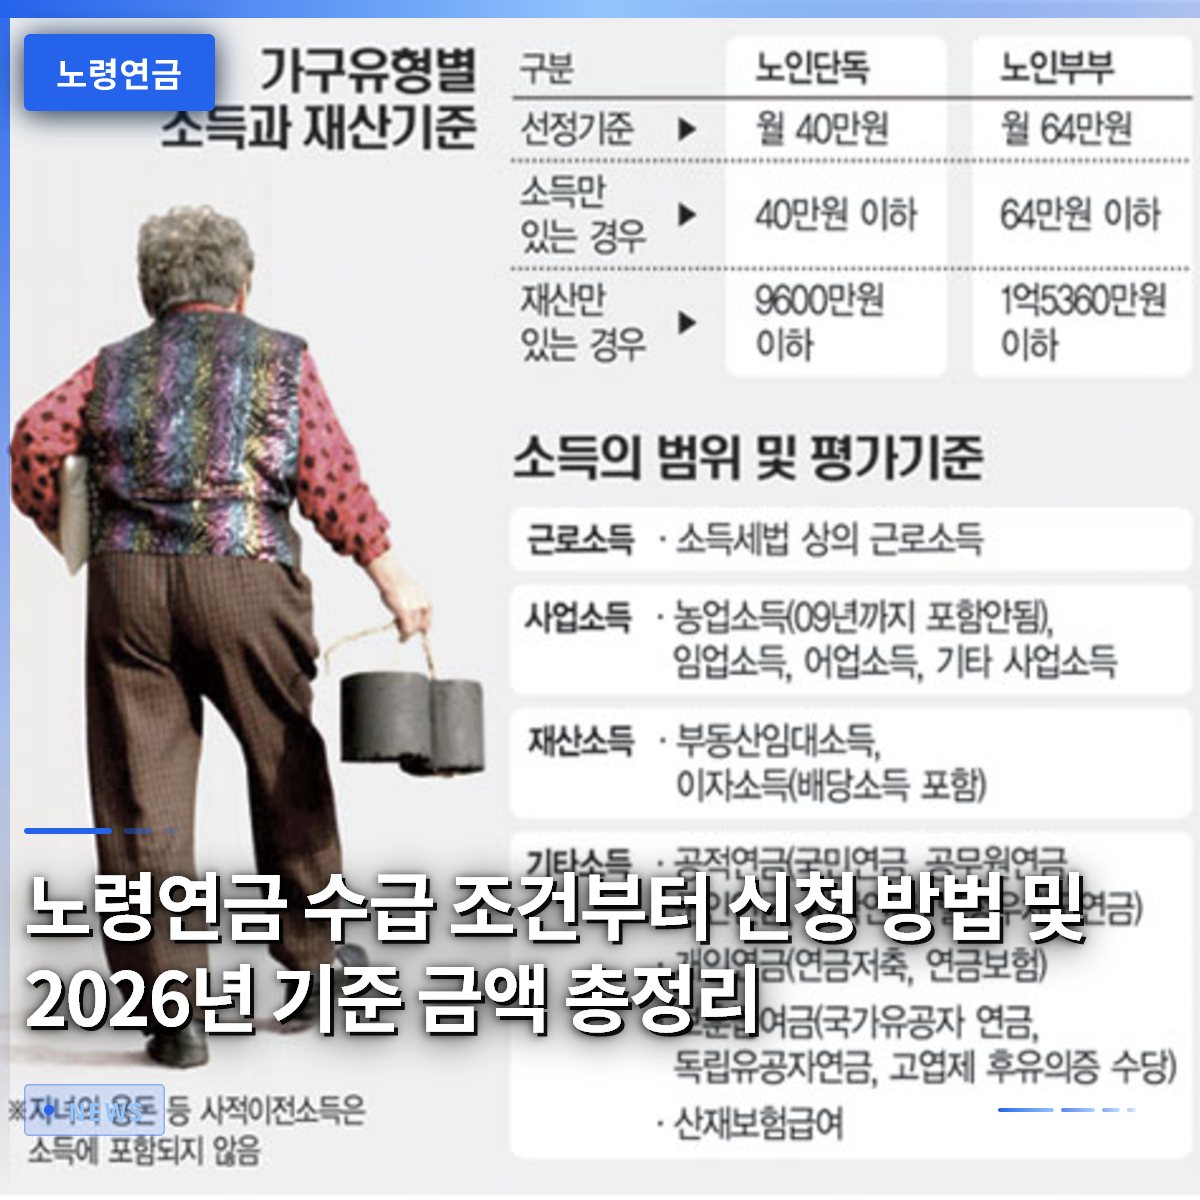
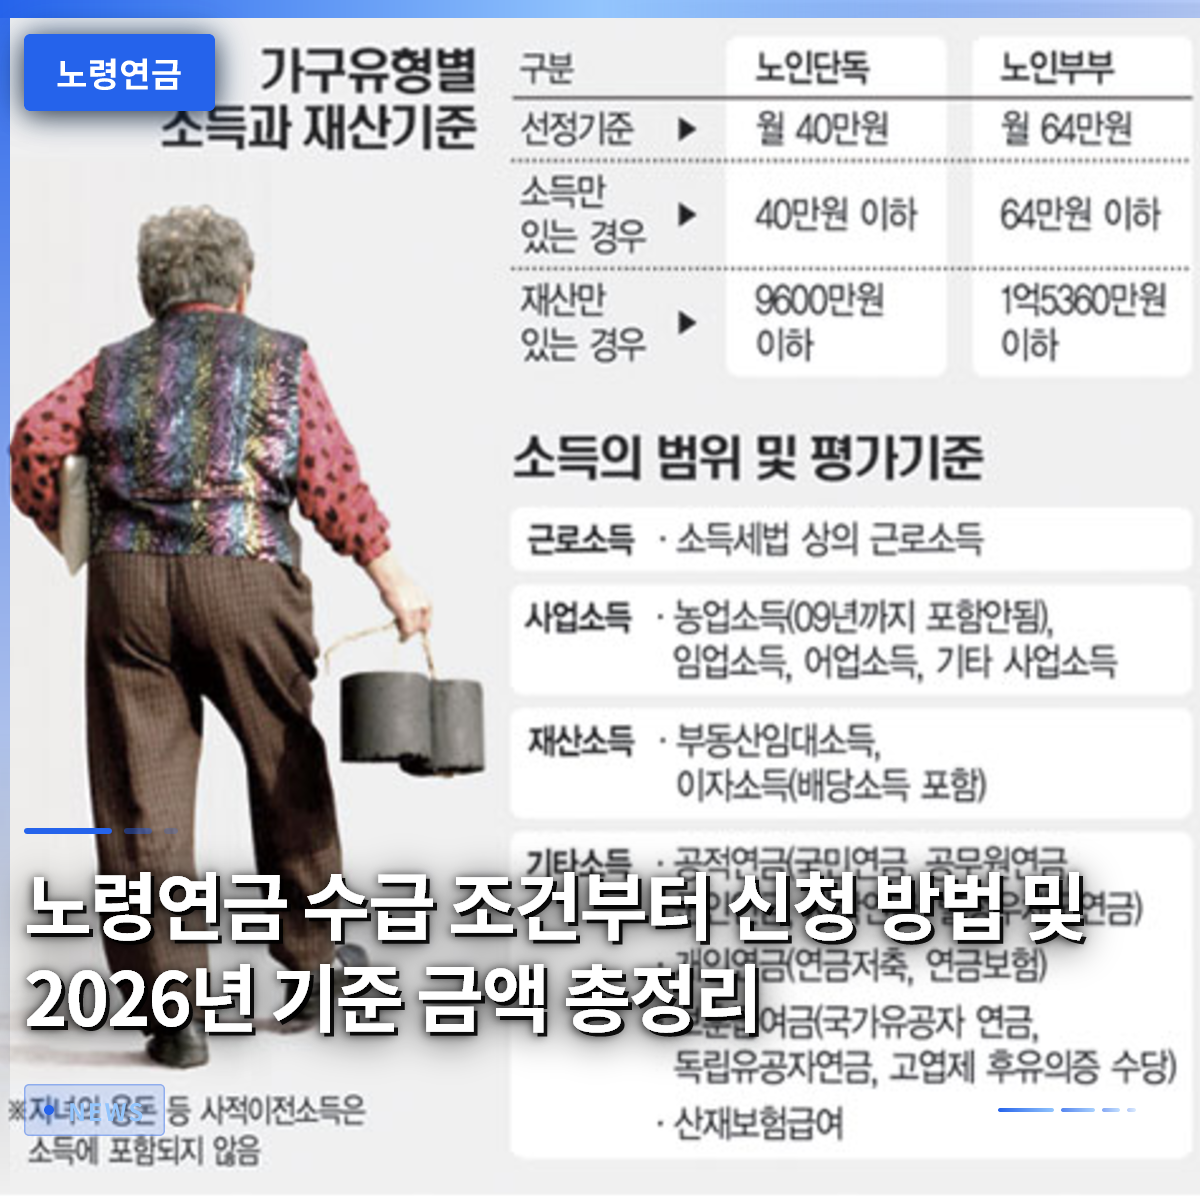
To receive the old-age pension stably, you must meet the minimum enrollment period of 10 years. Additionally, as of 2026, your average monthly income from employment and business must not exceed a certain threshold to receive the full benefit amount without reduction. It is common to see acquaintances approaching retirement worry about the pension amount deposited into their accounts each month and ponder how they can maximize their benefits. When retirement actually arrives, the complex regulations can be confusing, so understanding the core aspects of the system in advance is essential to avoid unnecessary financial losses. In this article, we will carefully examine the eligibility conditions for the old-age pension, reduction criteria, and its relationship with the basic pension. Properly understanding these details will greatly help in securing a reliable source of income for your retirement. Let’s go through this step by step to check which conditions apply to you.
=
A Complete Guide to Old-Age Pension Eligibility, Application Methods, and 2026 Benefit Amounts
1. Old-Age Pension Eligibility and Minimum Enrollment Period

To qualify for the old-age pension, you must have paid National Pension premiums for at least 120 months, or 10 years. For those who diligently paid premiums while working in the past but stopped due to unemployment or business failure, this 10-year barrier may feel insurmountable. However, actively utilizing government programs that subsidize part of the premiums during unemployment can significantly help in meeting the enrollment requirement. For example, applying for the Unemployment Credit system while receiving unemployment benefits allows you to count that period toward your enrollment. It is not uncommon to see seniors who barely met the 10-year requirement be surprised by the actual pension amount, which is often lower than expected. Since a longer enrollment period results in a higher monthly pension, it is advantageous to pay for a longer duration through voluntary continued enrollment if you have the means. If your enrollment period is slightly under 10 years as retirement approaches, you may consider making a lump-sum payment to meet the eligibility criteria. It is important to regularly check your enrollment records to know exactly how much time is missing.
The basic condition for receiving the old-age pension is a minimum enrollment period of 10 years, and any shortfall can be made up through various support programs.
2. 2026 Old-Age Pension Reduction Criteria and Income Activity

As of 2026, if you receive the general old-age pension while engaging in income-generating activities, part of your pension may be reduced if your average monthly income exceeds a certain threshold. Specifically, if your average monthly income amount, reflecting employment and business income, is 5,193,511 KRW or more, you may be subject to reduction. The “income amount” here does not simply refer to the pre-tax salary deposited into your account; it is calculated after deducting various income deductions. It often happens that seniors who run small shops or work part-time to make ends meet after retirement are caught off guard because they are unaware of this reduction criterion. Many people feel it is unfair and are disappointed to learn that their pension is reduced despite working hard to earn more. However, this system aims to adjust the pension benefits of relatively high-income recipients to ensure fiscal stability and concentrate benefits on those who truly need them. Therefore, if your expected monthly income is close to the reduction threshold, it is wise to contact the National Pension Service in advance for an accurate simulation. Be careful to report any changes in income immediately; otherwise, you may face clawback measures later for receiving excessive benefits.
When receiving the old-age pension while working, you must ensure your average monthly income does not exceed the threshold to avoid reduction.
3. Strategy for Receiving Both Basic Pension and Old-Age Pension

A significant number of seniors receiving the basic pension also receive the general old-age pension simultaneously, and they can enjoy both benefits if their recognized income is below the standard. Even if you are already receiving a survivor’s pension or disability pension, or if you are a recipient of the National Basic Livelihood Security or Disability Pension, you can apply for the basic pension if your monthly benefit amount is 524,550 KRW or less. At local senior centers, it is not uncommon to hear stories from seniors who feel wronged because they did not know they were eligible to apply, while their friends receive generous pensions. Although it is a right they are entitled to, many give up due to complex administrative procedures or lack of information, so family members should actively look after them. This is why many children share their experiences on blogs about checking their parents’ eligibility online, preparing necessary documents, and visiting the community center. If your income and assets are assessed to be below the selection criteria, you can receive a substantial additional monthly support, which is a great relief for your retirement life. Some people mistakenly believe that receiving the old-age pension automatically disqualifies them from the basic pension, but this is not true, so you must verify this directly. Instead of struggling with complex calculations, the most reliable method is to visit your local administrative welfare center for a consultation.
Even if you are an old-age pension recipient, you can apply for the basic pension and receive financial assistance if you meet the recognized income criteria.
4. Foreigner Additional Payment System and Recent System Improvements
Recently, controversy has grown over the additional payment system for foreign pension enrollees, prompting the government to actively work on improving the fairness of the social security system. Public outrage was sparked when it was revealed that some foreigners had paid premiums for only one month and then made a lump-sum additional payment for the long-standing arrears to meet the old-age pension eligibility. Reports of attempts to register spouses residing overseas as dependents to claim additional benefits intensified calls to fix the system’s loopholes. Although only a tiny fraction of cases followed proper procedures, general citizens expressed great concern that taxpayers’ money might be leaking into the wrong places. To receive the National Pension, a minimum payment period of 120 months is required. Previously, additional payments were allowed for up to 119 months, which created opportunities for abuse by short-term enrollees. In response to this social criticism, the government is reviewing various measures to introduce the principle of reciprocity and meticulously patch the system’s loopholes. Strengthening the transparency of the system to ensure that ordinary citizens who have diligently paid premiums for a lifetime do not feel deprived is a top priority. Many citizens hope that this controversy will serve as a turning point for the National Pension system to become fairer and more trustworthy.
In response to controversies over irregular additional payments by foreigners, the government is pushing for improvement measures to strengthen the fairness of the system.
5. How to Apply for the Old-Age Pension and Required Documents
To receive the old-age pension, you must submit an application to the nearest National Pension Service office or through their website when you reach the eligible age, regardless of your address. While the service sends out notices as retirement approaches, it is unfortunate that some seniors miss the application deadline by ignoring these notices. When applying, you must provide your ID and a copy of a bank account in your name. Depending on the situation, additional documents such as a marriage certificate or family relations certificate may be required. For seniors who are not comfortable using the internet, it is safer to have their children help them or to visit the office directly to proceed with the process alongside a helpful counselor. If visiting the office in person, wait times can be long, so it is helpful to make a reservation in advance or ensure you have all necessary documents ready. After submitting the documents, the review is usually completed within a few weeks, and you can verify that the pension amount is accurately deposited into your registered account on the scheduled date. Occasionally, children applying on behalf of their parents forget to bring a power of attorney or seal certificate, leading to minor mishaps where they have to make a second trip. If you are new to the system, it is necessary to mark the deadline on your calendar and prepare well in advance to avoid missing the cutoff.
To receive the old-age pension, you must apply directly to the National Pension Service with your ID and bank account copy when you reach the eligible age.
6. Recommendations for Successful Retirement Planning
The old-age pension is the most powerful and reliable pillar supporting a stable retirement in an aging society, so it is advisable to consistently extend your enrollment period from a young age. When discussing life after retirement with acquaintances, the pension amount is often the top topic, as it significantly impacts quality of life. Rather than easily giving up on paying premiums just because current income is low, you should actively utilize various government support schemes such as unemployment credits and additional payment systems. Since the system will continue to evolve in response to social changes, it is necessary to stay informed and keep a close eye on the latest information. We need the wisdom to view retirement not merely as the end of work, but as an opportunity to design a new life based on the pension assets accumulated over a lifetime. If you keep in mind the reduction criteria and the conditions for linking with the basic pension discussed today, you will be able to set a clear direction for your post-retirement financial planning. Please share this content with your loved ones and carefully check if there are any benefits you might be missing. We sincerely hope that everyone can enjoy a happy and comfortable golden retirement, using a robust pension system as a stepping stone.
Through thorough preparation and understanding of the latest systems, you can maximize your old-age pension and design a stable retirement.
Frequently Asked Questions
=