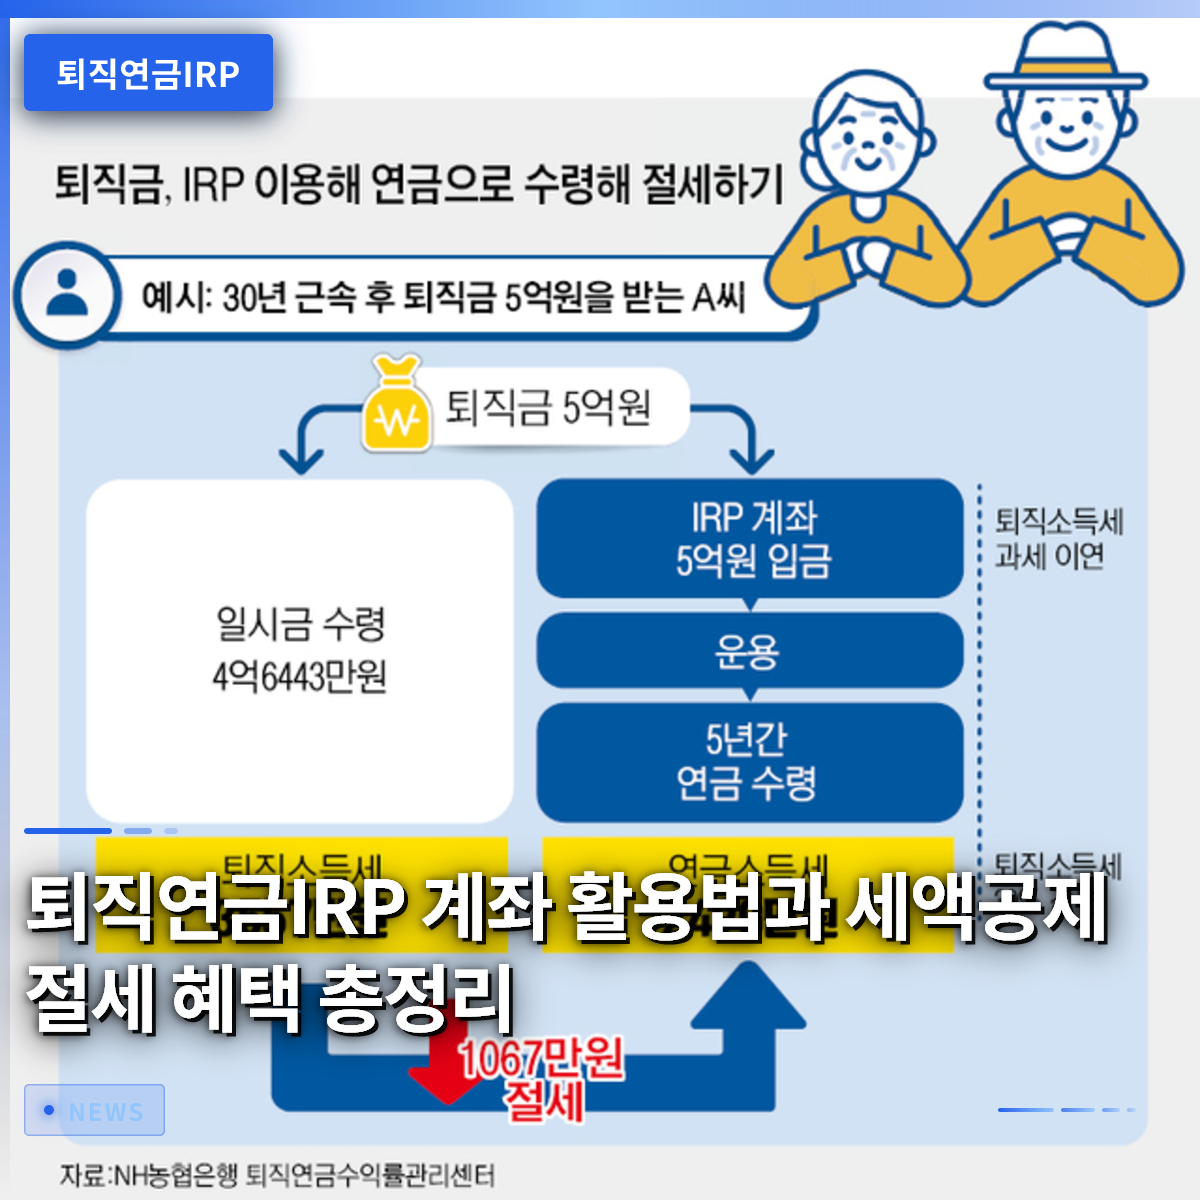
If you properly utilize your Individual Retirement Pension (IRP) account, you can receive tax refunds ranging from hundreds of thousands to millions of won during your year-end tax settlement. While it was once considered exclusive to office workers, the eligibility has recently expanded to include self-employed individuals and freelancers, establishing it as a core tool for retirement planning. In reality, many people view this account merely as a place to store their severance pay, but it is actually a powerful weapon that can transform your life after retirement. In this article, we will cover everything from the practical tax benefits of the account to efficient investment tips, leaving nothing out. We will explain the system, which can seem complex, using everyday analogies and specific examples to make it very easy to understand, so please follow along to the end.
=
A Complete Guide to Utilizing Your IRP Retirement Account and Maximizing Tax Deduction Benefits
1. What is an IRP Retirement Account?

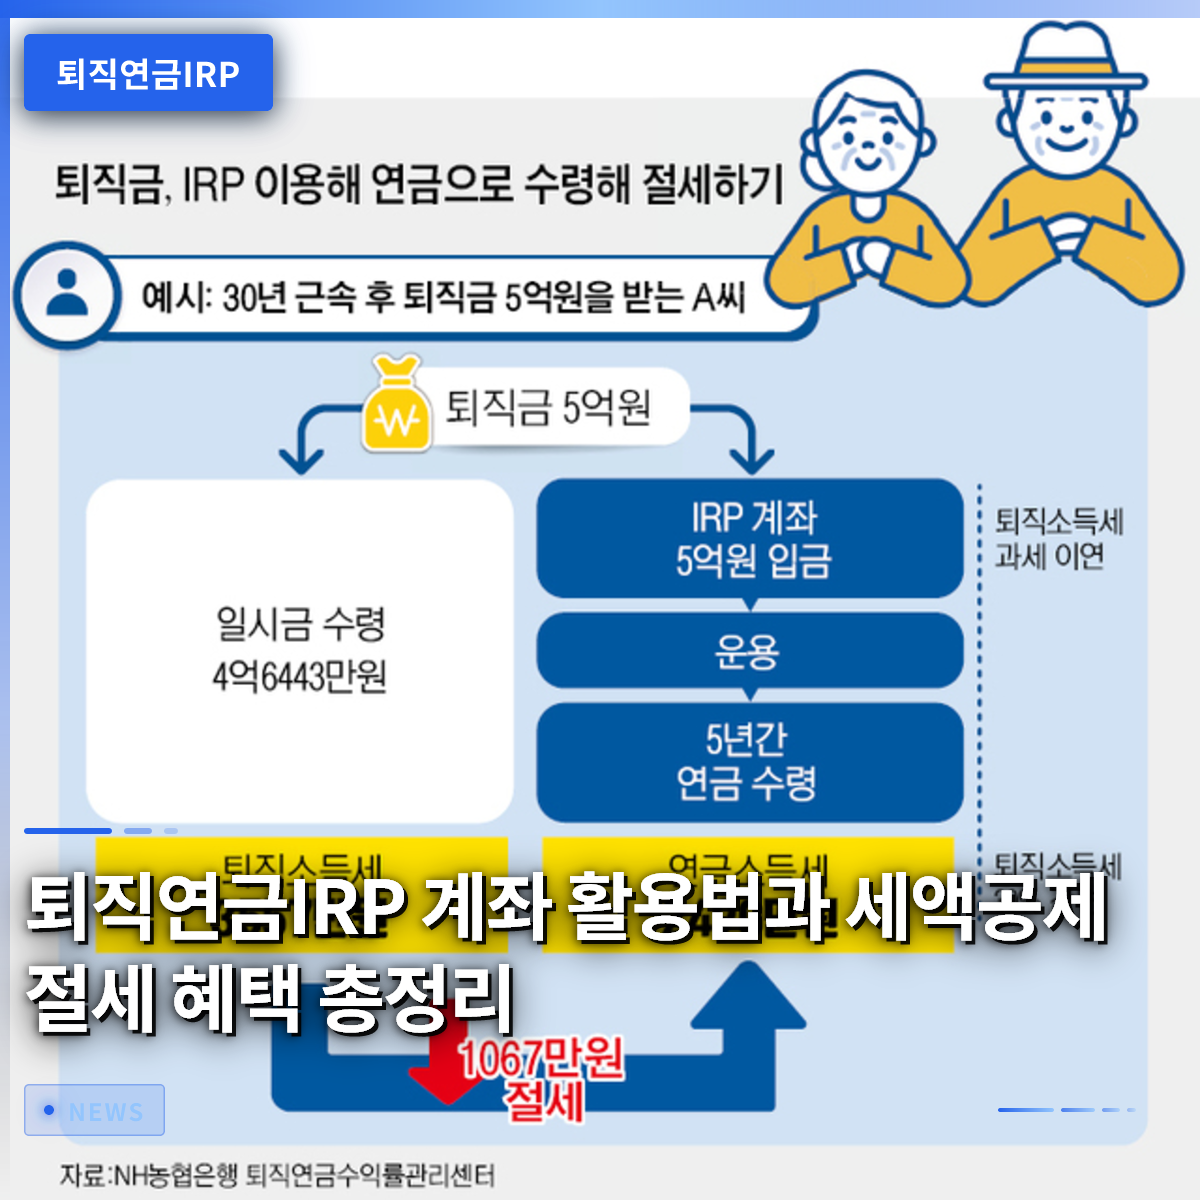
The IRP, known as the Individual Retirement Pension, is an account where employees consolidate their severance pay upon changing jobs or retiring, along with funds they voluntarily contribute, to manage themselves. It is separate from the employer-sponsored retirement pension accumulated monthly by the company, as individuals can directly open an account with financial institutions such as banks or securities firms. In the past, it could only be opened upon leaving a job, but the barriers to entry have been lowered, allowing current employees and self-employed individuals with income to open one at any time. A major advantage of keeping money in this account is that taxes are deferred until retirement, which maximizes the effect of compound interest. It is an essential stop on the journey of saving significant amounts during your working years and preparing for old age. If you receive your severance pay in a regular account, taxes are deducted immediately, reducing the actual amount you take home. However, if you transfer your severance pay to this account, you can defer paying taxes until the time you receive the pension, resulting in a significant tax-saving effect. For example, when receiving severance pay after nearly thirty years of service, taxes alone could amount to tens of millions of won; deferring this and reinvesting it is advantageous for growing your assets. This is why seniors often strongly advise transferring severance pay to this account immediately upon receipt. Ultimately, it serves as the safest shield to protect your precious assets from the “thief” of taxes.
The IRP is a personal account that simultaneously solves the issues of storing severance pay and forming retirement assets, while also providing tax deferral benefits.
2. Maximizing Tax Deductions and Benefits

As the year-end tax settlement season approaches every year, the biggest topic for office workers is undoubtedly tax refunds, and this account plays a key role in solving that. You can receive a certain percentage back within the maximum annual contribution limit, with the deduction rate varying based on your total income. If your total income is 50 million won or less, or if you meet specific criteria, you can receive a significant portion of your contributions back as a tax deduction, greatly increasing your actual rate of return. Because you can contribute small amounts monthly and feel like receiving a generous bonus at year-end, it is considered a basic formula for wealth management among office workers. Self-employed individuals and delivery riders, who do not have a fixed monthly salary, can also enjoy the same benefits if they meet the income requirements, leading to an explosive increase in the number of subscribers. In fact, Mr. Kim, an office worker, enjoyed the joy of receiving a tax refund of several hundred thousand won at last year’s settlement because he consistently contributed a fixed amount to this account every month. Had he not opened this account, the money he would have paid to the state has instead been accumulated as his retirement funds, achieving a two-for-one effect. He said he finally understood why his colleagues had been so insistent on joining pension products only after he actually received the money back. As small differences in habits can lead to asset differences of millions of won in a few years, starting now is more important than ever. The strategy of maxing out the tax benefit limit with contributions is the fastest shortcut for an ordinary office worker to become wealthy.
Receiving tax deductions within the annual contribution limit maximizes your year-end tax refund and simultaneously addresses retirement preparation.
3. Selecting Asset Management Products and Investment Strategies

Opening this account does not mean your money will just sit there; subscribers can directly choose and hold various financial products. You can combine products according to your preferences, ranging from principal-and-interest guaranteed products like deposits and savings to performance-linked products like equity funds and Exchange-Traded Funds (ETFs). Recently, robo-advisor services utilizing artificial intelligence algorithms and big data have been introduced, automatically proposing portfolios that match the subscriber’s investment style and goals. This is very useful for beginner investors as it helps allocate assets from a long-term perspective without being shaken by short-term market crashes or volatility. You can easily receive expert-level asset management without losing sleep over which products to buy every time the stock index fluctuates. Due to recent regulatory changes, the range of choices has expanded further, as it is now possible to purchase not only general products but also individual investment government bonds through pension accounts. As retirement approaches, the proportion of safe assets should be increased, and products like government bonds are an excellent alternative for defending against volatility. Investment methods that were previously daunting due to complex procedures can now be done with just a few clicks, allowing anyone to easily grow their assets. If you feel tired of buying and selling stocks yourself, it is wise to actively utilize asset allocation programs designed by experts. It is a time when the wisdom to flexibly navigate market waves while consistently investing in quality assets through regular accumulation is required.
You can choose from a variety of products, including deposits, funds, and government bonds, and achieve stable management through AI-based asset allocation services.
4. Important Precautions When Terminating the Account
This account is like a treasure chest hidden away for your old age, and terminating it or withdrawing money midway can come at a surprisingly high cost. If you misunderstand it as a regular deposit or savings account that can be accessed anytime and terminate it without thinking because you need urgent cash, you may suffer a major loss. Statistics showing that a significant portion of contributions in recent years were terminated midway indicate that many people overlook the weight of tax benefits. If you terminate the account midway, you not only have to return all the tax deduction benefits you received but also face the additional burden of miscellaneous income tax. After taking a tax bomb hit from the money you worked hard to save, there is often little left, leading to a sense of frustration, so you must approach this with great caution. However, in unavoidable situations such as bankruptcy, natural disasters, or the need for long-term treatment for yourself or a dependent family member, you can withdraw the money without penalty as an exception. But if the purpose is simply to buy a car or secure a house, it is much more beneficial to look for other sources of funds rather than making a mid-term withdrawal or termination. Breaking a pension account, which is the lifeline of your old age, just because you need a lump sum is no different from betraying your future self. If you have seen acquaintances who joined solely for the tax refund and later faced difficulties because their money was locked up, you will realize how serious this warning is. It is absolutely necessary to start with the firm resolve not to touch the account from the moment you open it until retirement.
Terminating the account midway requires returning the tax deduction benefits received and may result in a tax penalty, so it should be maintained unless there are special circumstances.
5. Pension Receipt Methods and Maximizing Tax Savings
When retirement arrives and it is finally time to withdraw the money, the key to reducing taxes is to receive it in the form of a pension rather than a lump sum. If you receive your severance pay all at once, you must pay high-rate severance income tax, but if you receive it in installments over a period of ten years or more through a pension account, taxes are significantly reduced. If you withdraw small amounts within the pension receipt limit, a much lower pension income tax is applied as an incentive from the state, increasing your actual income. Creating a structure where cash flow comes in monthly like a salary during old age allows for a psychologically more stable retirement life. When you add the National Pension, the Housing Pension, and the pension from this account, a perfect three-tier pension pyramid is built. Many retirees realize that the National Pension alone is insufficient to defend against inflation when calculating their post-retirement living expenses. At that moment, the cash flow from this pension account acts as a reliable lubricant, dramatically improving the quality of life in old age. The secret to maintaining a dignified life without having to ask children for money lies in this pension receipt strategy. The longer you set the receipt period, the more the tax burden decreases, and since the remaining amount continues to grow, your assets do not deplete easily. To truly feel that retirement is not an end but a new beginning, it is good to start building your receipt plan step by step now.
Receiving funds in pension form rather than a lump sum after retirement significantly reduces severance and pension income taxes and secures a stable cash flow.
6. Wise Practices for Retirement Preparation
As we have seen, this account is not just a savings account but the most powerful and reliable partner that protects and grows your lifetime assets. Those who join as soon as possible to enjoy the magic of compound interest and secure tax deduction benefits will inevitably become the ultimate winners in the retirement market. You should approach this with the will to design your old age with your own hands and take the initiative, rather than reluctantly joining just because everyone else is doing it. The financial environment will change even faster in the future, and AI-based asset management tools will continue to evolve to assist us. If we keep up with the changing system by maxing out our annual contribution limits and protecting our assets steadily, our old age will shine brightly. I sincerely hope that the moment you read this article becomes the most important turning point in your asset management. Just as sturdy hiking boots and a walking stick are essential when climbing the great mountain of retirement, this pension account is like the most powerful climbing gear for our lives. Setting up automatic transfers for a fixed amount each month and not worrying about it is actually the most straightforward yet certain method to increase the success rate of long-term investment. If you do not get shaken by outside noise and steadily push forward with your investment plan, you will find yourself smiling at the numbers in your account in a few years. Do not put it off until tomorrow; show a little initiative today by opening your smartphone app to open an account or check your contribution limit. Your abundant and stable old age truly begins with this small step you take today.
Retirement preparation should not be delayed; starting now with consistent contributions and long-term investing guarantees a successful old age.
Frequently Asked Questions
=