Closing an Individual Retirement Pension (IRP) account midway can result in a significant tax burden, so careful fund management is essential. Many people close their IRP accounts early due to a sudden need for a large sum of money, only to realize too late that they must pay a substantial amount of miscellaneous income tax. In fact, statistics show that a significant portion of funds transferred to IRP accounts in recent years has been withdrawn, indicating that many people choose to close these accounts without fully understanding their characteristics. Therefore, we must understand the exact nature of IRP accounts and establish the correct strategies to protect our retirement funds. In this article, we will examine in detail everything from the basic definition of an IRP account to specific methods for fully utilizing tax benefits. By reading this article to the end, you will gain the wisdom to protect your precious retirement savings and save on taxes.
=
Essential Guide to Avoiding Tax Penalties and Maximizing Your IRP Account Before Cancellation
1. What is an IRP Account?

An IRP is a system that consolidates severance pay received upon changing jobs or retiring, as well as voluntary personal contributions, allowing individuals to manage the funds themselves and receive them as a pension in retirement. It helps with broad retirement preparation, as anyone with a certain level of income, including self-employed individuals and freelancers, can join. In the past, severance pay was primarily received as a lump sum, but the government and financial sector strongly encourage receipt through an IRP to strengthen retirement security. Since severance pay is often automatically transferred to this account when employees change jobs, it is already a familiar concept for many workers. However, many people hold these accounts without understanding exactly how their assets grow, leaving them neglected. This account is not merely a piggy bank for storing money; it is a comprehensive asset management box that allows investment in various financial products while enjoying tax benefits.
Actively utilizing an IRP account in your own name can help you prepare more securely for life after retirement. For example, by saving a fixed amount monthly, you can simultaneously receive tax deduction benefits during the annual tax settlement, achieving a two-for-one effect. Instead of just envying colleagues who receive substantial tax refunds every year, you should open an account and start contributing yourself. Carefully reviewing the list of various products offered by financial institutions and choosing one that suits your investment style is the first step toward successful retirement preparation. While immediate living expenses may seem more urgent right now, failing to establish a cash flow for after retirement can lead to significant difficulties later. Therefore, you must accurately understand the basic structure of the IRP account and start the habit of adding funds little by little every month, starting today.
IRP is an essential account for preparing for retirement by pooling severance pay and personal contributions while enjoying tax benefits.
2. Reasons for High Cancellation Rates and the Truth About Tax Penalties

In recent years, while many people have opened IRP accounts, a high cancellation rate is causing retirement funds to be scattered. According to statistics, the ratio of withdrawn amounts to transferred amounts is very high, prompting serious attention from the government and financial authorities. The primary reason for this high cancellation rate is that IRP accounts are the easiest source of funds to tap into when a sudden large sum is needed or when immediate living expenses are lacking. However, the moment you cancel midway, you must return all the tax deduction benefits received so far and face a terrifying tax penalty in the form of miscellaneous income tax. Seeing the money you saved diligently shrink due to taxes and surcharges can inevitably lead to a sense of self-reproach.
As a specific example, Mr. Kim, an office worker who had consistently contributed to his IRP and fully enjoyed tax deduction benefits, faced a situation where he urgently needed to increase his deposit for a jeonse (long-term lease). Without consulting a bank, Mr. Kim rashly closed his entire IRP account. A few days later, he was shocked to see a settlement notice from the National Tax Service. He had to pay a much larger amount in miscellaneous income tax than the taxes he had previously saved. Choosing to cancel without properly understanding the system leads to massive financial losses, making it an action to be avoided at all costs. When a large sum is urgently needed, it is wise to first check if the situation qualifies for legally permitted exceptional withdrawal reasons rather than closing the entire account. In special circumstances such as purchasing a home, securing a jeonse deposit, or the bankruptcy of oneself or a family member, there are ways to utilize part of the funds without closing the account.
Midway cancellation of an IRP triggers the return of tax deductions and a miscellaneous income tax penalty, so check for exceptional withdrawal reasons first.
3. Why You Must Receive Severance Pay Through an IRP

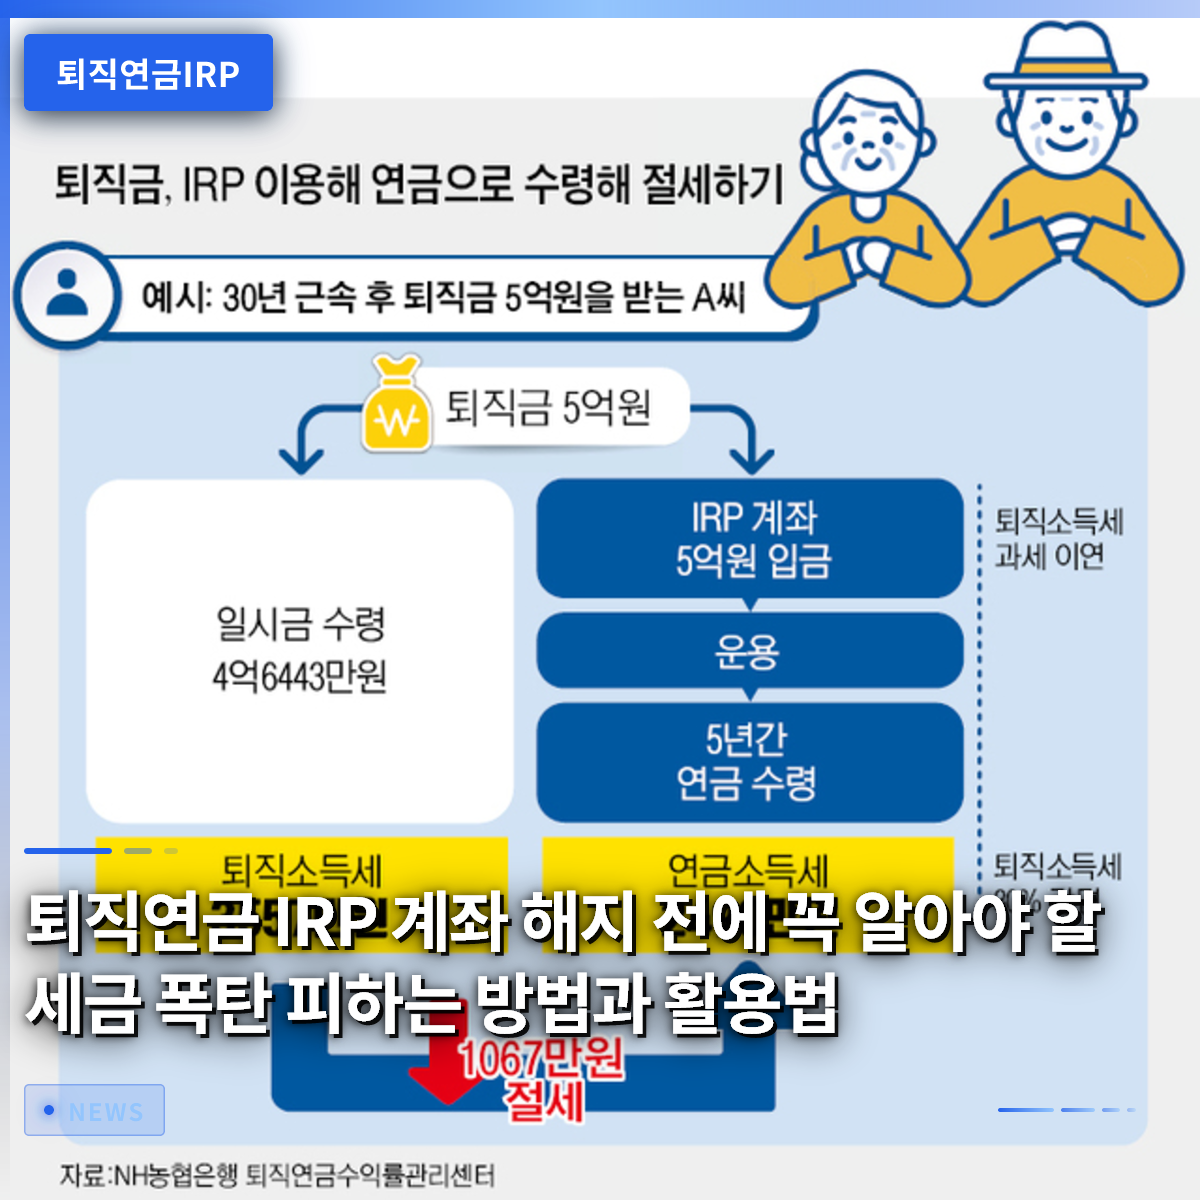
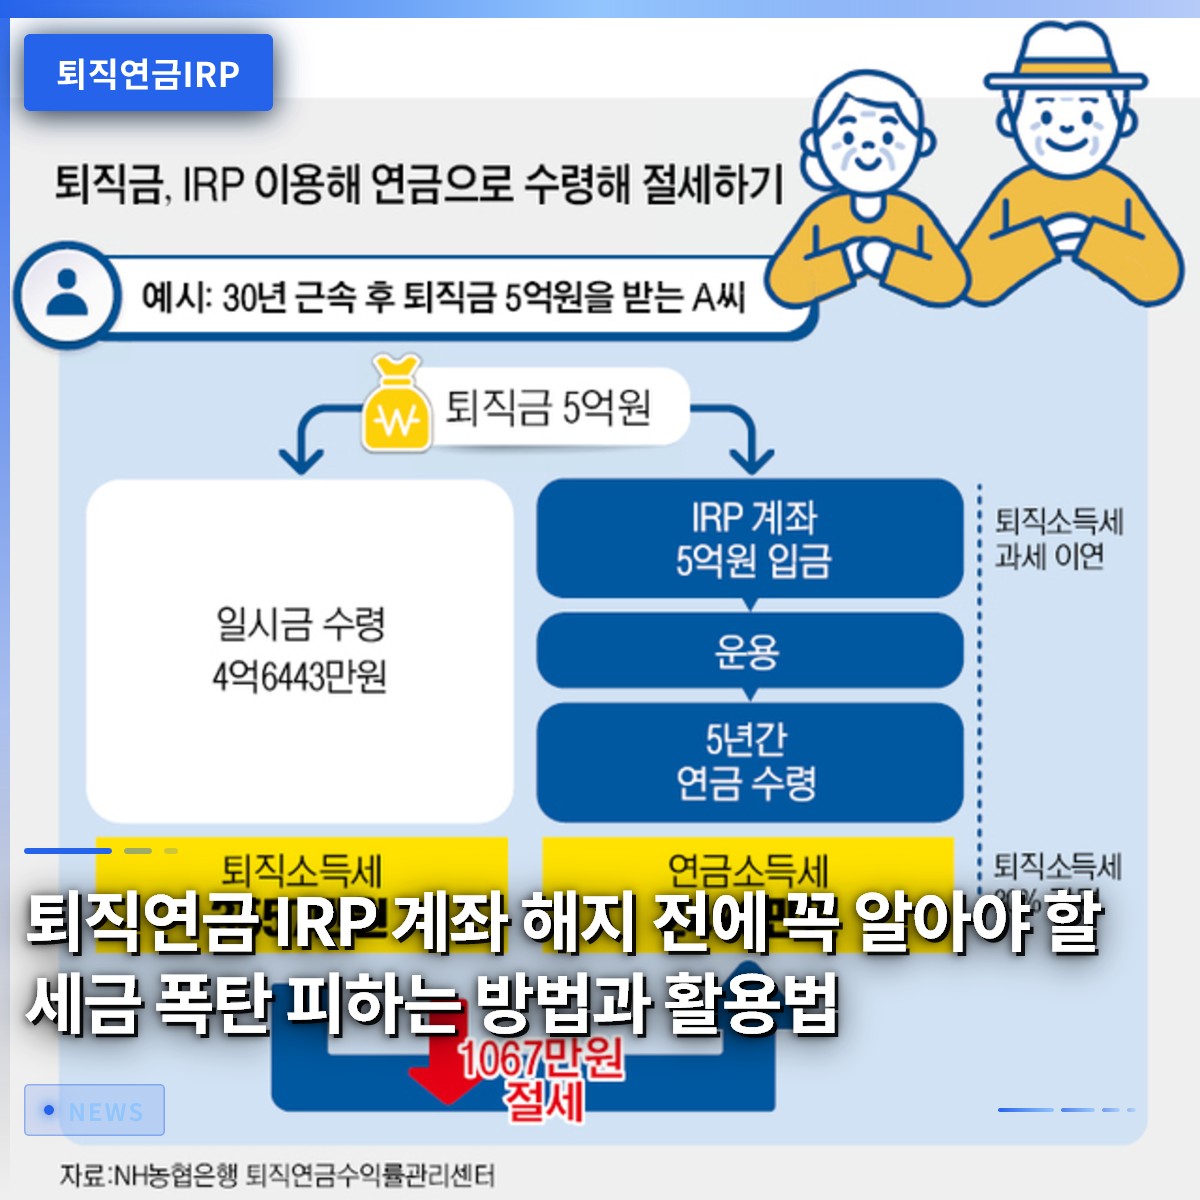
If you are approaching retirement or preparing to change jobs, receiving your severance pay into an IRP account is overwhelmingly advantageous from a tax perspective. The severance income tax incurred when leaving a company can be quite substantial. However, if you transfer this money to an IRP account instead of putting it directly into your personal pocket, the tax is not deducted immediately, and taxation is deferred. In other words, since the tax payment is postponed until old age when you actually receive the pension, you can enjoy the compound interest effect of managing a larger amount. The government also provides a benefit of discounting severance income tax when received through an IRP account to encourage citizens to protect their retirement funds intact.
If you ignore this process and receive your severance pay directly into a regular bank account, you will only hold the remaining amount after the full tax deduction. The money lost to taxes permanently loses the opportunity to grow through compound interest, resulting in a significant loss in asset accumulation. This is why retirement experts unanimously advise that severance pay should always be received through an IRP. If the severance pay deposited into the account is later received in the form of a pension rather than a lump sum, you can enjoy a much greater reduction in severance income tax. Saving on taxes is equivalent to increasing your rate of return, so this process should never be taken lightly. Employees approaching retirement should contact the HR department in advance to submit their IRP account number accurately and secure the tax deferral benefits.
Receiving severance pay via IRP defers taxes and provides severance income tax reduction benefits, helping to protect your assets.
4. Diverse Asset Management Products and Utilizing Robo-Advisors
If you leave your money idle after opening an IRP account, it may not keep up with inflation, causing your real asset value to decline. Within this account, you can directly invest in a variety of assets, ranging from principal-and-interest guaranteed products like deposits and savings to risky assets such as equity funds and exchange-traded funds (ETFs). Recently, financial companies have been actively operating robo-advisor services that analyze customer investment tendencies based on AI algorithms and big data to propose optimal asset allocation portfolios. For office workers who find it difficult to monitor complex financial market conditions daily, this robo-advisor technology serves as a reliable investment partner.
In fact, subscribers who have engaged in long-term investing using robo-advisors have reported satisfaction, recording stable returns even amidst market volatility. Statistical results also show that it effectively reduces the maximum loss range compared to general investment methods, making it very useful for risk management. Additionally, recent regulatory improvements have allowed the purchase of government bonds for individual investors within IRP accounts, broadening the options for safe assets. If you are anxious about the high volatility of the stock market, you can include safe government bonds in your portfolio to protect your retirement funds with peace of mind. It is recommended to carefully consider your investment goals and remaining investment period, and then regularly rebalance with the help of expert advice or algorithms.
You can choose from various products such as deposits, funds, and government bonds within an IRP account, and can also utilize AI asset allocation.
5. Maximizing Tax Deduction Limits and Designing Post-Retirement Cash Flow
The core of retirement preparation lies in firmly building the three-tier pension pyramid, which encompasses the National Pension, the Occupational Pension, and the Personal Pension. Among these, the IRP is a highly beneficial product that offers substantial tax deduction benefits on annual contributions when combined with the pension savings account. By filling the account up to the designated annual limit, you can secure a generous refund during the annual tax settlement, establishing it as an essential wealth management tool for office workers. The funds accumulated in this way create a steady monthly cash flow after retirement, serving as a reliable pillar that alleviates concerns about living expenses.
You can easily observe people around you diligently checking their IRP contribution amounts around autumn to widen their annual tax settlement refunds. If putting in a large sum at once feels burdensome, it is recommended to set up automatic transfers aligned with your payday to consistently accumulate small amounts. The funds steadily accumulated during your working years will serve as a vital lifeline when economic activity ceases in old age. If the pension amount deposited into your account monthly after retirement is sufficient, your quality of life will visibly improve. Reducing current expenses to invest in an IRP is like giving your future self the most certain and safe gift.
Contribute consistently every year to receive tax deductions and create a secure monthly cash flow similar to rent after retirement.
6. Practical Strategies and Outlook for a Successful Retirement
The IRP is no longer an option but an essential survival tool for living a stable life after retirement. While the complexity of the system may make it seem difficult to approach initially, once you grasp the basic principles, there is hardly a more powerful tax-saving tool. As various technological advancements in the financial market and regulatory improvements converge, the asset management environment for individual subscribers is expected to become more convenient. The government is also expected to continue refining IRP activation policies to prevent retirement poverty among citizens. Therefore, we must keep up with the times by accumulating financial knowledge and actively managing our accounts.
Even now, many people are unknowingly closing or neglecting their accounts, eroding their precious assets. Readers of this article are encouraged to check the status of their IRP accounts today and start remodeling them with the help of experts or smart products. Small attention and practice can lead to a significant difference in assets by the time of retirement in a few years. Keep in mind that the earlier you start preparing for retirement, the more advantageous it is, and take action now. We support you in becoming a wise retirement planner who takes one step at a time toward a secure and comfortable retirement.
IRP is an essential retirement preparation tool, so check your account immediately and manage it actively.
Frequently Asked Questions
=