A gloomy forecast has emerged from the securities industry that LG Chem’s Q3 operating profit this year will plummet by over 76% compared to the previous quarter, drawing deep sighs from investors. In the previous quarter, the company delivered a solid performance that easily exceeded market expectations, benefiting from a rebound effect due to geopolitical instability in the Middle East and one-off positive factors. However, as the impact of these one-off factors quickly fades, the sluggishness in its core basic materials business is directly translating into a decline in overall performance. To make matters worse, with the Fair Trade Commission and the prosecution pointing their swords at the company over suspicions of price-fixing for major petrochemical products, there are concerns about an astronomical fine bomb of up to 1.4 trillion won. In this article, we will thoroughly dissect the reality of the crisis facing LG Chem’s diversified business portfolio and carefully examine what phase the stock price is likely to enter. We will provide concrete examples of how fluctuations in the raw material prices of everyday items like plastic containers and building materials can shake the performance of major corporations, making the implications clear. If you follow along step by step, you will understand the context of complex economic news, including why securities firms are collectively lowering their target prices.
=
Analysis of LG Chem’s Projected 76% Q3 Operating Profit Decline and Potential Fine of Up to 1.4 Trillion Won
1. The Secret Behind the Q2 Surprise Performance and the Fading of One-Off Effects
In the previous quarter, LG Chem recorded robust results that completely defied market expectations, offering a moment of joy to many shareholders. Amid fears of supply disruptions in crude oil due to the aftermath of armed conflicts in the Middle East, the company benefited significantly from cost reductions by having secured cheap raw materials in advance. Additionally, a temporary global rebound in petrochemical product prices led to a substantial improvement in margins. In the Bio & Life Sciences division, the company even secured a large-scale technology export contract, generating considerable cash flow beyond its core business. Thanks to these favorable factors, which arrived like a timely rain in a drought, the Q2 operating profit margin hovered around the 4% line, showing rare vitality. However, all these factors were not the result of structural improvements but rather one-off gifts where external circumstances coincidentally aligned. As time passed, the benefit of low-cost raw materials from the Middle East vanished without a trace, leaving only the harsh reality of oversupply. The moment these temporary factors supporting the performance disappeared, the company’s true vulnerability was starkly exposed. This is exactly like a neighborhood supermarket seeing a rush of customers during a brief flash sale, only for foot traffic to drop off immediately once the promotion ends. This serves as a reminder that investors should always keep a close eye on the fundamental strength of the core business rather than cheering for temporary performance improvements.
With the disappearance of the one-off positive factors that drove Q2 results, LG Chem is entering a phase of sharp profitability decline starting from Q3.
2. Q3 Performance Estimates and the Shock of the Petrochemical Division Turning to a Loss
According to forecasts aggregated by the financial investment industry, LG Chem’s Q3 revenue is expected to be around 13.5 trillion won, which is a reasonably decent figure compared to the same period last year. However, operating profit, a key indicator of a company’s core earnings, is expected to remain between 750 billion and 1,400 billion won, representing a sharp drop of over 76% from the previous quarter. This means that while the scale of total revenue is being maintained, a distorted structure where there is no real profit is becoming entrenched. In particular, the petrochemical division, which forms the foundation of the company, is feared to halt its streak of profits enjoyed until the previous quarter and record a massive operating loss of over 1 trillion won. This is because the prices of numerous basic plastic materials used in daily life, such as polyvinyl chloride (PVC) and caustic soda, are hitting rock bottom. A worst-case scenario is unfolding where losses accumulate the more the factories operate, causing the overall operating profit margin to plummet to a floor of 1%. It is similar to how housewives feel that ordering delivery food is cheaper than buying ingredients and cooking themselves; the cost of operating the factories has become higher than the selling price of the products. This sluggishness in basic materials is not merely a one-quarter fluke but is intertwined with a global oversupply structure, posing a more serious concern.
Although revenue scale is maintained, Q3 operating profit is expected to drop by 76% due to the basic materials business turning to a loss.
3. The Supporting Role of Advanced Materials and Energy Solutions
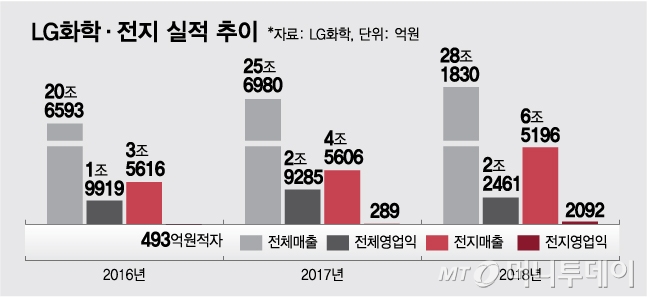
While the basic materials business struggles, the Advanced Materials division and the battery subsidiary, LG Energy Solution, are playing the role of saviors that keep the company afloat. The Advanced Materials division is expected to defend operating profits in the hundreds of billions of won by consistently generating demand for high-value-added products, including battery cathode materials. LG Energy Solution, boasting world-class technology, is also expected to record a profit in the trillions of won, effectively serving as a pillar for the consolidated results. Although concerns are pouring in that the growth of the electric vehicle market is not as strong as before, the company is still processing stable volumes for massive global customers. In the past, all of the company’s revenue came from traditional chemical products like plastics and rubber, but the portfolio has now become highly diversified. Even if petrochemicals have fallen into a swamp of massive losses, the two pillars of secondary batteries and advanced materials are holding the line, preventing total collapse. It is like a situation where, when the walls of a fortress besieged on all sides are about to crumble, two sturdy internal bastions hold out desperately to prevent enemy intrusion. From an investor’s perspective, the extent to which high-tech stocks can offset the sluggishness of traditional chemicals will be the key criterion determining the future direction of the stock price.
Despite the sluggishness in basic materials, the Advanced Materials division and the battery subsidiary are recording profits, establishing a minimum defense line for the company.
4. Concerns Over a Price-Fixing Fine Bomb of Up to 1.4 Trillion Won
In addition to the bad news of sluggish performance, the most frightening factor keeping LG Chem on edge is the suspicion of product price-fixing currently under investigation by authorities. High-intensity investigations by the prosecution and the Fair Trade Commission have been ongoing for several years, centered on the so-called “vinyl chain” product group, including PVC, caustic soda, and plasticizers. According to securities industry analysis, if the recently strengthened fine calculation criteria and estimated revenues for these products over the past five years are all applied, the worst-case scenario unfolds. Calculations suggest that astronomical fines ranging from a minimum of approximately 700 billion won to a maximum of 1.39 trillion won could be deducted from the company’s accounts. Of course, since there is no final judgment yet, the amount may fluctuate depending on the actual factory operating rates and the specific application period. However, compared to the company’s market capitalization, it is undoubtedly a major negative factor that cannot be ignored, and shareholder anxiety has reached its peak. It is similar to the shock of receiving a traffic violation fine so inflated that it requires returning several years’ worth of salary. For the company, this uncertainty itself acts as the heaviest shackle preventing stock price growth.
As authorities’ investigations into price-fixing intensify, the risk of a massive fine of up to 1.4 trillion won is weighing on the company’s value.
5. Downward Revision of Target Prices and Cooling of Investor Sentiment
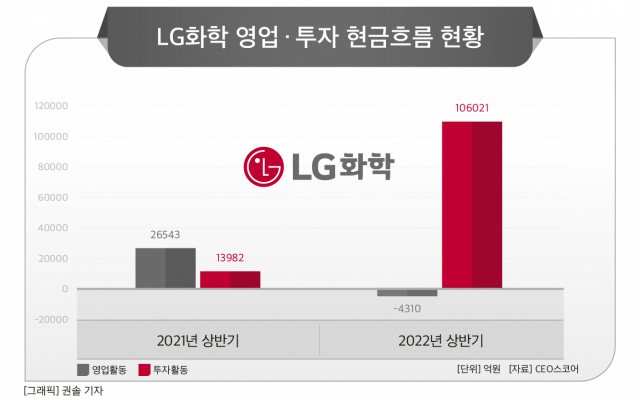
As these overlapping bad news items emerged, major securities firms collectively lowered their expectations for LG Chem, revising the target price down to the 235,000 won line. This figure leaves room for a decline of nearly 10% compared to the previous trading day’s stock price, and the investment rating remains at a neutral “Hold.” The target price was lowered by reflecting only the pure deterioration in performance and changes in the subsidiary’s market capitalization, even though the unconfirmed price-fixing fine risk was excluded from the calculation. The market judges that it will be difficult to find a definitive momentum for the company to rebound in the near term, leading institutional and foreign investors to sell off their holdings. The stock market is a creature that hates future uncertainty the most, and with a performance shock and legal risks overlapping, the stock price lacks strength. Among individual investors, cries of despair are emerging over the difficulty of gauging where the bottom is, and a conservative approach has become the mainstream for the time being. It is like a merchant who bought goods to sell only to face a flood of returns due to defective product judgments, with a tax audit also looming; business is hardly going well. Currently, the gaze on LG Chem in the stock market is less about its past glory and more about strictly verifying its current crisis management capabilities.
Reflecting the slowdown in performance and fine concerns, the securities industry is lowering target prices and advising investors to adopt a conservative approach.
6. Outlook and Wise Countermeasures for Shareholders
As reviewed above, LG Chem is squarely facing the massive waves of a long-term downturn in the petrochemical industry and an impending astronomical fine. While the Q3 earnings release will likely confirm a short-term performance bottom, the external economic variables are too complex for the industry itself to make a V-shaped sharp rebound. Therefore, rather than rushing to buy at the bottom, it is wise to calmly observe how the company resolves the price-fixing risk and how much certain profit it generates in the advanced materials division. From a long-term perspective, investors who believe in the growth potential of batteries and new materials might consider a split-buying strategy, but they must be thoroughly prepared for immediate stock price volatility. When consuming economic news, it is necessary to have the insight to read the hidden legal risks and structural changes in the industry, rather than just being surprised by the magnitude of the performance figures. Wisdom is required to closely monitor the final sanction results from the Fair Trade Commission and the Q4 petrochemical price trends and respond calmly. It is like a massive oil tanker navigating the open sea encountering a fierce storm and reefs simultaneously; however, with sturdy lifeboats, it must find a way to safely escape. We hope that readers will make wise decisions, whether to use this crisis as an opportunity or to step back and observe, based on their own investment principles.
Investors should maintain a calm and conservative investment strategy while watching for the confirmation of the Q3 performance bottom and the resolution of fine risks.
Frequently Asked Questions
=