The annual household loan growth targets for the five major commercial banks have hit rock bottom in just one month, making it highly likely that a severe “loan cliff” will become a reality by the end of this year. Although financial regulators doubled the household loan growth target for this year to ease the situation, it appears the banks were unable to handle the surging demand. In fact, major banks such as KB Kookmin, Shinhan, Hana, Woori, and Nonghyup have exhausted their additional loan capacity within a mere month. As a result, many people who approached banks to buy their first home are experiencing the absurd situation of being rejected for mortgage loans or finding that applications are closed almost instantly. In this article, we will carefully examine the background behind the exhaustion of commercial bank loan limits and the impending impact on the real estate market at year-end. If you are planning to purchase a home or sign a jeonse (lump-sum lease) contract, you should pay close attention to the news shared below.
=
Can’t Get a Mortgage? The 5 Major Banks’ Loan Limits Have Hit Rock Bottom, Warning of a Year-End Loan Cliff
1. Additional Loan Capacity Vanished in an Instant
The household loan limits that major domestic commercial banks barely secured through negotiations with financial regulators have been completely exhausted in just one month. As of the 17th, the household loan balances of the five major commercial banks had already recorded figures far exceeding their annual targets. While regulators slightly eased loan regulations, granting each bank new additional loan capacity worth trillions of won, this capacity melted away like snow due to a sudden influx of pending demand for home purchases coinciding with the autumn moving season. Even bank insiders are expressing their astonishment, admitting they did not expect the loan limits to be depleted so quickly.
In particular, some banks have already significantly exceeded their set annual growth targets and have entered an emergency state. They are notifying customers who come to take out loans that new applications are temporarily difficult to process, or they are internally managing by splitting monthly allocation limits. This situation is not merely a problem specific to certain banks but a phenomenon common across the entire financial sector. Consequently, the threshold for household loans is not expected to lower throughout the second half of the year; instead, it is projected to become even higher.
Commercial banks have exhausted their increased loan limits in just one month, triggering an emergency in household loan management.
2. Shinhan Bank Loan Applications Closed in Just Two Days
A representative case illustrating how quickly loan limits are being exhausted is the closure of loan applications through Shinhan Bank’s loan solicitors. Shinhan Bank resumed accepting household loan applications through loan solicitors, which had been suspended earlier this month, but had to close the doors after just two days. This was because the entire monthly allocation limit was depleted in a mere 48 hours. Customers who visited branches or attempted to apply through solicitors were met with the shocking news that applications were closed as soon as they opened.
This phenomenon is not significantly different at other banks, leaving those seeking loans in a state of frantic confusion. Hana Bank has also resumed accepting applications for some executed loans starting this month, but it is continuing a precarious tightrope walk, unsure of when its limits will be exhausted. The Industrial Bank of Korea is also exerting full effort in total volume management by strictly setting monthly application limits. The reason banks are locking down their lending is to avoid potential penalties for exceeding their annual targets.
At major banks such as Shinhan Bank, loan limits have been depleted in just two days, leading to a series of application closures.
3. The Reality of the Year-End Loan Cliff and the Blow to Genuine Demand
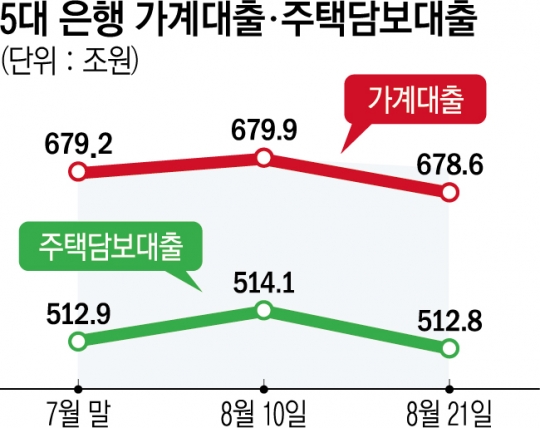
The financial sector is concerned that a severe loan cliff phenomenon will emerge by the end of this year as total household loan volume management continues. The contradictory situation is that funding demand is at its peak due to the overlap of the autumn moving season and the year-end wedding season, while bank coffers are empty. The sighs of non-homeowner low-income earners and genuine demanders looking into jeonse loans, in addition to mortgages, are growing deeper. As the date for paying the final settlement approaches, if they cannot borrow money from banks, they risk losing their deposit or being forced to hurriedly seek high-interest products.
In reality, even if essential funds such as moving costs, interim payments, and final settlement loans are excluded from certain management targets, the overall loan flow is frozen. Since commercial banks must suppress the pace of household loan growth to the maximum extent for the remainder of the year, they are reluctant to issue new loans. Unlike in the past, it is difficult to expect loan windows to open generously at year-end. Ultimately, it is ordinary office workers and newlyweds who have planned to buy their first home who are taking the direct hit.
As loan limits are exhausted during the peak year-end moving season, the damage to genuine demanders is increasing.
4. Subtle Changes in Total Household Loan Balances
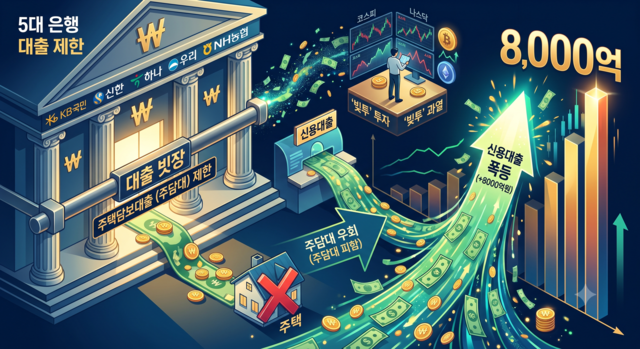
While the total volume of household loans across the banking sector is growing rapidly, there are also noticeable parts where balances have temporarily decreased in the statistics. The total household loan balance of the five major commercial banks, including policy loans, showed a slight decrease compared to the previous month in recent tallies. This is an unusual event, marking the first time the total balance has recorded a downward trend in about half a year since last spring. This is a result of policy products supported by the government and general commercial bank household loans showing different trends.
However, one must absolutely not misunderstand that the loan environment has become more relaxed based solely on this statistical figure. Demand for general bank funds, excluding policy funds, remains explosive, and the figures reflect the result of banks locking down their lending on their own. In other words, it is close to a statistical illusion caused by banks being unable to lend, rather than people choosing not to borrow. For genuine demanders, the fact that securing necessary funds from commercial banks remains as difficult as “catching a star in the sky” has not changed.
Although the total balance has temporarily decreased in the statistics, this is merely a phenomenon caused by banks tightening their lending.
5. The Banking Sector’s Strict Monthly Total Volume Management System
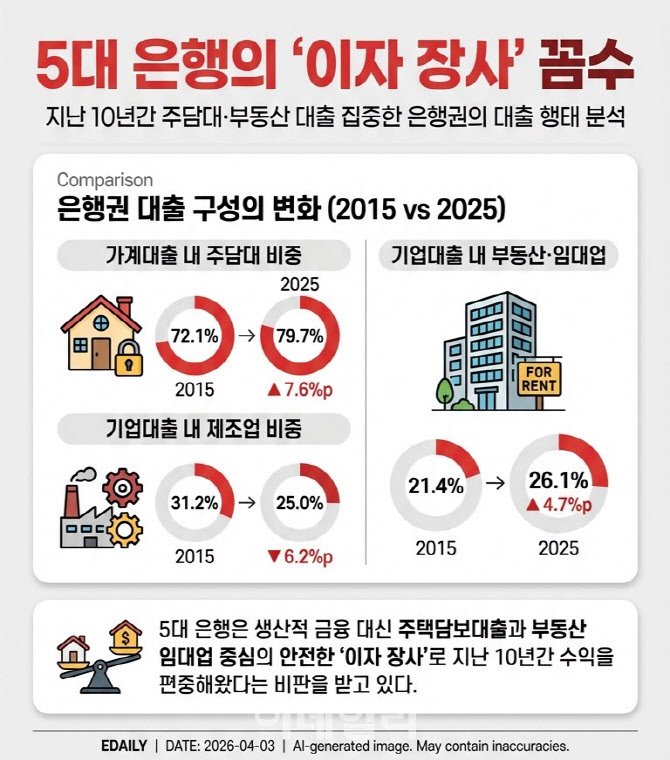
For the remaining period, commercial banks plan to adhere to a monthly total volume management method that strictly controls limits. For banks that must watch the financial regulators’ reactions if they exceed their set annual targets, risk management is the top priority. Consequently, a policy is solidifying where, once the loan limit allocated to each bank branch is exhausted, no new loans will be issued for that month. From the customer’s perspective, the structure is such that if they do not apply quickly at the beginning of the month, it becomes impossible to secure funds by their desired date.
This situation is causing significant confusion not only in banks but also in the loan solicitor market. Since solicitors must deal with customers using the limited volume allocated by banks, competition has become even fiercer. Some customers are running around visiting multiple banks simultaneously to check loan eligibility, but they often come up empty-handed. As banks’ funding sources dry up, inconvenience and confusion for financial consumers are expected to continue for the time being.
Banks plan to introduce a monthly limit management method to strictly control total loan volume until year-end.
6. Revising Home Purchase Plans and Smart Response Strategies
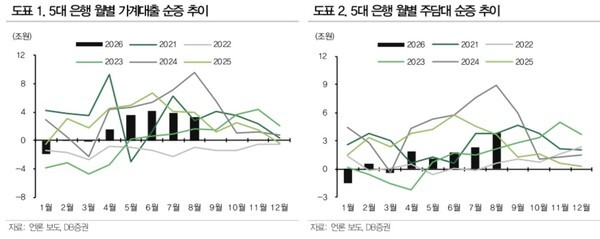
Now that the exhaustion of household loan limits and the year-end loan cliff concerns have become reality, strategies for viewing the real estate market must be completely restructured. It is essential to check loan eligibility and timing in advance through your primary bank or multiple financial institutions before signing a contract for a home. One must avoid the worst-case scenario of signing a contract first and then having to forfeit the deposit because they cannot meet the final settlement date. In particular, it is necessary to have the wisdom to act swiftly at the beginning of each month, understanding the characteristic that loan solicitor applications close almost instantly.
Continuously monitoring government policy changes and commercial banks’ fund management situations through the news is also a very important coping method. Rather than making unreasonable funding plans, it is recommended to approach safely by postponing the schedule to early next year or increasing the equity ratio. As financial market uncertainty is higher than ever, thorough preparation is the only way to protect your assets. Please keep a close eye on additional loan guidelines to be announced by the banking sector and respond wisely.
Thorough pre-loan verification and conservative funding planning are the only ways to overcome the year-end loan cliff.
Frequently Asked Questions
=