Comparing out-of-pocket insurance to find the product that best suits you is the most reliable way to reduce the burden of soaring medical costs. I often witness people who, frustrated by sharply increased renewal premiums, impulsively cancel their existing contracts only to end up in tears. You need to carefully weigh whether the coverage scope of your past policy is good or if switching to a recently introduced product with a more reasonable structure would be more beneficial. In particular, making a hasty decision based solely on premium comparisons can lead to significant setbacks when you eventually need to file a claim for hospital expenses. In this article, we will take a detailed look at the characteristics of out-of-pocket insurance for different generations, the correct comparison methods, and hidden coverage benefits. We will guide you with specific examples to help you wisely manage your monthly fixed expenses.
=
Essential Guide to Comparing Out-of-Pocket Insurance: How to Choose the Right Plan for You
1. The History and Evolution of Out-of-Pocket Insurance by Generation
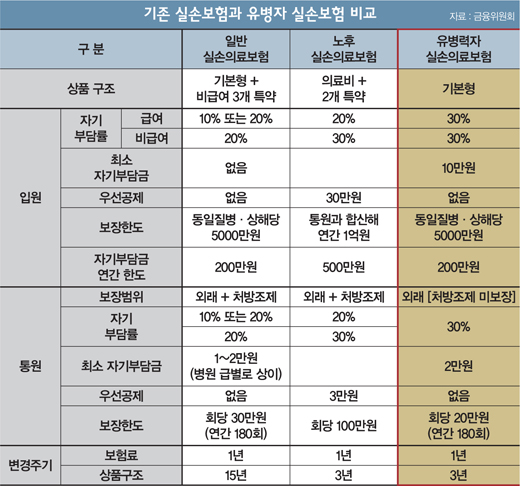
Out-of-pocket insurance has undergone remarkable changes from the first generation to the recent fifth generation, depending on when it was purchased. Past first and second-generation products offered little to no out-of-pocket costs for hospital bills, providing the best benefits for frequent hospital visitors. However, from the insurance companies’ perspective, this caused loss ratios to snowball. As a result, existing policyholders began to face increasingly severe renewal premium hikes that became difficult to bear over time.
To address these issues, the government and insurance companies have repeatedly reformed the system by increasing out-of-pocket costs and preventing excessive medical treatment. The fourth-generation products, which many people currently maintain, strictly separate covered and non-covered treatments and introduce a structure where premiums increase if non-covered treatments are used frequently. The latest products currently under discussion are trending toward strengthening coverage for severe illnesses while adjusting coverage for unnecessary minor outpatient treatments. Therefore, checking the conditions under which you originally enrolled is the starting point for comparing out-of-pocket insurance.
You must understand the differences in coverage structure and out-of-pocket costs based on the enrollment period to make a proper comparison.
2. What You Must Check Before Switching Haphazardly

You should absolutely avoid canceling your existing out-of-pocket insurance and switching to a new one simply because of a friend’s recommendation or because you feel the monthly payment is a waste. For example, Mr. Kim, a corporate employee who enrolled in out-of-pocket insurance ten years ago, recently switched to the latest product because he didn’t want to renew due to a significant premium increase. However, as he aged, he started visiting hospitals more often for various minor and major illnesses. The new product had much higher out-of-pocket costs, resulting in him paying more out of pocket for hospital bills than before.
When canceling an existing contract and moving to a new one, you must carefully check if any previously covered items have been removed. In particular, if you are older or have a medical history, you may face disadvantages such as rejection during the underwriting process or being unable to receive desired coverage when enrolling in a new product. Therefore, do not hastily cancel just because the premium is high; calmly compare the benefits you are currently enjoying with your expected frequency of hospital visits. Rather than relying solely on what insurance agents or comparison platforms say, you need the wisdom to objectively assess your own health status.
Haphazardly canceling just because premiums have risen can actually lead to significant losses in coverage.
3. How to Utilize Data Published by the Korea Insurance Association
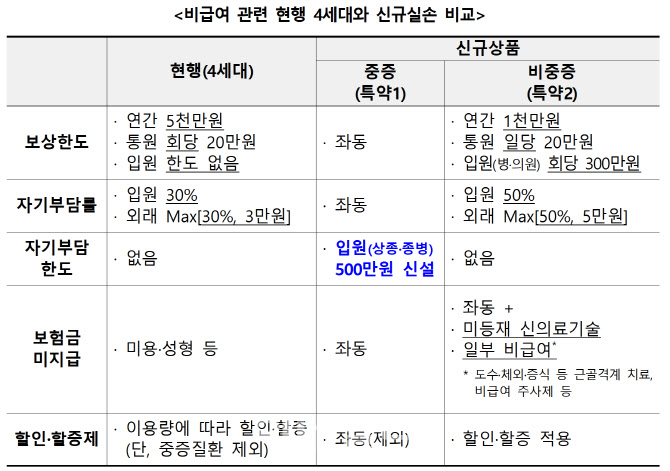
If you want to find the most favorable premium for yourself, you should actively utilize published data that allows you to compare products from various insurance companies at a glance. You don’t need to go around asking which company offers the best value among the countless products on the market; you can simply use the official comparison system. In fact, if you compare the fifth-generation out-of-pocket insurance premiums of major non-life insurance companies for a 40-year-old male with a healthy physique, you will see slight differences in the monthly payment amounts depending on the company.
Of course, choosing a company solely because the monthly premium is a few hundred won cheaper is not a wise approach. You should also consider the company’s financial soundness and the overall quality of service, such as how quickly claims are processed when you file for hospital expenses. Additionally, it is essential to carefully check if the additional riders available match your lifestyle. By comparing multiple products side-by-side based on these objective materials, you can naturally discover the truly valuable product that you need.
You must compare objective premiums and coverage details using official published data to make a rational choice.
4. How to File Out-of-Pocket Insurance Claims Easily Without Documents
Surprisingly, many people who diligently enroll in out-of-pocket insurance give up filing claims when hospital bills come up because the complex document preparation process is a hassle. Collecting items like medical receipts and detailed calculation statements to submit to the insurance company is cumbersome enough that office workers might have to break up their lunch break or take vacation days. However, recently, an environment is being created, centered around large hospitals, where documents can be transmitted directly to insurance companies via computer systems without issuing paper copies.
Although this electronic claim system has not yet fully taken root in the majority of local clinics or pharmacies, the number of institutions adopting it is gradually increasing. If you can reduce the trouble of receiving documents at the hospital counter, consumers’ time and effort can be drastically reduced. Therefore, when comparing out-of-pocket insurance products, you should not look only at the premium but also consider how well the smartphone app or simple claim system is established as an important selection criterion. Small differences can lead to a huge gap in convenience over time.
It is important to check if the product supports a simple claim system that minimizes the hassle of submitting documents.
5. Tips for Managing Insurance to Fit Your Lifestyle
Linked coverage from out-of-pocket insurance is a great help when going on overseas trips during holidays like Chuseok or when unexpected accidents occur in daily life. If you are going abroad using a long holiday, you should carefully check the detailed coverage of travel insurance. At this time, it is also good to check for any overlapping coverage with your existing out-of-pocket insurance. Rather than blindly enrolling in new travel insurance, examining how your existing out-of-pocket insurance or family daily life liability riders are structured can prevent unnecessary expenses.
Old insurance policies maintained for a long time may not fit the modern, changing medical environment, so it is advisable to get a professional diagnosis periodically. You need to compare and organize your overall insurance portfolio at a glance to ensure there are no coverage gaps with auto insurance or driver’s insurance. You should restructure your insurance according to your age, health status, and expected future medical expenses to avoid burdening your household economy. Rather than blindly following products recommended by others, you need to make an effort to accurately understand your own lifestyle and design a customized plan.
You must manage comprehensively by linking various situations in daily life with the coverage scope of your existing insurance.
6. Final Recommendations for Wise Out-of-Pocket Insurance Comparison
Ultimately, successful out-of-pocket insurance comparison is not a competition to find the cheapest price, but a process of weaving a solid medical safety net that fits your body best. Since this insurance is enrolled to prevent a medical cost bomb, you must not end up in a situation where you cannot receive coverage when you actually get seriously ill just to save a few cents in the short term. You must pay continuous attention to how your product changes as medical technology advances and systems change.
Please do not be misled by hearsay or sensational advertising; take time to calmly reflect on your health history and financial situation. The small action of accessing the publication site right now and checking the premiums suitable for your age and gender with your own eyes brings great peace of mind for the future. We sincerely hope that through wise information gathering and careful comparison, you can protect your valuable assets and always enjoy a healthy life.
You must wisely prepare for future medical cost risks through thorough comparison and proactive management.
Frequently Asked Questions
=