If you keep a lump sum in your Retirement Pension IRP account, you must strictly manage your annual withdrawals to stay under 15 million won to avoid a tax bomb later on. Mr. Kim, an office worker, recently transferred his severance pay to an Individual Retirement Pension account and, without giving it much thought, withdrew large amounts every month. He was shocked to discover later that he would have to pay significantly higher taxes than expected. Many people open these accounts solely for the tax deduction benefits but do not fully understand the tax rate structure applied when they withdraw funds after retirement. In this article, we will thoroughly examine the essential tax criteria and smart fund withdrawal strategies for utilizing the Retirement Pension IRP. Only by properly understanding and preparing for the system can you prevent your hard-earned retirement assets from being squandered on taxes. Let us carefully go through the details one by one to build a solid foundation for a secure retirement plan.
=
How to Avoid the Retirement Pension IRP Tax Bomb and a Summary of 2026 Tax-Saving Strategies
1. Basic Concepts and Understanding of the Retirement Pension IRP Account

The Individual Retirement Pension system is a useful financial instrument designed to allow employees to accumulate their severance pay in an account in their own name and manage it safely until retirement. If you simply deposit your valuable severance pay into a regular checking account, it is easy to fall into the temptation of spending it immediately. However, by utilizing this system, you can significantly reduce your tax burden while steadily building your retirement assets. Notably, this account is not limited to those who have left their jobs; employed individuals and self-employed persons with income can also make additional contributions at any time to enjoy tax deduction benefits. Because you receive a tax refund based on a certain percentage of your annual contributions, it has long been established as an essential tax-saving tool among office workers. Recently, financial institutions such as banks and securities firms have improved accessibility by running various events to attract subscribers or introducing augmented reality technology to diagnose investment tendencies. Since you can allocate funds across various products like deposits or funds according to your investment style, you should actively manage the account rather than leaving it neglected.
The Retirement Pension IRP is an essential retirement asset management account that allows you to secure both severance pay storage and additional tax deductions.
2. Retirement Pension IRP Tax Deduction Benefits and Limits

As the year-end tax settlement season approaches every year, the biggest concern for office workers is undoubtedly how much tax they can get back. You can receive tax deduction benefits on contributions made to pension savings and individual retirement pensions combined, up to a maximum of 9 million won annually. Depending on your income level, you can receive a refund ranging from 13.2% to a maximum of 16.5%. For example, if you max out the annual limit of 9 million won and qualify for the highest deduction rate, you can enjoy the joy of receiving a cash tax refund of several hundred thousand won during your year-end settlement. However, it is not always good to contribute as much as possible; you need the wisdom to carefully consider your income level and annual savings capacity before deciding on the contribution amount. Occasionally, people lock in funds solely for the tax deduction benefits and find themselves in a difficult situation when they urgently need cash, so caution is advised. Financial institutions operate various counseling channels to help customers understand these benefits easily, so it is best to utilize them actively.
Filling the annual maximum contribution limit of 9 million won allows you to receive a substantial tax refund during your year-end settlement.
3. The Secret of the 15 Million Won Annual Limit and Preventing a Tax Bomb

When withdrawing money from your Retirement Pension IRP after retirement, special caution is required because the tax calculation method changes completely if your total annual withdrawals exceed 15 million won. If your annual withdrawals are 15 million won or less, a low-rate separate taxation applies, with pension income tax rates being very low, ranging from 3.3% to 5.5%. However, the moment you exceed this limit by even 1 won, you face the burden of choosing between comprehensive income tax aggregation or 16.5% separate taxation on the entire amount received, not just the excess. There are many retirees around us who regret receiving a bomb-like tax notice after carelessly withdrawing large amounts monthly to comfortably fund their retirement living expenses. Therefore, if you have a large total asset to withdraw, it is much more advantageous to carefully calculate your monthly withdrawals to ensure they do not exceed 15 million won annually by spreading the withdrawals over a longer period. You must keep in mind that simply flexibly adjusting the withdrawal period can significantly reduce the regrettable amount lost to taxes.
If annual withdrawals exceed 15 million won, the tax rate spikes sharply, so you must adjust the withdrawal period to maintain separate taxation.
4. Differences Between Lump-Sum and Pension Receipt of Severance Pay
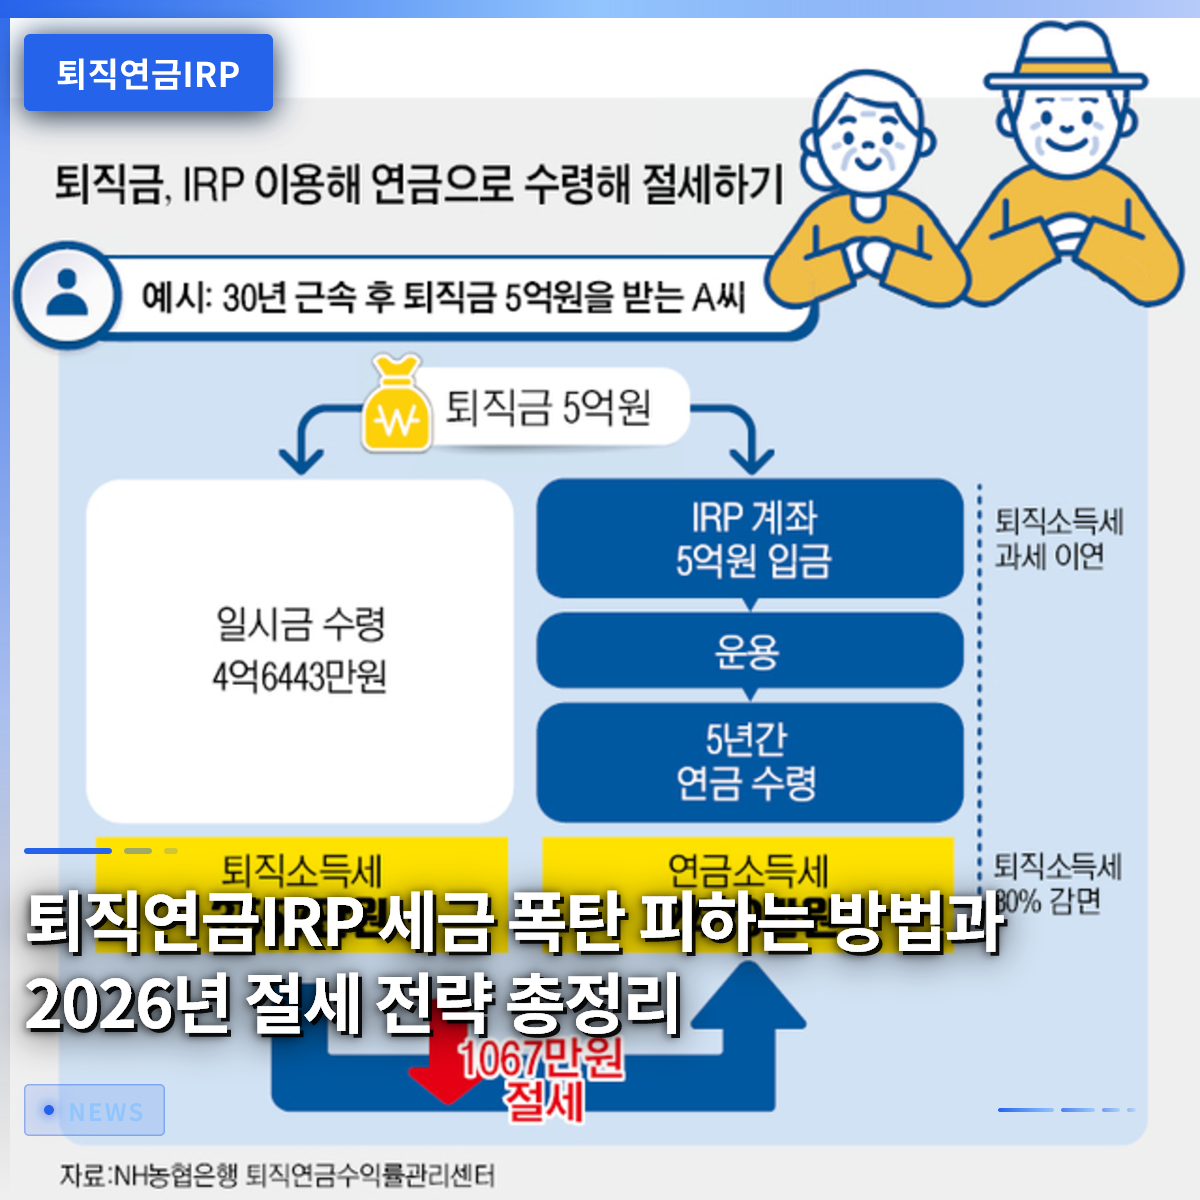
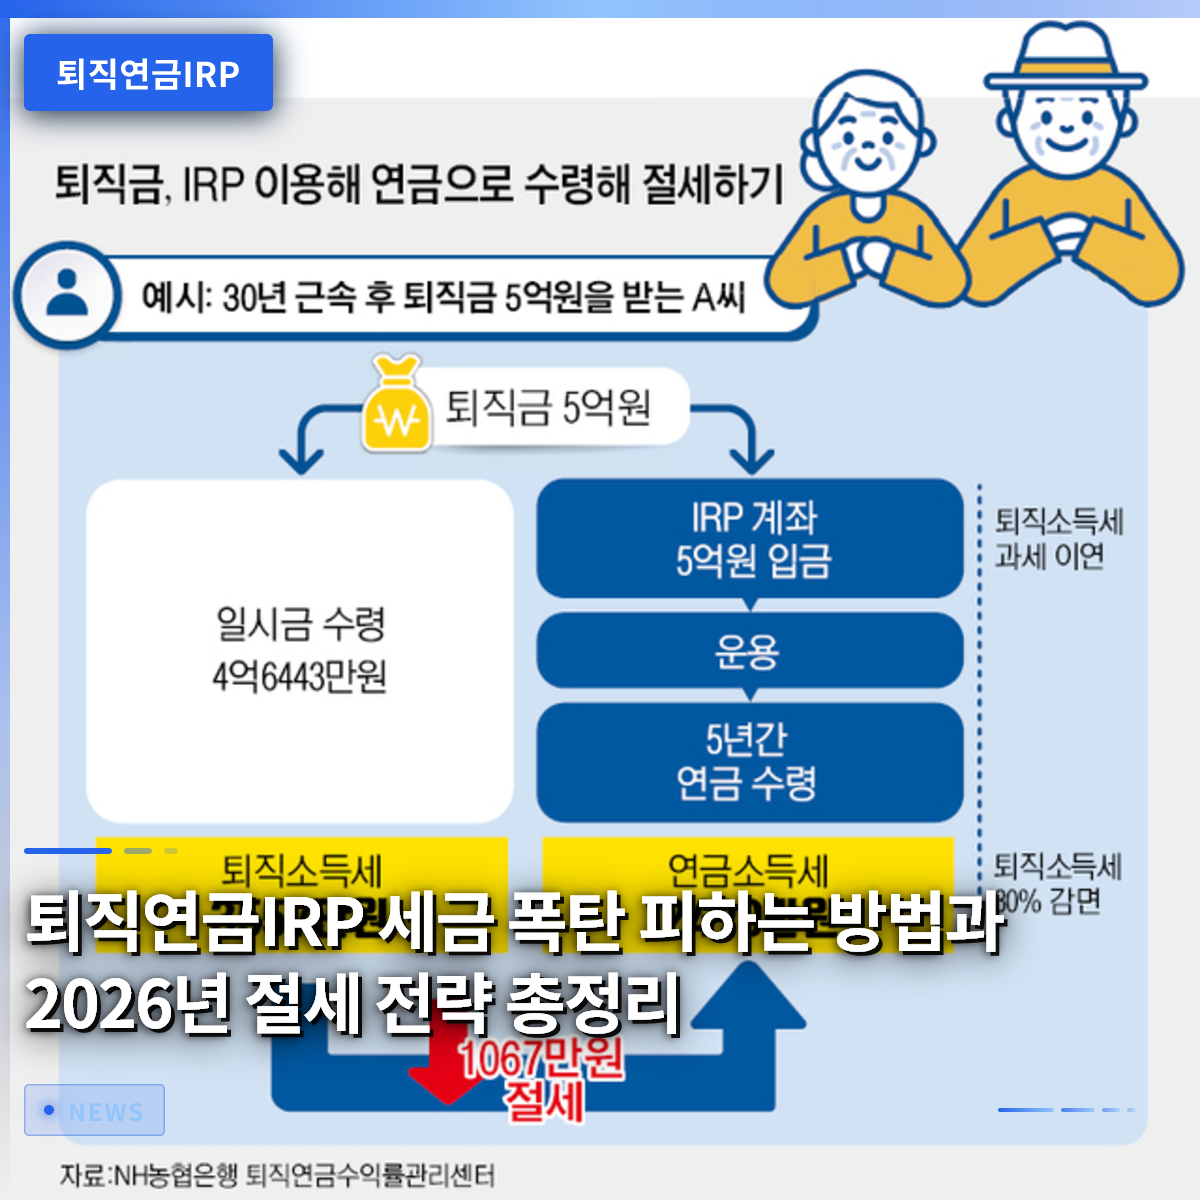
If you withdraw your entire severance pay as a lump sum instead of receiving it in the form of a pension upon leaving your job, you will miss out on significant tax reduction benefits. According to the law, if you transfer your severance pay to an IRP account and receive it as a pension, you are eligible for a substantial tax reduction of 30% to a maximum of 40% on severance income tax. However, if you withdraw the entire amount as a lump sum simply because you are over 55 years old, these reduction benefits disappear instantly, and you must pay the full amount of tax originally due. Withdrawing a lump sum just because you need a large amount of cash immediately can be a very foolish choice from a tax perspective. In reality, many retirees do not know about this system well and frequently regret it later, kicking themselves for paying more taxes than necessary. Even if it is slightly more troublesome, choosing to keep the funds in the account and receive them in monthly installments is much more beneficial in the long run.
Receiving severance pay as a lump sum eliminates income tax reduction benefits, so it is advantageous to receive it in the form of a pension.
5. Early Withdrawal Conditions and Exceptional Situations to Avoid
Life inevitably brings crisis situations where you suddenly need a large amount of money, and many people wonder if they can withdraw funds from their Retirement Pension IRP in the middle. Unfortunately, early withdrawal from an Individual Retirement Pension account is strictly prohibited for general reasons and is only permitted in specific situations defined by law, such as purchasing a house or securing a deposit for a tenant without owning a home, bankruptcy declaration, or natural disasters. Withdrawal conditions may vary depending on the type of pension, such as Defined Benefit (DB) or Defined Contribution (DC) plans managed by the company, so you must accurately understand your enrollment type. If you want to withdraw money without a special reason, you must terminate the account entirely; in this case, you must not only return all the tax deduction benefits received but also pay miscellaneous income tax. Therefore, you should plan your long-term funds with the mindset that once money is put into this account, it should never be touched until retirement. It is wise to prepare emergency funds separately through other means such as regular deposits or a Comprehensive Asset Management Account (CMA).
The Retirement Pension IRP has very strict early withdrawal conditions, and unauthorized termination requires the return of all tax benefits.
6. A Wise Retirement Asset Management Plan for 2026 and Beyond
To meet a stable retirement in the midst of rapidly changing tax laws and financial environments, you must establish a thorough and meticulous asset management strategy starting now. You should actively utilize AI-based asset checks and various tax-saving guides provided by the financial sector to develop the habit of regularly monitoring the return rates and tax status of your account. Whether you are a civil servant or a general office worker, as retirement approaches, your pension income may decrease or your tax burden may increase, making multi-faceted preparation essential. You need a three-dimensional retirement design that involves checking your expected National Pension receipt amount in advance and supplementing any shortfall through personal pensions, housing pensions, and the Retirement Pension IRP. It is most important to take action now rather than procrastinating out of laziness; open your financial accounts and carefully check your contribution limits and expected pension amounts. Do not forget that a peaceful and abundant retirement does not come by chance but is the result of meticulous tax-saving investments and consistent attention during your younger years.
To achieve a successful retirement, you must build a diversified pension portfolio aligned with changing tax laws and monitor it consistently.
Frequently Asked Questions
=