Using the Four Major Social Insurance Calculator allows you to accurately predict the deductions for National Pension, Health Insurance, and other mandatory contributions that often leave you puzzled every time you receive your monthly payslip. We have all likely had the experience of being shocked to find that the amount deposited into our bank account is significantly less than expected, despite working hard all month. This is because a pre-tax salary of 3 million won does not mean that exact amount will land in your account. Companies are legally required to deduct various taxes, including National Pension and Health Insurance, before payment, resulting in a lower net amount. While performing these complex calculations manually can be a headache, using a tool allows you to find out your true take-home pay in just a few seconds. In this article, we will examine the meaning of deduction items and how to effectively use these tools in detail.
=
How to Use the Four Major Social Insurance Calculator: Accurately Check Your Net Salary, Taxes, and Deductions
1. What is the Four Major Social Insurance Calculator?
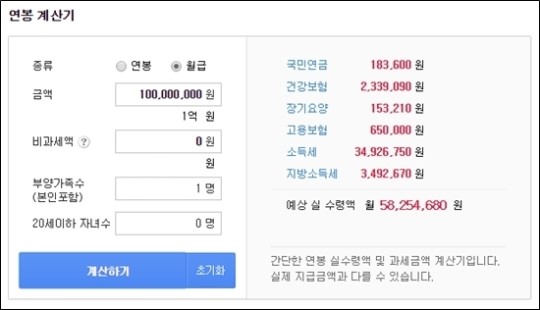
The Four Major Social Insurance Calculator is a convenient tool that automatically calculates the four mandatory insurance premiums and taxes deducted from an employee’s salary. Anyone who works for a company will notice that a certain percentage of their monthly salary is naturally deducted. By entering your monthly salary or annual income into this tool, you can calculate the National Pension, Health Insurance, Long-term Care Insurance, and Employment Insurance all at once. Since it also reflects estimated income tax and local income tax, you can clearly see the difference between your gross and net pay. The reason many office workers frequently use this tool is that it quickly reflects the changing rates each year and any fluctuations in their salary. Manually calculating by multiplying ratios in your head is prone to errors and time-consuming, but using a tool provides results with just a few inputs. For example, if you are envious of a friend who received a raise and wonder how much you would actually take home if you earned the same amount, this tool is very useful.
The Four Major Social Insurance Calculator is a tool that automatically calculates the four insurance premiums and taxes deducted from your salary to tell you your actual net pay.
2. The Deduction Structure of National Pension and Health Insurance

The National Pension is a state-operated system to prepare for old age, where the employer and the employee each bear half of the cost based on a certain percentage of monthly income. According to current standards, the National Pension premium rate is steadily deducted from monthly salaries based on established criteria and is returned in the form of a pension after retirement. Health Insurance is a crucial social security system that helps us use hospitals and pharmacies at affordable costs. The Health Insurance premium is also shared equally between the employee and the employer, and the Long-term Care Insurance premium, which is calculated based on the Health Insurance premium amount, is deducted along with it. Many people sigh when looking at their payslips, wondering why such large amounts are being deducted. However, these costs serve as a safety net, providing a sturdy support for you and your family in the future when you or your loved ones may fall ill or grow old. Although it may feel like a waste of money every month, these are amounts that are eventually returned or provide benefits, so it is best to understand the structure accurately. Using a tool to check exactly how much is deducted from your account each month can greatly help in planning your asset management.
National Pension and Health Insurance are essential deduction items where the cost is shared between the employee and the employer to prepare for old age and medical expenses.
3. Understanding Employment Insurance and Income Tax

Employment Insurance is a sturdy shield for workers that helps them receive unemployment benefits if they suddenly lose their job and provides opportunities for vocational training. The Employment Insurance premium is also automatically deducted from monthly salaries at a certain rate, with the worker and the employer each bearing a designated percentage of the responsibility. Income tax and local income tax are taxes paid to the state and the local government where you reside, and they vary slightly depending on the number of dependents an individual has. The more dependents you have, the lower the tax burden, so even if everyone earns the same 3 million won, the actual amount deposited into their accounts will differ slightly. You may have been puzzled at times when a friend had the exact same annual salary as you, yet your net pay was either higher or lower. This is due to differences in the number of dependents registered on your resident registration or eligibility for tax deductions. By entering these specific conditions into the tool, you can calculate an accurate estimated deduction tailored to you. Understanding the principles behind how taxes and insurance premiums are structured will make you feel much more at ease when reviewing your payslip.
Employment Insurance is for unemployment benefits, while income tax is levied differently for each individual based on factors such as the number of dependents.
4. Changing Rates Each Year and the Need for a Calculator
The rates for deduction items such as National Pension and Health Insurance can change slightly each year due to inflation or government policies. For example, if the rate for a specific insurance increases by a few percent compared to last year, your net pay will inevitably decrease slightly. Relying on outdated standards or old memories to make rough calculations can lead to discrepancies between the estimated and actual amounts, causing confusion. Therefore, it is very important to use a reliable tool that immediately reflects the latest standards and updated rates. Every time a new year begins and you negotiate a new salary, you likely want to calculate in advance exactly how much will be deposited into your account next year. In such cases, opening a tool updated to the latest version and entering your expected salary allows you to plan your future savings. It is also crucial to know your exact monthly net pay when preparing for a real estate contract or looking into loans, as it helps determine whether you can afford the monthly principal and interest payments. Keeping up with changing standards is the first step toward smart asset management.
You should use a calculator updated with the latest standards to accurately reflect the changing insurance premium rates each year.
5. Reasons Why Net Pay May Differ from Estimates
You may have been puzzled when the estimated amount from an online tool differed slightly from the amount on your actual company payslip. The biggest reason for this discrepancy is that non-taxable salary items or company-specific allowances, such as meal allowances, vary from person to person. Non-taxable allowances like meal subsidies or driving allowances are not subject to tax, so how these are applied can change your net pay. Additionally, if your company provides group accident insurance or deducts interest on internal loans, these can also cause differences. Rather than simply entering your gross annual or monthly salary and trusting the result, it is better to understand the nature of the allowances you receive. If your company provides meal allowances separately up to the non-taxable limit, the actual amount deposited into your account may be slightly higher than expected. Conversely, if there are additional deductions such as union dues or welfare association fees, the amount will decrease accordingly. By keeping these detailed factors in mind when using the tool, you can significantly reduce the error between the estimate and the actual amount.
Differences between the tool’s estimate and your actual salary can occur due to non-taxable allowances or additional deduction items based on company regulations.
6. Tips for Smart Asset Management
Accurately understanding the flow of taxes and insurance premiums deducted from your monthly income is the most basic yet important process in financial management. Instead of simply spending your salary as it comes in, you should calculate the outgoing funds in advance and plan your savings and spending within the remaining amount. If you have goals to grow your assets and save a lump sum, try to make it a habit to check your net pay every time your annual salary increases. You must block unnecessary outflows and accurately grasp the actual cash flow remaining in your account to prepare solidly for the future. As various tax law changes and policy revisions are expected to continue, the ability to find relevant information on your own will become increasingly important. Based on what you have learned today, try calculating your expected salary and setting new savings plans for the upcoming period. Small concerns and actions will eventually form a sturdy foundation that protects our valuable assets and creates a more abundant retirement. Let’s use tools to easily and clearly resolve the secrets of the taxes hidden in your salary, which may have seemed complex and difficult.
Accurately grasping your net pay and planning your savings and spending is the core of successful asset management.
Frequently Asked Questions
=