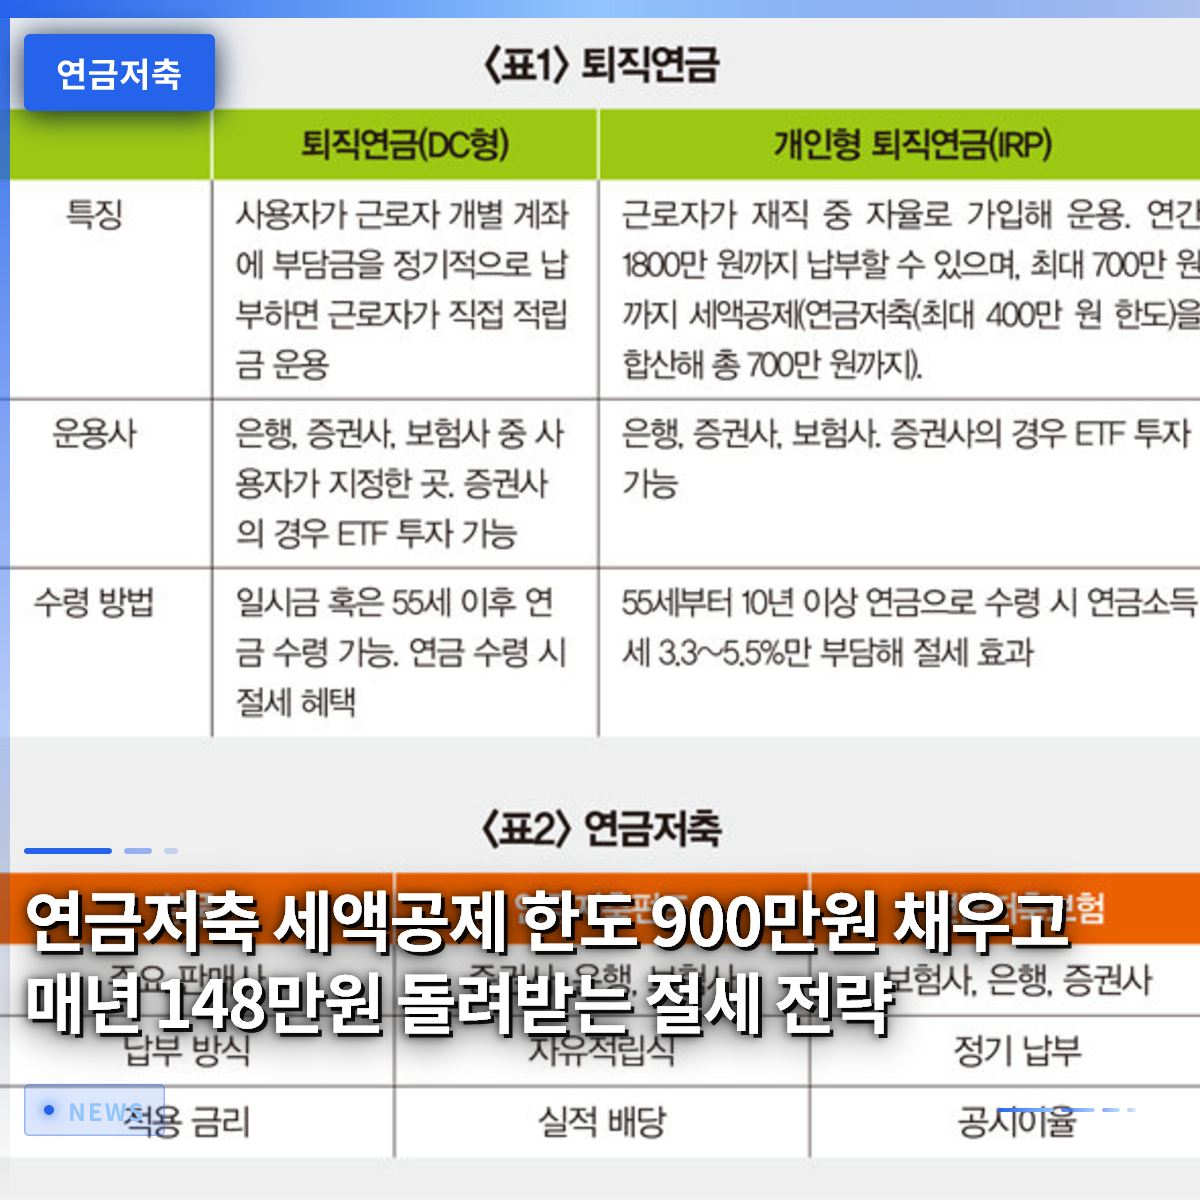
If you feel like you’re paying more in taxes every year during your year-end tax settlement, you must utilize pension savings accounts and individual retirement pension accounts to contribute up to 9 million won and secure the 1.48 million won tax credit benefit. Mr. Kim, an office worker, was disappointed by the smaller-than-expected refund from last year’s year-end settlement, but this year he has planned to change his pension account strategy to significantly reduce his tax burden. In reality, it is easy to find cases where people waste money every year by failing to fully utilize the tax credit limit. In this article, we will cover everything from specific methods for setting contribution limits that busy office workers can easily follow to how to utilize US dividend investments. With a little care in managing your accounts, you can achieve both retirement preparation and immediate tax savings. The small changes you start now will completely transform your bank account balance in a few years.
=
Tax-Saving Strategy: Maxing Out the 9 Million Won Pension Contribution Limit to Get 1.48 Million Won Back Annually
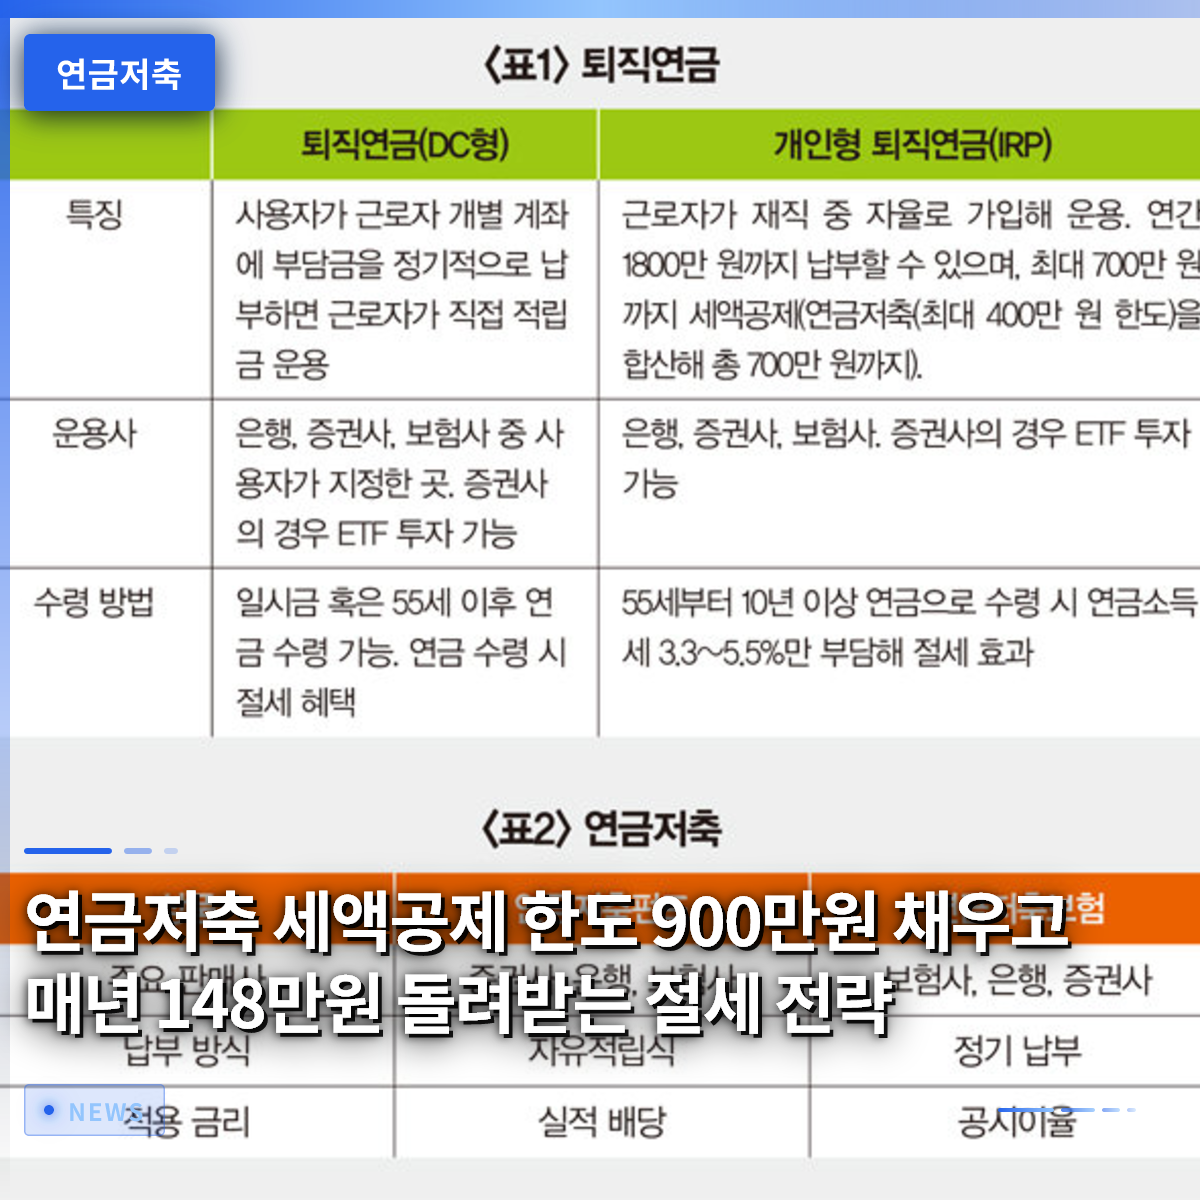
1. Everything About the Tax Credit Limits for Pension Savings and Individual Retirement Pensions

A pension savings account alone offers a tax credit contribution limit of up to 6 million won, but when combined with an individual retirement pension, the total limit increases to 9 million won. If your total annual income is 55 million won or less, a 16.5% credit rate applies, allowing you to receive a maximum refund of 1,485,000 won if you fully utilize the 9 million won limit. Even if your total annual income exceeds 55 million won, a 13.2% credit rate applies, resulting in a substantial refund of 1,188,000 won. Choosing to split your surplus funds and contribute steadily each month reduces the burden of saving a large lump sum while allowing you to enjoy significant benefits at the time of year-end settlement. Mr. Park, an office worker, sets up an automatic transfer of 750,000 won each month, naturally reaching the maximum credit limit without the stress of scrambling for funds at year-end. Understanding the structure of the system accurately and setting your monthly contribution amount according to your income bracket is the first step toward successful asset management. Pension accounts are not just savings for retirement; they are the most powerful state-recognized tax-saving tool that helps save on current income tax. Therefore, it is wise to regularly check your expected annual salary and contribution amount from the beginning of each year to ensure you meet the limit.
By contributing up to 9 million won in total to pension savings and individual retirement pensions, you can receive a tax refund of up to 1.48 million won depending on your income bracket.
2. Tax Deferral Effects Through Investing in US Dividend Stocks and ETFs
When you buy US dividend growth stocks or index-tracking ETFs within a pension savings account, you can reinvest the dividends without immediately paying dividend income tax. If you invested in a regular account, 15.4% tax would be deducted every time dividends were received, but pension accounts defer this tax, maximizing the effect of compound interest. In fact, investors who have invested long-term in products tracking the S&P 500 index feel the tangible growth of their assets as quarterly distributions accumulate in their accounts. If you are worried about the high volatility of tech stocks, choosing US value stocks or stable dividend-focused products is also a good alternative. Since taxes are paid at a lower rate when you withdraw the pension later, long-term investing creates an overwhelmingly higher return compared to regular stock accounts. Mr. Lee, an office worker, has been buying US stock-based products monthly through his pension account for several years and has now established a system where dividends are automatically reinvested. Watching your assets grow on their own until retirement is one of the great pleasures of investing for office workers. If you want to fully enjoy the magic of compound interest, it is best to open your brokerage app today and review the investment stocks in your pension account.
Managing stocks within a pension account allows you to defer dividend income tax, maximizing the effect of compound interest.
3. Strategy for Utilizing Pension Savings Wrap Products with Expert Management

If you are an investor who lacks the time to pick stocks and analyze market conditions, you can actively utilize the discretionary asset allocation products recently introduced by brokerage firms. Experts affiliated with the brokerage firm adjust the portfolio according to market conditions on behalf of the client and manage assets safely, which can revitalize neglected accounts. For example, related products recently launched by brokerage firms are well-received for pursuing both stable defense and returns in volatile markets. This is a very useful option for office workers who are intimidated by the idea of studying and trading stocks themselves or are too busy with their main jobs to check their accounts. However, since fee structures and performance vary by product, you must carefully compare past returns and costs before signing up. Rather than signing up based solely on recommendations from others, you should first determine whether your investment style is stable or aggressive and choose a product that fits it to avoid regret. The biggest advantage of this method is that you can fully enjoy tax credit benefits while receiving expert management.
If selecting stocks is difficult, you can manage your assets comfortably through discretionary products where pension experts handle asset allocation on your behalf.
4. The Annual 15 Million Won Withdrawal Rule to Watch Out For When Receiving Pensions
When you start receiving your pension after retirement, if your private pension income exceeds 15 million won annually, your tax burden may increase, so a strategy to adjust the amount received is necessary. If the annual amount received is 15 million won or less, a low pension income tax rate of 3.3% to 5.5% applies, but if it exceeds this, comprehensive taxation or higher separate taxation applies. Choosing to receive approximately 1.25 million won per month by splitting the amount is a wise way to avoid a tax bomb. Mr. Kim, a retiree, chose to receive 1.2 million won per month rather than withdrawing all his money at once after retirement, minimizing his tax burden while securing stable living expenses. Many people rush to deposit money just for the tax credit benefits and are later shocked when they receive their pension because they did not know the tax system. Therefore, a long-term perspective that calculates not only the tax savings when contributing but also the tax rate when withdrawing is essential. When designing your cash flow after retirement, you should also consider coordinating the timing of receiving your National Pension to be perfect.
To lower your tax burden, you should split your withdrawals so that your annual pension income after retirement does not exceed 15 million won.
5. Tips for Transferring Retirement Pension Accounts and Choosing Principal-and-Interest Guaranteed Products
If you are not satisfied with the return of your existing retirement pension product or want to switch to a financial institution with better terms, you can easily switch using the contract transfer system. Since the types of deposit and bond products offered vary by bank or brokerage firm, you should check in advance if they offer the government bonds or high-quality fixed deposits you want. Even for principal-and-interest guaranteed products, interest rates vary slightly by financial institution, so it is beneficial to shop around for slightly more favorable conditions. If you leave your retirement pension account neglected, it can be locked at low interest rates that cannot keep up with inflation, so regular checks are essential. Mr. Jeong, an office worker, recently transferred his account to a brokerage firm, allowing him to invest in a wider variety of government bond products, and his returns have improved noticeably. Without complex paperwork, the transfer is completed simply by visiting either the existing or the new financial institution, or by applying non-face-to-face. If you seek stability but want returns higher than market rates, you should seriously consider a portfolio centered on government bonds.
You can switch retirement pensions with low returns to those with more favorable interest rates or government bond products using the contract transfer system.
6. Fund Management Ahead of Holidays and Future Outlook for Pension Asset Management
As the Chuseok holiday approaches and various support measures and funds are released by the financial sector, you should take this time to calmly review your overall asset status. Just as housing pensions may be paid out early or various traditional market support activities continue around the holidays, it is good to clearly manage your personal financial schedule. To perfectly prepare for the upcoming year-end settlement, you should check your remaining pension savings contribution limit once more and fill in any shortfall. The importance of tax benefits will continue to grow, and the quality of life between those who prepare for retirement themselves and those who do not will diverge significantly. The habit of setting aside a portion of your monthly salary and steadily accumulating it in a pension account is the most certain and safe investment for your future self. It is most important to have the attitude of setting a confident contribution plan based on your own judgment, rather than being swayed by rumors, and executing it consistently. I recommend opening your brokerage app today to check your pension account balance and whether you have met this year’s credit limit.
Take advantage of the holiday period to review your cash flow and fill up your year-end settlement limit in advance to build a solid retirement asset.
Frequently Asked Questions
=