To break free from a life of dependence on your children after retirement and build a true safety net for your later years, you must start preparing a personal pension immediately. It is practically impossible for children to send their parents 2 million won in pocket money every month during holidays, making a self-created pension system the only viable solution. While many people feel overwhelmed as retirement approaches, those who prepared in advance are enjoying a comfortable living expense. In this article, we will discuss specific methods to maximize retirement funds using personal pensions, in addition to the National Pension and retirement pensions. We will carefully examine everything from tax deduction benefits to specific asset allocation strategies. We have compiled only the core content so that those just beginning to worry about their retirement can easily follow along.
=
The Secret to Contributing 240 Million Won and Receiving 800 Million Won in Personal Pensions: A Strategy for Retirement Preparation
1. Building a Retirement Safety Net with Your Own Power, More Reliable Than Children’s Pocket Money
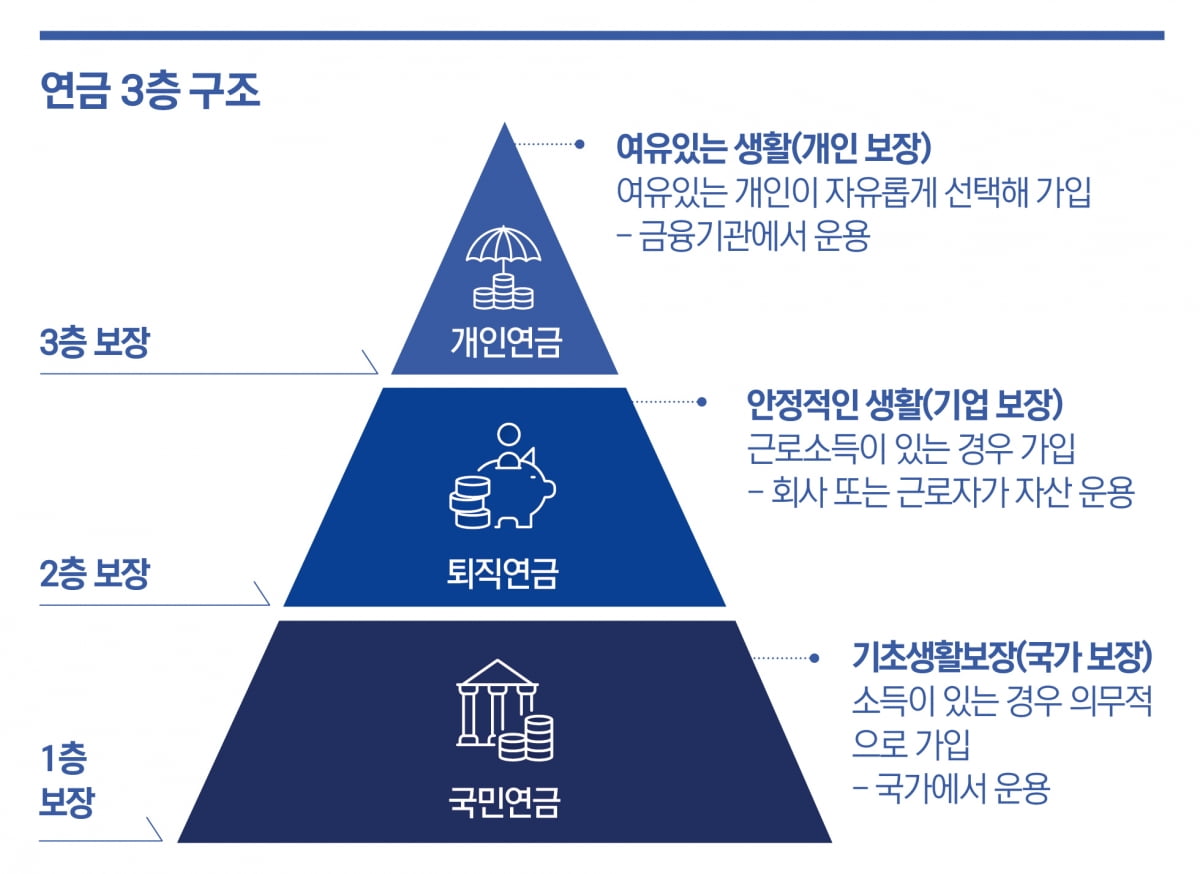
The living expenses we typically anticipate after retirement are often far from being covered by public pensions alone. Without a fixed monthly cash flow, even meeting basic needs for food, clothing, and shelter can become a struggle. In the past, it was taken for granted that children would support their parents, but for today’s generation, the era is one where they are busy just taking care of themselves. Therefore, the habit of accumulating and growing assets on one’s own has become more important than ever. Assets consistently accumulated through regular contributions will ultimately become the most reliable “filial child” in retirement. It is heartbreaking to see friends around us who expect pocket money from their children only to be disappointed. On the other hand, those who have consistently filled their pension accounts are enjoying leisure and travel. In reality, the basic goal for office workers in their 50s regarding retirement cash flow is to generate 2.5 million won per month by combining the National Pension, retirement pension, and personal pension. Only when this amount is secured can you stably cover more than half of your necessary living expenses. Even now, you should set aside a fixed amount each month with the mindset of investing in your future self.
Relying on children’s pocket money for retirement is risky; you must combine the National Pension, retirement pension, and personal pension to create your own cash flow of 2.5 million won per month.
2. The Reality Behind the Secret of Contributing 240 Million Won and Receiving Over 800 Million Won in Personal Pensions
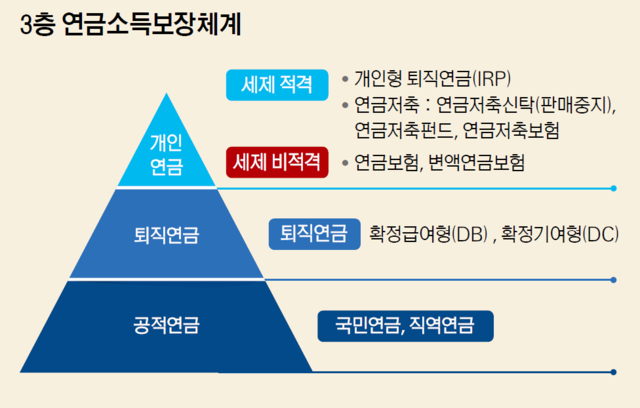
Many people wonder how a small principal can turn into a large sum of money. Combining the effect of compound interest over a long period with stable investment in equity-based assets leads to surprising asset growth. For example, one can take the approach of regularly investing in index-tracking products and reinvesting dividends. If you patiently build up your principal over a decade or more, you can achieve valuation profits several times your principal. In fact, looking at the records of people who consistently settle their pensions, you can easily witness the process of principal growing from tens of millions to hundreds of millions of won. This process does not happen overnight and requires a thorough long-term investment mindset. The key is to mechanically continue buying on a set date each month, even if the stock market fluctuates in the middle. You must maintain your own portfolio without being swayed by asset management companies’ internal controls or market noise. By splitting a considerable amount of 240 million won over a long period, you can enjoy both tax benefits and capital gains. Ultimately, at the time of retirement, this grows into a massive asset of over 800 million won, providing a solid support for your later years.
By utilizing long-term regular investment and the effect of compound interest, you can grow a principal contribution of 240 million won into a massive retirement fund of over 800 million won.
3. The Essential Gateway for Severance Pay Tax Savings: How to Use IRP Accounts
If you are preparing to change jobs or retire, you must absolutely not receive your severance pay directly into a regular bank account. You must receive your severance pay through an Individual Retirement Pension (IRP) account to avoid a tax bomb and safely grow your assets. If you receive your precious severance pay in a general account when leaving a company, taxes are deducted immediately, resulting in a loss. On the other hand, if you transfer it to the relevant account and receive it as a pension, you can pay taxes in very small installments, like a light drizzle, or significantly reduce the tax burden. Practical experts strongly advise that if you want to save on taxes, you must unconditionally direct your severance pay to the relevant account. Within this account, you can pool your severance pay with additional personal contributions and manage it yourself. You can diversify investments in various financial products to increase returns while also fully taking advantage of tax deduction benefits. This is why office workers desperately fill their pension accounts every year-end tax settlement season. Saving on taxes is the same as generating profit, so this system should be actively utilized.
Severance pay must be received into an IRP account to save on taxes and safely link it as a pension asset.
4. Maximizing Tax Deduction Limits and Pension Savings Fund Combination Strategies
Every year during the year-end tax settlement, the biggest topic for office workers is undoubtedly tax deduction benefits. By combining pension savings and IRP contributions, you can maximize the tax deduction limit and receive the full refund. Since a certain percentage of the contributed amount is refunded at year-end, it is considered the best financial tool for office workers. If you gradually increase your savings amount while taking it easy each month, you will eventually find an account filled to the deduction limit. It is the trend to directly purchase high-quality index-tracking products from a pension savings fund account in line with the stock market’s flow. It is difficult to keep up with inflation by burying money only in safe bank products, so using a securities account is more advantageous. Investing in assets that consistently pay dividends allows you to enjoy the fun of generating monthly cash flow. The dividends collected this way are combined back into the principal, creating a virtuous cycle that triggers a larger compound interest effect. Accumulating and practicing this financial knowledge from a young age is the only way to overcome the polarization of retirement.
You should appropriately combine pension savings funds and IRP to fill the annual tax deduction limit and reinvest dividends.
5. Taxation Standards for Private Pensions Exceeding 15 Million Won and How to Handle Them
Many people fear hitting a tax bomb when they finally try to withdraw and use the pension they have diligently saved. Rumors that the tax burden increases if the annual receipt amount exceeds a certain amount make them hesitate to withdraw. However, pension accounts are not taxed based on the total balance, but rather based on the source of the funds (the “label” of the money) according to tax law standards. The taxation method varies significantly depending on the source of contribution and whether a tax deduction was received. Based on expert advice, you must formulate a strategy to disperse the timing of withdrawals or adjust the receipt amount. The trick is to extend the period so that the monthly private pension receipt does not exceed the annual standard. Choosing to receive the funds in installments over several years rather than withdrawing a lump sum at once can significantly reduce the tax burden. Wisdom is needed to understand the detailed standards of tax law in advance and reflect them in retirement planning. Preventing unnecessary expenditures like taxes is the most certain shield for protecting retirement assets.
Understand the taxation standards when the annual receipt amount exceeds 15 million won, and disperse the receipt period to minimize the tax burden.
6. Practical Recommendations and Outlook for a Successful Retirement
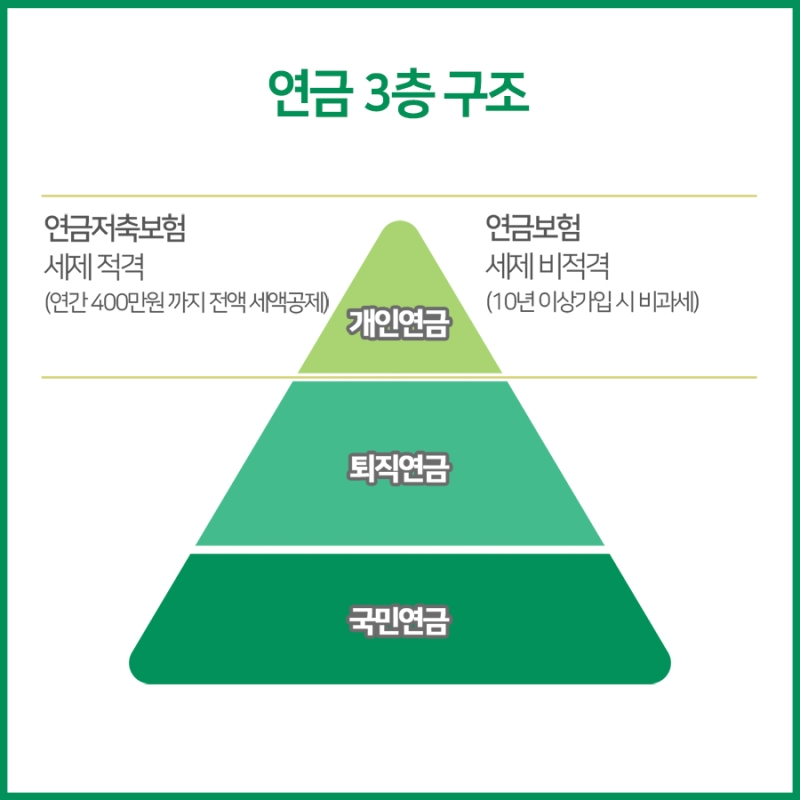
As we have seen so far, a prosperous retirement is not something that comes by chance but is the result of thorough preparation. If you rely on your children or vaguely trust only the state’s public pension, it will be difficult to avoid economic hardship after retirement. You must save the money for a cup of coffee each month or reduce unnecessary consumption to fuel your pension account. As the saying goes, “It is never too late to start,” you need the courage to open an account and make your first contribution today. The future financial environment will flow favorably only for those who protect and grow their own assets. Listening to the advice of retirement experts and diligently continuing regular contributions each month is the best weapon. Please complete a multi-layered pension system that secures both the stability of the National Pension and the profitability of personal pensions. Imagine yourself smiling as you see the solid cash flow hitting your account every month after retirement. The small practice of starting right now will completely change the quality of your life in your later years.
Retirement preparation is a task that cannot be postponed; opening a pension account now and making consistent contributions determines a successful retirement.
Frequently Asked Questions
=