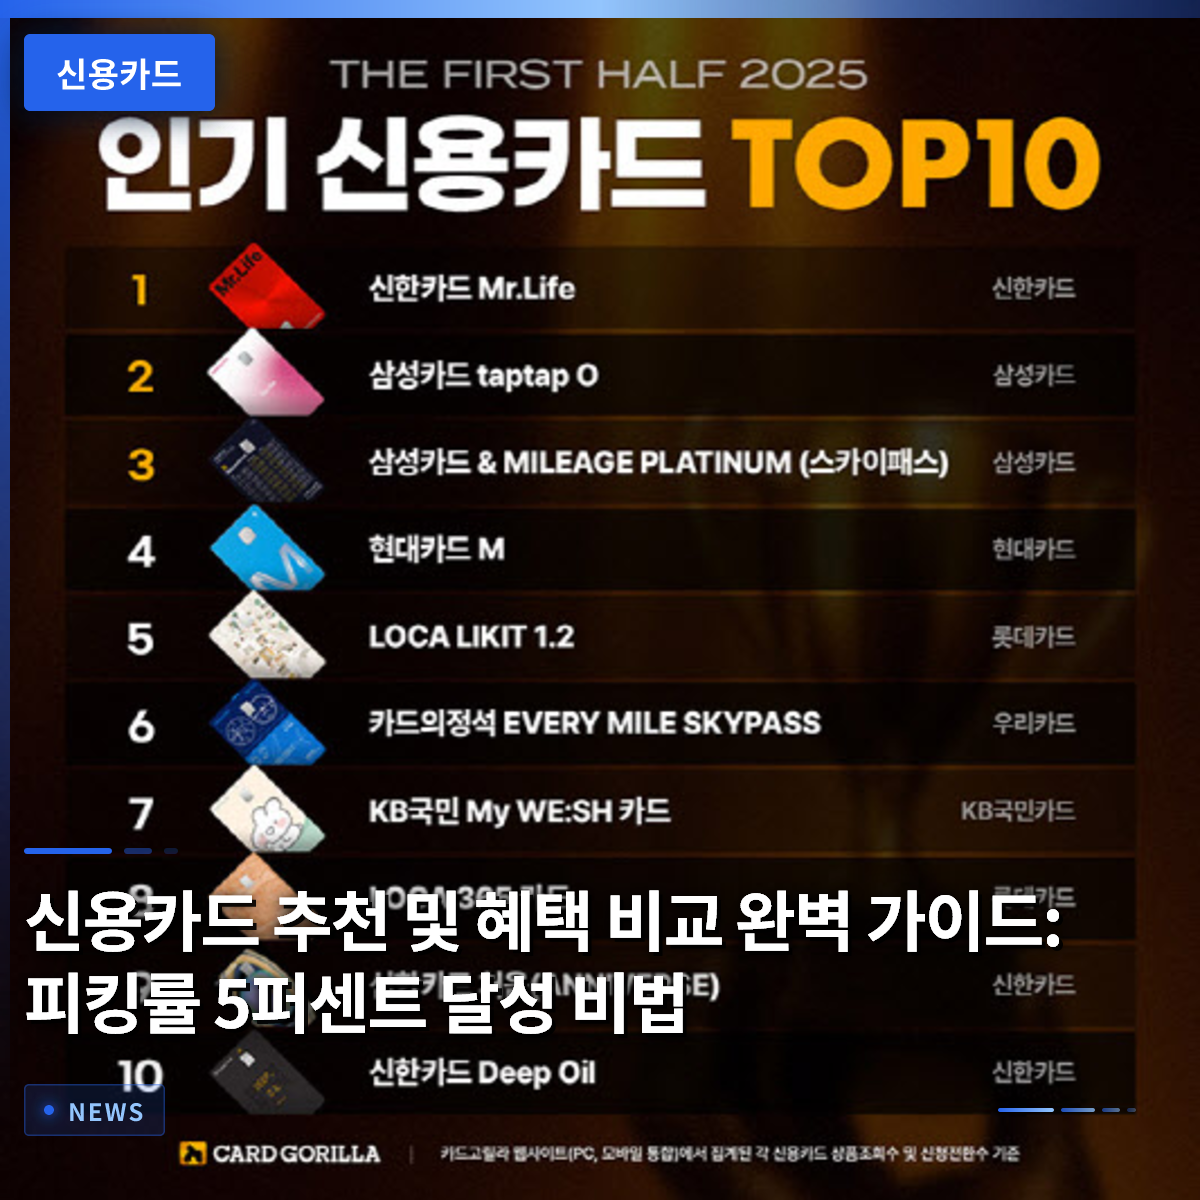
When choosing a credit card, the wisest decision is not simply to pick the one with the highest discount rate, but to select benefits that align with your average monthly spending patterns. It is easy to be lured by advertising claims of “up to 50,000 won per month,” but you must carefully consider the picking rate—the required payment amount necessary to actually receive those benefits. Many people rush to get a card just because others recommend it, only to fail to meet the spending requirements and receive no benefits at all. By analyzing your fixed monthly living expenses and frequently used spending channels, you can find a hidden gem of a card that significantly reduces your household expenditure. In this article, we will thoroughly examine the know-how and precautions for using credit cards effectively in daily life to keep your wallet full. If you have been using your cards without a clear strategy, this is your chance to establish solid spending criteria.
=
The Ultimate Guide to Credit Card Recommendations and Benefit Comparisons: Secrets to Achieving a 5% Picking Rate
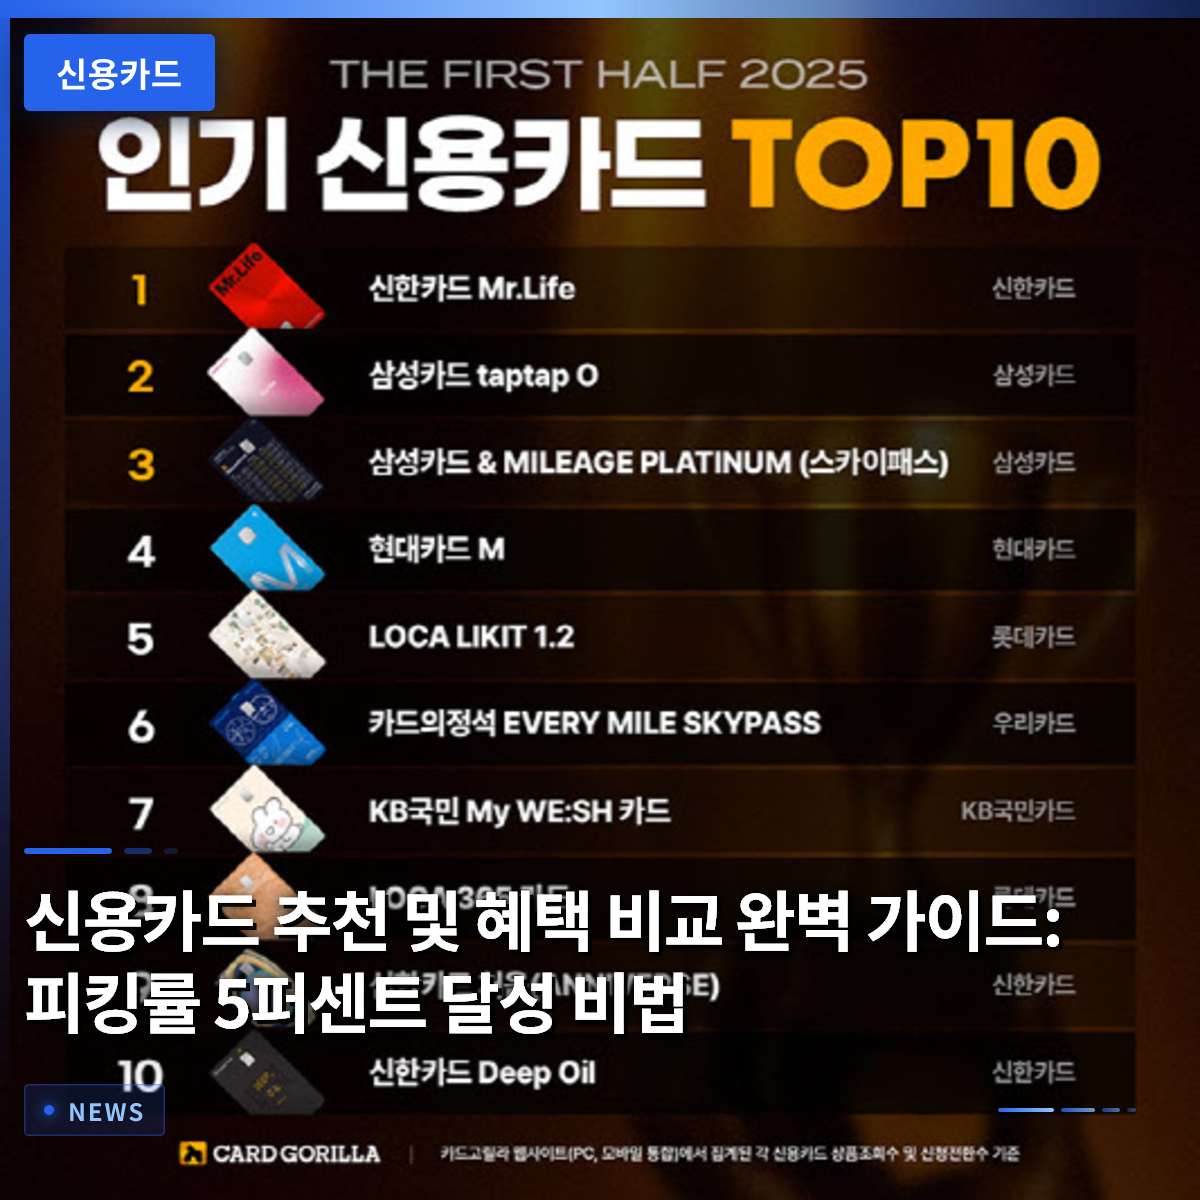
1. Criteria for Comparing Credit Card Benefits: How to Calculate the Picking Rate

The first metric to check when choosing a credit card is the picking rate, which is the ratio of the benefits you receive relative to the amount you spend. Generally, a card is considered to offer excellent benefits if the picking rate is 5% or higher, while a rate below 5% is often seen as lacking appeal. For example, if you pay 300,000 won per month and receive discounts or points worth 15,000 won, you have achieved a picking rate of exactly 5%. However, many people sign up based solely on the maximum benefit amount advertised by the card company, only to find their benefits reduced because they failed to meet the previous month’s spending requirements. Therefore, to avoid losses, you should first accurately calculate your average monthly spending and then choose a card with a previous month’s spending requirement that matches your usage.
You need to develop the habit of carefully verifying whether your actual spending aligns with the spending requirements set by the card company. Rather than being drawn to flashy benefit slogans, it is essential to cross-reference your spending statements with the card’s conditions.
To truly enjoy savings, you should choose a credit card by calculating the picking rate that fits your spending amount, rather than being swayed by flashy advertising slogans.
2. Card Combination Strategies to Maximize Year-End Tax Refunds

As the year-end tax settlement season approaches, the biggest concern for office workers is undoubtedly how to increase their income deduction rate to receive a larger refund. Smart office workers accurately understand the difference in deduction rates between credit cards and debit or prepaid cards, and they use a mix of these payment methods appropriately. Generally, it is advantageous to focus on using credit cards with good discount benefits up to 25% of your total annual income. For amounts exceeding 25%, using debit cards or cash receipts, which have much higher deduction rates, is the shortcut to saving on taxes.
In reality, when you hear stories from colleagues, you’ll notice a significant gap in refund amounts between those who adhere to this ratio and those who do not. By anticipating your monthly living expense flow and actively utilizing the year-end tax preview service, you can secure a generous bonus in early next year. It is absolutely necessary to have the wisdom to divide your spending by category and use different cards for each, rather than sticking to just one type.
The core of tax savings during year-end settlement is to use credit cards for spending up to 25% of your total income and debit cards for the excess amount.
3. Preventing Overdue Risks by Managing Holidays and Payment Dates
You may have had the experience of being shocked and feeling a sinking heart when you suddenly checked your bank account balance on your way to work after a long holiday. When payment dates coincide with holiday periods like Chuseok or Lunar New Year, you may worry about whether the payments will be processed correctly. Fortunately, according to financial regulatory guidelines, credit card bills or loan repayment due dates that fall during holidays are automatically deducted on the first business day after the holiday without late fees. However, if you let your guard down completely, you could end up with an overdue record instantly due to insufficient balance at the time of deduction, so you must ensure your account is funded in advance.
While the automatic deduction system is convenient, the habit of frequently checking your account balance remains very important for credit management. In particular, since expenses tend to spike around holidays, there is a high possibility that your card bill will be higher than usual. You should check the upcoming payment date and billing amount before the holiday begins to prevent any unnecessary drop in your credit score.
Credit card bills due during long holidays are automatically deducted on the first business day after the holiday, so you should check your balance in advance to prevent overdue payments.
4. Tax Blind Spots and Transparent Management of Consumer Expenditure
In recent years, peer-to-peer transactions through online social marketplaces or group buying have exploded, creating new economic trends. However, a significant portion of these peer-to-peer transactions often leave no trace in the form of tax invoices, credit card sales slips, or cash receipts. Tax authorities are making various efforts to reduce these blind spots, and in fact, the National Tax Service has been analyzing individual consumer expenditure electronically for several years. They operate a system that compares declared income with the sum of asset increases over the past few years, real estate and vehicle acquisition records, and credit card and cash receipt usage amounts.
While this electronic network plays a major role in preventing tax evasion and establishing a transparent market order, it also has significant implications for honest general consumers and small business owners. The credit card and cash receipt records we use daily are not just proof of expenditure but become a crucial measure of income and consumption in the eyes of the National Tax Service. Therefore, to continue transparent and sound economic activities, it is safer to use official payment methods correctly in your daily life.
Credit card and cash receipt usage records are fully reflected in the tax authorities’ electronic systems, making transparent consumption management essential.
5. Precautions for Mileage Accumulation and Gift Certificate Purchases
There are many consumers around us who issue and use dedicated credit cards to accumulate airline miles, including those from Korean Air. In addition to earning miles through flights, many people enjoy the process of steadily accumulating miles through credit card partnerships. However, since the accumulation ratios for general flights and partnership rewards (like credit cards) can differ, you must carefully review the terms and conditions. Also, due to policy changes by the Fair Trade Commission and other bodies, the usage venues and annual usage limits for miles are expected to increase gradually, so it is beneficial to accumulate them wisely.
On the other hand, some consumers occasionally purchase large quantities of gift certificates using credit cards to meet spending requirements or for investment purposes. However, in gift certificate purchases, difficult conditions such as card status, the seller’s support for payment methods, and the identity verification process can act as variables. You need to be particularly careful, as proceeding with a payment carelessly assuming you have sufficient remaining limit could result in being excluded from benefits or facing restrictions on card usage.
You should check the mileage accumulation ratios and specific criteria applied to gift certificate purchases in advance to avoid unexpected disadvantages.
6. Building Proper Credit Card Habits for Living Expense Savings
Credit cards are convenient tools that enrich our lives, but depending on how they are used, they can be either a poison or a medicine. Chasing only discount or accumulation rates while increasing unnecessary consumption is putting the cart before the horse and cannot be called true savings. The most ideal way to use a credit card is to naturally collect benefits within the range of your regular fixed living expenses. It is now the trend to periodically review your monthly spending and keep only one or two main cards that provide benefits you truly need, practicing minimal consumption.
In the future, the financial environment will become more complex, and various forms of payment methods will emerge, but maintaining balance is ultimately the consumer’s responsibility. If you reduce impulsive spending and use cards according to a planned budget, it will be a great help to your household economy. I recommend that you open your wallet today and carefully check the performance and benefits of the cards you hold. Small changes in habits will completely change the size of the savings you accumulate over the year.
The most important thing is to reduce unnecessary consumption and develop spending habits centered around main cards that match your living expense patterns.
Frequently Asked Questions
=