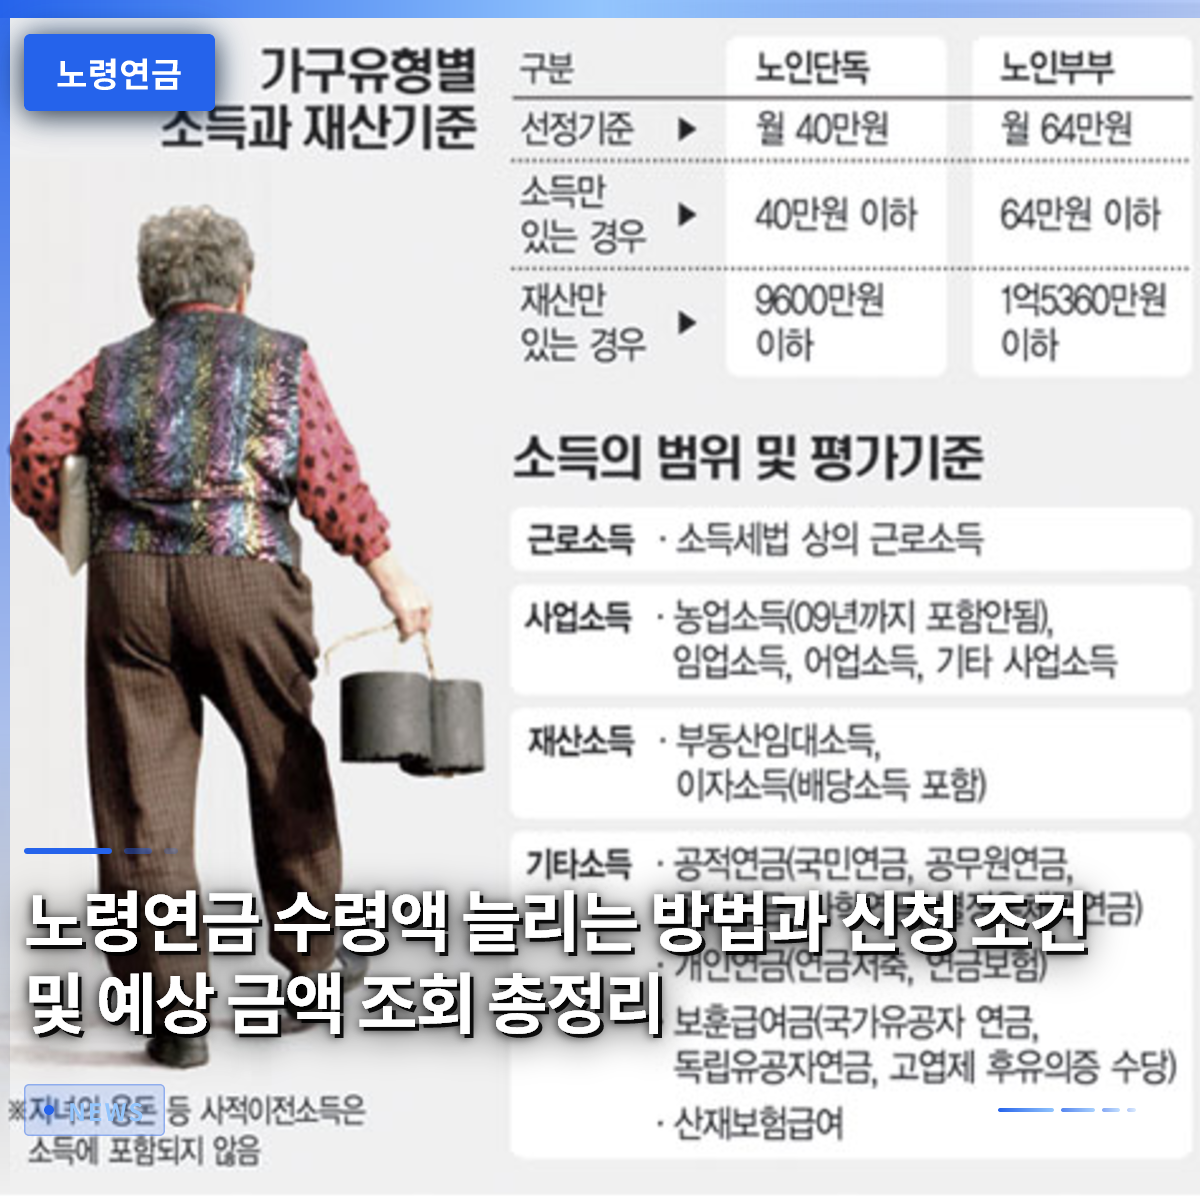
When it comes to the old-age pension, it is crucial to check your estimated benefits in advance and strategically adjust the timing of your receipt to maximize the monthly amount you receive once you reach the eligible age. Many people are disappointed to find that the pension amount deposited into their accounts is less than they expected. To avoid regret later, it is essential to accurately understand your contribution period and changes in the value of money. In reality, many people approaching retirement are curious about the exact amount they will receive and are constantly wondering how they can get a little more. In this article, we will carefully examine how to check your estimated pension amount, tips for adjusting the timing of receipt, and key institutional features you must know. We will explain the pension system in an easy-to-understand way, so reading this article to the end will be of great help to you.
=
A Complete Guide to Maximizing Your Old-Age Pension: How to Increase Benefits, Application Conditions, and Checking Estimated Amounts
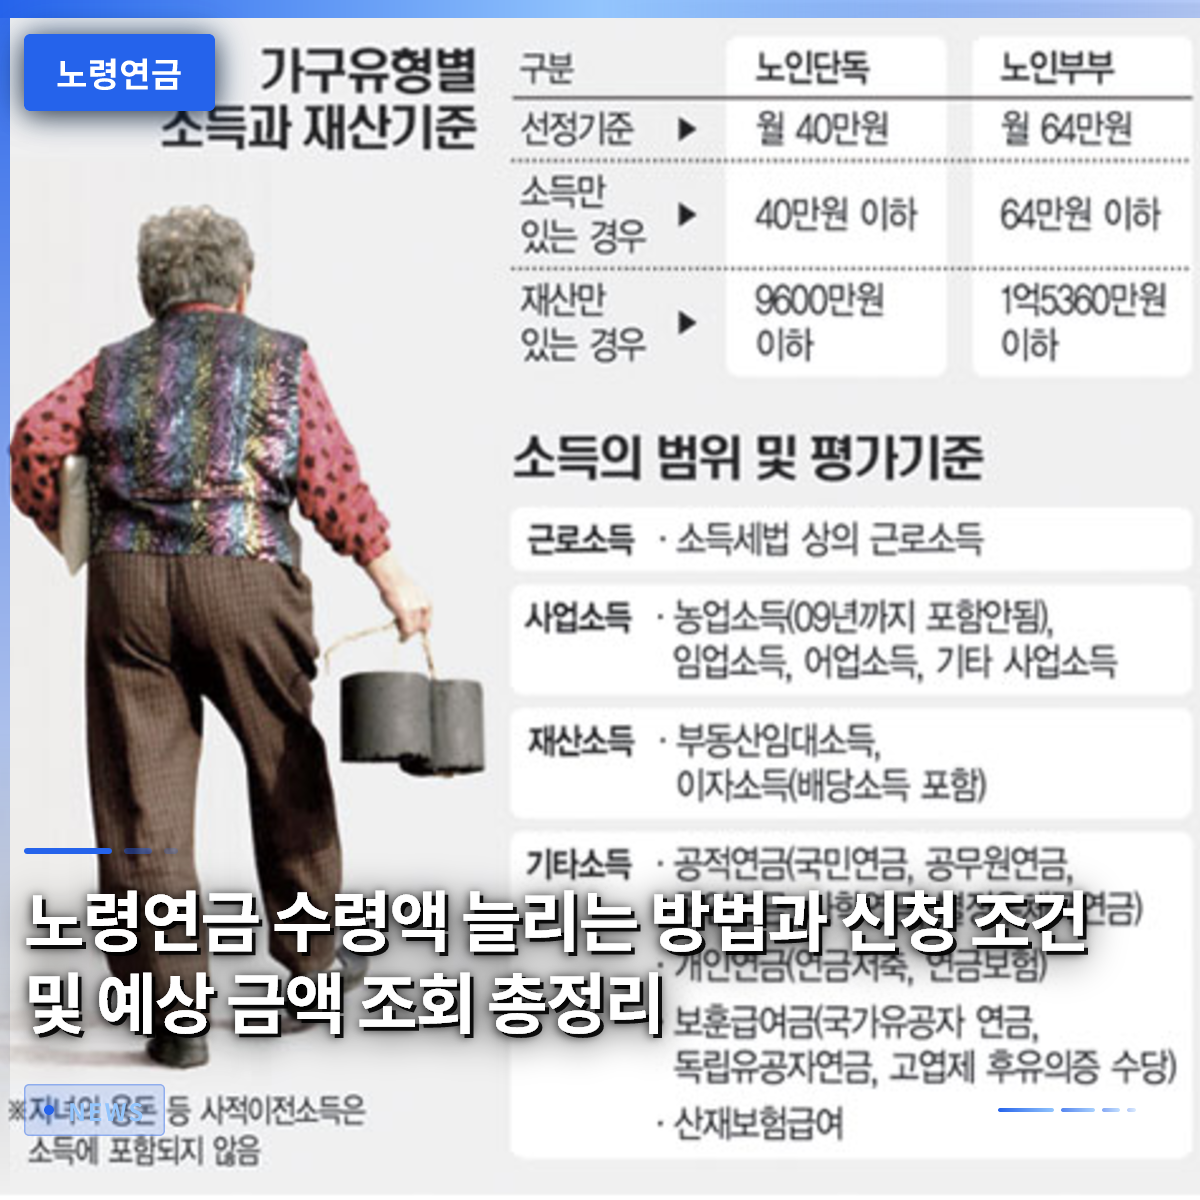
1. Checking Your Estimated Pension Amount and the Value of Money

The first thing you should check when preparing for your old-age pension is the accurate estimated benefit amount based on your current contribution history. In the past, calculations based on simple inflation rates and future value could be confusing, but now you can check more realistic amounts using a method that reflects the time value of money. By logging into the National Pension Service website and running the estimated pension amount inquiry, you can get a preliminary idea of the actual amount you will receive, taking into account both current and future values.
For example, Mr. Kim, who is approaching retirement, expected to receive around 1 million KRW per month. However, after checking his estimated benefits, he was surprised to find the amount was lower than he thought and began seriously considering additional contributions. Rather than facing retirement with vague expectations, it is wise to check your estimated pension amount right now and assess any shortfalls. Given that statistics show six out of ten pension recipients receive less than 600,000 KRW per month, thorough preparation is the key to a comfortable retirement.
When checking your estimated old-age pension, use calculations that reflect the time value of money to realistically assess your retirement funds.
2. Should You Delay Your National Pension? How to Use Deferred Pensions

If you have reached the age for receiving your old-age pension but have enough financial flexibility for living expenses, you can actively consider the deferred pension system, which allows you to delay receipt to significantly increase your monthly amount. The deferred pension system works by postponing the start of your pension for up to several years; in exchange, an interest-like bonus is added to your monthly pension amount for the deferred period, allowing you to receive more for life. To put it simply, even delaying the National Pension by just one month increases the amount, so it is worth weighing your health status and financial flexibility comprehensively.
For instance, if you have other sources of income after retirement and do not urgently need the pension, delaying receipt may be much more advantageous in the long run than claiming it at an early age. Considering the percentage increase in pension benefits for a three-year delay, it can serve as a sturdy pillar to defend against inflation in the coming era of an aging society. However, delaying receipt is not always the right answer; it is wise to carefully consider your life expectancy, health status, and immediate cash flow before making a decision.
By using the deferred pension system to delay receipt, you can significantly increase your monthly pension amount and secure long-term retirement income.
3. Automatic Payment Service and Easy-to-Miss Application Tips

Until recently, even if you met all the eligibility requirements for the old-age pension, you had to visit a National Pension Service branch or apply online to receive payments. However, due to recent system improvements, a pilot automatic payment service has begun for certain eligible individuals, allowing pensions to be deposited directly into their accounts without complex application procedures. This change aims to reduce cases where people who are eligible for pensions suffer disadvantages because they fail to apply on time due to a lack of information or mobility issues.
It is not uncommon for people to forget to apply for their pensions due to busy daily lives, only to realize later that they missed out on several months of benefits. Therefore, it is a good idea to check in advance whether you are eligible for the automatic payment service. If you are not eligible, it is safer to apply directly to ensure you do not miss your receipt date. Do not forget that a little attention and verification is the most reliable way to secure your valuable retirement funds on time.
The introduction of the automatic payment service for old-age pensions has improved convenience, but you still need to verify your eligibility and prepare accordingly.
4. Everything You Need to Know About the Divided Pension System in Case of Divorce
Even if you have gone through the pain of ending a marriage, the divided pension system allows you to share your ex-spouse’s old-age pension if the marriage met certain conditions. The National Pension divided pension is a right that can be claimed through negotiation or legal procedures when the marriage lasted at least five years and both parties have reached the old-age pension receipt age. You must apply within five years of the date the right arises, or the right will expire, so you must pay special attention to the deadline.
For example, Ms. Lee, who was worried about her livelihood after a late-life divorce, learned about the divided pension system later on and was able to secure a stable monthly living expense and build a new life. Recognizing the contribution to the contribution period accumulated by the couple and sharing a portion of the pension is a valuable right guaranteed by law. You must remember that when proceeding with divorce litigation or property division, severance pay and pension assets are also important objects of division.
If the marriage lasted at least five years and you have reached the receipt age, you can share your ex-spouse’s pension through the divided pension system.
5. Taxes and the Relationship with Survivor’s Pensions When Receiving Old-Age Pensions
Even though the old-age pension is received after a lifetime of diligent premium payments, you should be aware that taxes may be applied to the amount deposited into your account depending on the receipt amount. The National Pension is also subject to taxation under the Income Tax Act, so a certain percentage of tax may be withheld from the pension amount based on your total comprehensive income before payment. Additionally, many people are unsure whether to choose between a survivor’s pension and an old-age pension. It is advantageous to consider a method where you choose your own old-age pension while receiving a certain percentage of the survivor’s pension.
You may hear stories from seniors who were shocked to find that a significant amount of tax was deducted from their pensions after retirement; this is often because their pension income was combined with other sources of income. Since there are restrictions on receiving both a survivor’s pension and one’s own pension simultaneously, you need the wisdom to compare the sizes of the two pensions and choose the option that is more beneficial to you. Tax issues and coordination of overlapping benefits are easy to overlook, but they directly affect your actual take-home amount, so thorough prior verification is essential.
Old-age pensions can be subject to taxation, and you should consider the relationship with survivor’s pensions to choose the most advantageous receipt method.
6. Outlook on Utilizing Old-Age Pensions for a Successful Retirement
In the coming aging society, the importance of the state-guaranteed old-age pension will grow even greater, and an individual’s thorough retirement planning will determine a happy old age. It is an essential virtue for modern retirees to develop a comprehensive perspective that goes beyond simply receiving a pension, including checking estimated amounts, utilizing deferred pensions, and managing taxes. The system is continuously improving in more convenient directions, so you should keep an eye on related news and try to apply it to your own situation.
Retirement is not an end but the beginning of a new life, and the old-age pension deposited into your account every month is the strongest pillar supporting that new start. Based on the various systems explained today, I hope you will steadily build your own pension receipt strategy without being swayed by surrounding circumstances. To make the time ahead comfortable and abundant, please check your pension contribution history and estimated receipt amount right now.
You must formulate an old-age pension strategy and prepare thoroughly amidst rapidly changing systems to enjoy a stable and abundant retirement.
Frequently Asked Questions
=