Pension insurance is an essential financial product for creating a stable cash flow after retirement, but canceling it midway can result in significant losses. In reality, few people truly understand what benefits they will receive in their old age, despite paying premiums diligently every month. It is common to see people who enrolled simply because others recommended it or because they were lured by tax deduction benefits, only to face difficulties later. In fact, many office workers have experienced the pain of canceling their contracts before completing ten years, failing to even recover their principal. In this article, we will thoroughly examine the types of pension insurance, how to use it correctly, and recent institutional changes that are drawing attention. By reading this article to the end, you will gain the wisdom to protect your precious retirement funds.
=
Essential Information and Tax-Saving Tips You Must Know When Enrolling in Pension Insurance
1. Understanding Pension Insurance: The Foundation of Retirement Planning
When preparing for retirement, the first product that comes to mind is pension insurance, where you pay a fixed amount monthly and receive payments after retirement. Many people worry about their post-retirement life but hesitate because they are unsure which product to choose. I also remember enrolling in a product based solely on a bank employee’s advice, only to regret it later after carefully reviewing the terms. If you do not accurately understand the product’s structure, you may face disappointing results as it fails to keep up with inflation. Therefore, you must first assess whether the monthly outlay is appropriate for your income level and whether you can sustain it long-term.
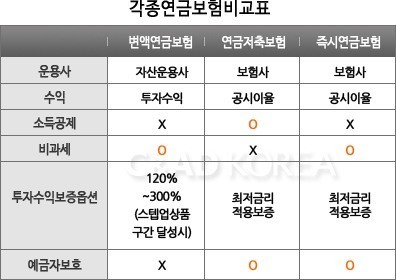
Simply following the crowd by enrolling in whatever others are buying does not help in securing retirement funds. You need the wisdom to clearly understand the difference between tax-qualified and tax-exempt products and choose the one that benefits your income structure. For example, high-income office workers may benefit from products that maximize tax deduction benefits. On the other hand, self-employed individuals with irregular incomes should look for products with flexible structures that allow them to adjust payments at any time. Retirement planning is like a marathon, not a sprint, so it is most important not to overextend yourself from the start.
Pension insurance should be chosen carefully, taking into account your income structure and retirement timing.
2. Why Mid-Term Cancellation Is Risky and How to Handle It
While pension insurance offers greater benefits the longer you keep it, canceling it before completing ten years can lead to a dismal outcome where you cannot even recover your principal. Many people diligently pay hundreds of thousands of won monthly, only to be shocked when they check the surrender value upon needing urgent cash. In the first few years, expenses and risk premiums are deducted first, so the amount returned upon cancellation is significantly less than the principal paid. For instance, Mr. Kim, an office worker, had a painful experience of canceling a product he had paid into for five years due to a sudden need for business funds, resulting in recovering less than half of his principal.
If you suddenly face a cash shortage, it is much wiser to utilize payment suspension or reduction systems rather than canceling immediately. If you contact the insurance company and explain your situation, they can guide you to systems that allow you to defer premium payments for a certain period. Additionally, you can use policy loans to save on fees, so unconditional cancellation should be avoided. Maintaining the contract while getting through the crisis is the only way to prevent financial loss in the long run. Remember that breaking a financial product midway brings losses as severe as incurring debt to a bank.
Mid-term cancellation leads to principal loss, so you should first look for alternatives such as payment deferral or policy loans.
3. Understanding the Relationship Between the Four Major Insurances and Pensions
The premiums for the four major insurances, which are deducted from salaries every month, are a significant burden for office workers but also serve as a sturdy safety net for retirement. However, if you switch to self-employment or resign and take unpaid leave, these premiums suddenly become a frightening bill. Since premiums are calculated based on the previous year’s confirmed income, many self-employed individuals face difficulties as they are billed based on last year’s income even if their sales have plummeted this year. In such cases, you must proactively submit documents proving income reduction and apply for premium adjustment to prevent unnecessary expenses.
Even during periods of unpaid leave, health insurance and national pension payments do not automatically stop; you must apply for payment deferral or exemption. If you fail to apply, you may be treated as a delinquent, leading to scary legal procedures such as seizures or provisional seizures. While various reduction systems are supported by the state, they will never be applied automatically unless you apply for them yourself. It is easy to see cases where people ignore bills out of inconvenience, only to incur surcharges or see their credit scores drop. You need to regularly check the flow of money leaving your account and actively utilize these systems.
You must apply directly to reduce the burden of the four major insurances and pension systems when your income fluctuates.
4. The Issue of Double Payments for Overseas Dispatched Workers
As more companies enter the global market, the issue of double payments for workers dispatched overseas has emerged as a serious social topic. Even if workers have diligently paid pensions in Korea, they face the frustrating situation of being required to pay insurance premiums again in the host country. This double burden is cited as a major factor that lowers the competitiveness of our companies abroad and demoralizes workers. The government and relevant agencies are actively negotiating with various countries to resolve this issue.
In fact, discussions on signing Investment Protection Agreements and Social Security Agreements with several countries, including Mexico, have gained momentum through recent summit meetings. If these agreements are signed promptly, overseas dispatched workers will be relieved of the heavy burden of paying double contributions to both countries. From the companies’ perspective, reducing unnecessary labor costs will provide a foundation for further momentum in overseas expansion. Close cooperation between nations will ultimately lead to valuable results that directly affect the daily lives of our citizens. We hope that the government’s diplomatic efforts will expand to agreements with even more countries in the future.
The issue of double pension payments for overseas dispatched workers must be resolved through the prompt signing of social security agreements.
5. The Ideal Combination of National and Private Pensions
For a stable retirement, you need the wisdom to harmoniously combine the basic framework guaranteed by the state with private products prepared by individuals. Some mistakenly believe that relying solely on the national system will ensure a smooth post-retirement life, but considering inflation, this is far from sufficient. Conversely, putting all your assets into private products can block your cash flow in your younger years, making your immediate life too difficult. Therefore, you must accurately calculate your expected retirement timing and required living expenses, then appropriately allocate the ratio between the two systems.
For example, a good strategy is to cover basic food and housing needs with public systems and fill in leisure activities or medical costs with private products. When you meet retired seniors around you, their biggest concern after retirement is the lack of fixed income, and the key to solving this is enrolling in multiple pensions. The more diverse the sources of cash coming into your account each month, the greater your psychological stability and the more noticeable the improvement in your quality of life. You should develop the habit of saving little by little from a young age so that you are not caught off guard when large sums are needed later. Retirement planning is not achieved overnight but is the result of consistent accumulation over a long period.
You can welcome a secure and stable retirement by appropriately combining public systems and private products.
6. Future Prospects of Pension Systems and Our Attitude
As we approach a super-aged society, concerns about the sustainability of pension systems are expected to grow, but thorough individual preparation remains the unchanging answer. Rather than blaming government policy changes or economic conditions, we must build a strong financial defense to protect our own retirement. Reducing fixed monthly expenses and diversifying assets are the virtues most needed by us right now. It is important to make and implement realistic plans that fit your financial situation rather than blindly following expert opinions.
Start by checking your current financial asset status and carefully examining any unnecessary money leaks. It is also good to discuss the information you have learned with people around you and consider better directions for wealth management. Retirement is a future that everyone faces, but how you face it depends entirely on your choices today. Small concerns and actions will eventually gift you a prosperous and leisurely retirement life. The time to think it is too late is the earliest time, so please check your pension plan right now.
You must check your financial status and actively prepare for retirement in a changing environment.
Frequently Asked Questions
=