If you compare fixed deposit interest rates at major commercial banks right now, you will notice that most one-year maturity products fall within a narrow range of 3.0% to 3.5% per annum. It is important to keep in mind that this does not mean interest rates are rising across the board. While commercial banks recently raised deposit interest rates to secure funding, the situation varies by bank, making careful verification essential. Mr. Kim, an office worker who was planning to simply renew his deposit that matured last year, assumed the interest rate differences between banks were negligible. However, he was surprised to find significant variations after examining the detailed terms. As deposit interest rates undergo fine-tuning in response to changes in loan rates and funding costs, it is better to scrutinize the details thoroughly rather than just visiting the nearest branch. In this article, we will examine in detail the current interest rate levels of major financial institutions and the tips for uncovering hidden preferential conditions. If you are looking for smart asset management, please read to the end to help grow your valuable assets.
=
Key Points for Comparing Fixed Deposit Interest Rates in September 2026 and Tips for Finding the Highest Interest
1. Current Status of Fixed Deposit Interest Rates at the Top 5 Commercial Banks
Currently, the representative one-year fixed deposit products at the top five commercial banks mostly show a narrow interest rate distribution between 3.30% and 3.45% per annum. Although banks are competing to attract funds, interest rates have become so standardized that it is difficult to feel a significant difference. Mr. Lee, an office worker living in Seoul, recently struggled with where to place his lump sum that had just matured, so he visited the counters of major banks to compare interest rates. However, contrary to his expectations, the gap in interest rates between banks was not large, leading him to realize that to earn even a few extra cents in interest, he needed to check if he met the preferential conditions. Since interest rates are adjusted frequently in response to changes in bank bond issuance or wholesale funding costs, it is safer to check the latest disclosures before signing up. In reality, some banks offer special products for a specific period to expand retail deposits, but most maintain similar levels. Therefore, rather than deciding on a bank based solely on the basic interest rate figure, it is more advantageous to take advantage of the preferential benefits from your primary bank. You can receive additional interest by meeting criteria such as automatic transfer records or credit card usage history, so you should reflect on your own transaction habits. It is not uncommon for people to regret not finding a better product later after opening a deposit without careful comparison. Right now, please access the official app or internet homepage of the bank you deal with to check the actual applicable interest rate.
One-year deposits at the top five commercial banks are clustered around the mid-3% range, so you must carefully check preferential conditions.
2. Characteristics of Interest Rates for Savings Banks and Mutual Financial Institutions

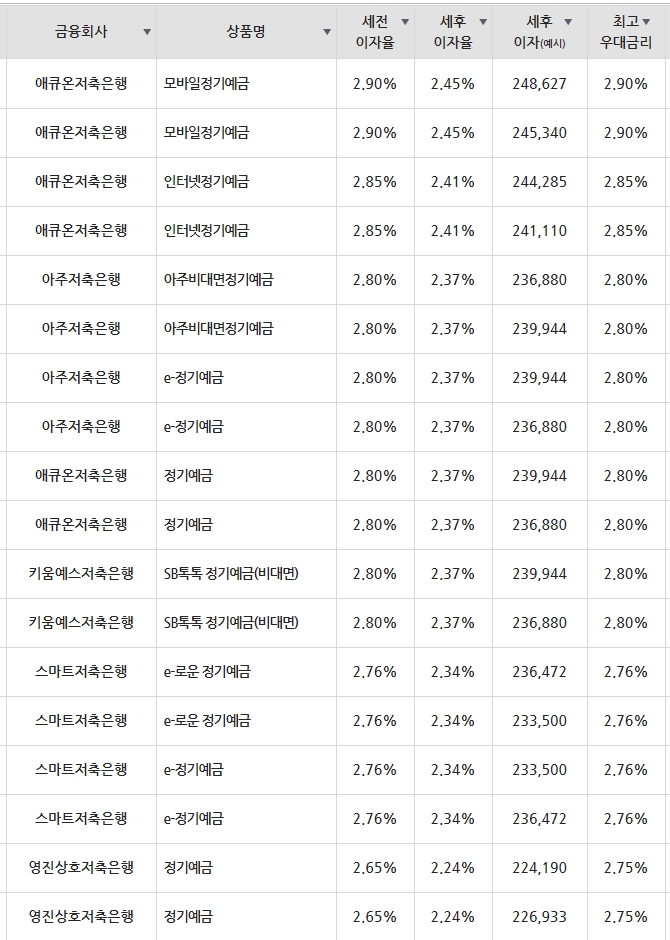
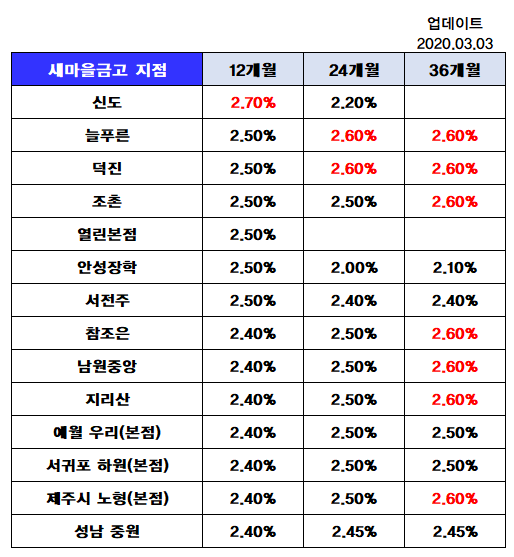
When comparing fixed deposit interest rates at second-tier financial institutions such as savings banks, the National Cooperative Federation (NHF), and the National Agricultural Cooperative Federation (NACF), they often offer slightly higher interest rates than commercial banks. This is because each financial cooperative or branch operates autonomous special products to attract public deposits from local governments or general household funds. Mr. Park, a self-employed business owner in Busan, was looking for a place that offered even slightly higher interest than commercial banks and found great satisfaction in signing up for a special product at a local NHF branch. However, since second-tier financial products may have different management indicators or soundness ratios by branch, it is strictly forbidden to chase only the highest number. Deposits are safely protected up to 50 million won per person (including principal and interest) under the depositor protection limit, so staying within this range is paramount. Formulating a strategy to disperse deposits across multiple branches allows you to prepare for potential risks while maximizing interest income stably. While referring to the latest special product information posted on internet communities or financial information websites, you must always cross-check through the official channels of the respective financial institution. Wisdom is needed to avoid being misled by false information or exaggerated advertising and to secure interest within a safe framework.
Second-tier financial institutions offer relatively higher interest rates, but you must strictly adhere to the 50 million won depositor protection limit and disperse your deposits.
3. Understanding the Relationship Between Interest Rate Hikes and Funding Costs
Recently, the financial market has seen fierce competition for deposit acquisition as banks’ funding costs rise. As banks incur higher costs in the process of issuing bonds or attracting deposits to release funds into the market, this directly impacts interest rates. Mrs. Jung, a housewife living in Gyeonggi Province, wondered why the interest on her deposits was not rising as much as her loan interest, which keeps going up. This is due to the subtle time lag and cost burden between how banks secure funds for loans and the structure of collecting money through deposits. As commercial banks show movements to reduce their reliance on wholesale funding and actively expand retail deposits, favorable conditions may emerge for depositors. However, interest rates are not rising uniformly across all products; there are significant differences in the magnitude of increases depending on the maturity period or product type. If you regularly monitor trends in base interest rates and market indicators through economic news, it will greatly help you capture the right timing for deposits. Rather than waiting blindly, it is wise to find the product offering the most favorable conditions at the current moment and sign up in installments.
Rising bank funding costs and competition for securing funds act as direct causes of fluctuations in deposit interest rates.
4. How to Utilize Tax-Exempt Benefits for the Elderly (65 and Over)
If you are an elderly person aged 65 or older, you should prioritize checking the tax-exempt comprehensive savings limit when comparing fixed deposit interest rates, rather than choosing general taxable products. This is because saving on the national income tax and local income tax applied to general deposit interest can result in a significant difference in the actual amount received. Mr. Choi, a retiree living in Seoul, took his children’s advice and used his eligibility for being over 65 to fill up to the tax-exempt limit with a fixed deposit. He enjoyed the effect of receiving the 15.4% tax as interest and actively informed his friends about this useful system. Since this benefit is applied within the integrated limit of financial institutions, it is essential to calculate your remaining limit across multiple banks in advance. You can simply process this by visiting a bank branch or using the official app to confirm your eligibility and submitting the documents. Small tax differences can lead to significant differences in asset growth over time, so this is an opportunity that eligible individuals must never miss. Tax-advantaged or tax-exempt products are only applicable at the time of signing up, so it is advantageous to maintain them until maturity without early withdrawal.
Elderly individuals aged 65 and over should utilize the tax-exempt comprehensive savings limit to reduce tax burdens and increase their actual interest income.
5. Tips for Using Online Comparison Platforms and Official Disclosures
These days, with just a smartphone, you can easily compare fixed deposit interest rates through various financial information websites and apps. Mr. Kim, who works in Daejeon, has developed the habit of turning on financial apps during his lunch break to check the highest interest rates of each bank in real-time. In the past, one had to go out of their way to gather information, but now a world has opened up where you can view all special product information nationwide at a glance from home. However, just because it is convenient to look up, you must be cautious of impersonation sites or false advertisements and ultimately trust the official comparison disclosures from financial authorities. By accessing the official websites of the Financial Services Commission or the Korea Bankers Association, you can accurately verify the latest terms and actual applicable interest rates of each financial institution. It is safer to entrust your assets based on data from certified institutions rather than relying on uncertain rumors circulating on the internet. By regularly updating your apps and setting notifications, you can keep track of interest rate trends and move your assets at the appropriate time.
While utilizing convenient online comparison tools, you must always check the official comparison disclosures from financial authorities before finalizing your deposit.
6. Maturity Strategies and Outlook for Successful Asset Management
Deciding whether to choose short-term or long-term products while predicting future interest rate trends is one of the core tasks of wealth management. Mr. Han, a freelancer living in Incheon, was unsure how interest rates would change in the future, so he split his money between a 6-month short-term product and a 1-year product. By dispersing funds this way, you can respond flexibly when market conditions change rapidly, and it greatly helps in securing liquidity. Experts forecast that deposit interest rates will fluctuate slightly depending on future economic indicators and the direction of the central bank’s monetary policy. Therefore, rather than forcing yourself to lock in all your lump sums at once, the safest method is to formulate a ladder-style maturity diversification strategy. If you have idle funds in your wallet, try carefully comparing the conditions of nearby banks based on the tips provided today. Small attention and action will serve as a great foundation for completing a solid piece of your future assets.
It is important to diversify maturities and formulate a ladder-style asset management strategy to prepare for interest rate volatility.
Frequently Asked Questions
=