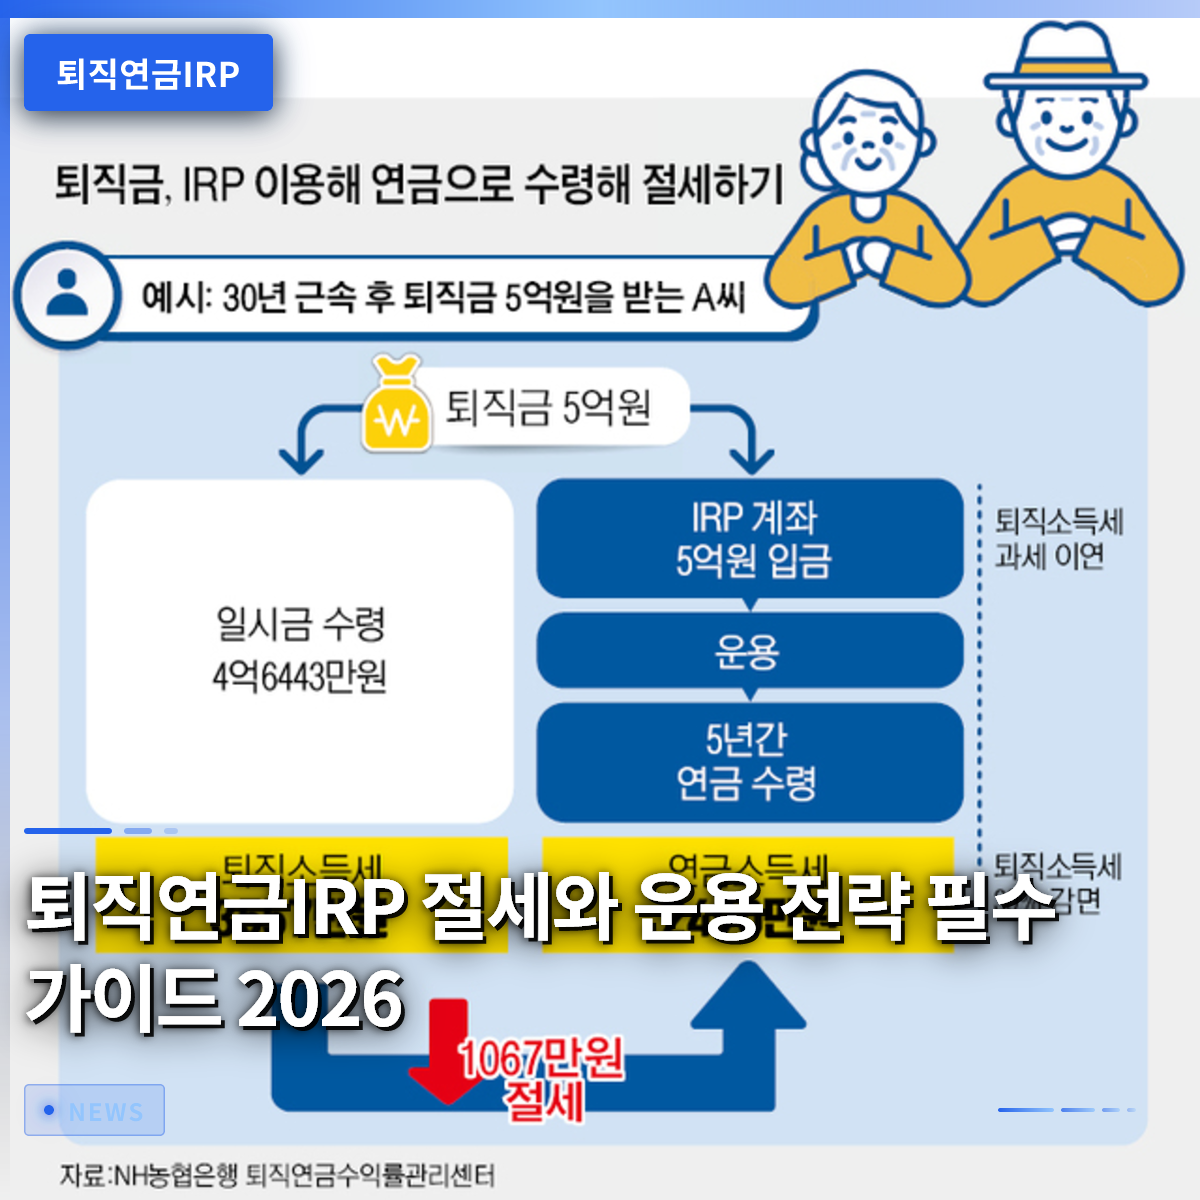
The Retirement Pension IRP account is an essential tax-saving account that every employee should definitely open and utilize. Many people are often at a loss as to how to manage their severance pay when they change jobs or approach retirement. Instead of just feeling envious when you hear colleagues saving millions of won in taxes, you should actively use this account to secure tangible benefits for yourself. Recently, as the scope of asset management through this account has expanded and tax-saving effects have grown, interest among employees has been soaring. Today, we will take a detailed look at all the ways to smartly use this account to reduce taxes and grow your retirement funds. Instead of using complex financial jargon, we will explain everything using everyday examples that anyone can easily understand.
=
Essential Guide to Tax Savings and Investment Strategies for Retirement Pension IRP in 2026
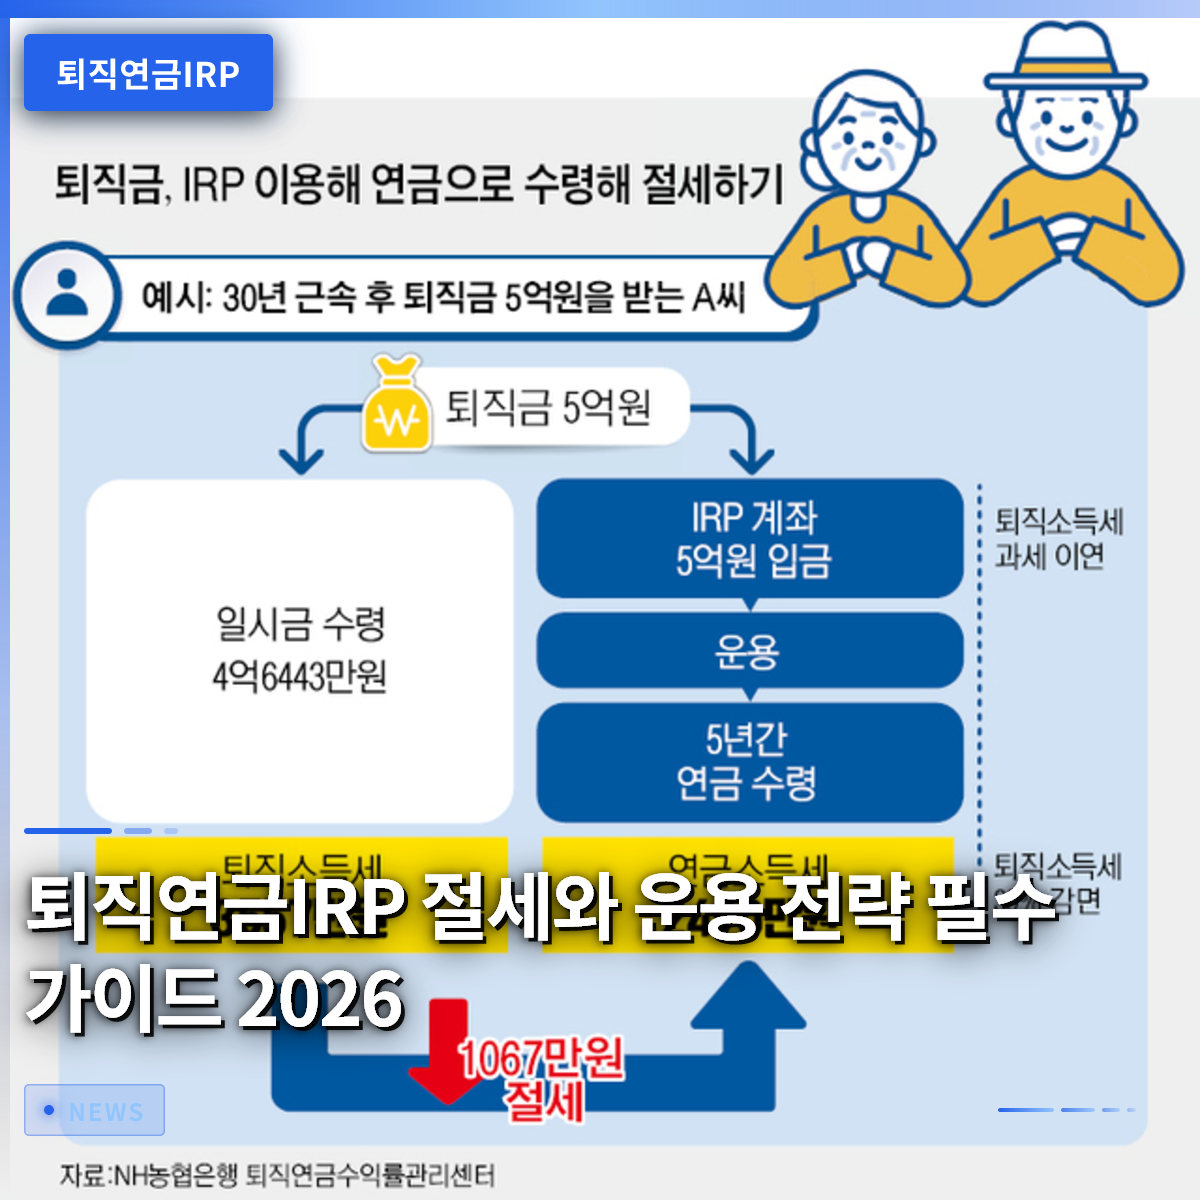
1. Why You Must Receive Your Severance Pay in an IRP and the Tax Savings Effect

If you receive your valuable severance pay directly into a regular checking account upon leaving or changing jobs, you could face a tax bomb. While severance income tax rates are lower given that it is compensation for long-term service, receiving it in a regular account results in immediate withholding, reducing your lump sum. However, if you transfer this money to a Retirement Pension IRP account, you can defer the tax payment and keep the full amount accumulated. This is known as the tax deferral effect. Since the money that would have gone to taxes remains in the account to grow, you can maximize the compound interest effect. In fact, because tax payment is deferred until you receive it as a pension after retirement, you can significantly increase the size of your retirement funds.
After transferring your severance pay to this account, if you later receive it in the form of a pension, you can receive a tax reduction of 30% to 50% on the original severance income tax. Additionally, you can fully enjoy tax credit benefits on the amounts you contribute annually by the year-end tax settlement, offering a two-for-one effect. For example, employees who consistently contribute often enjoy the joy of receiving refunds ranging from hundreds of thousands to over a million won at year-end. Remember that the reason your friends smile every year during tax settlement is because they actively utilize this account. Therefore, when changing jobs or receiving a lump sum, it is wise to immediately open a dedicated account and link it rather than carelessly withdrawing to a regular account.
You must receive your severance pay in an IRP account to defer taxes and establish a tax-saving strategy that significantly reduces taxes when receiving pension payments.
2. 2026 Latest Tax Credit Limits and Tips to Maximize Year-End Tax Refunds

Every year during the year-end tax settlement season, employees look forward to their refunds with a mix of hope and worry, finding vitality in their work life. As of this year, combining your pension savings account and this account allows you to receive tax credit benefits on up to 9 million won annually. An employee with a total annual income of 50 million won who fills the limit will receive a substantial refund ranging from hundreds of thousands to over a million won, depending on their income bracket. This refund is not simply free money; it is a definite and direct reward from the state for citizens who prepare for their retirement independently. In an era of high prices where it is difficult to build assets on a salary alone, year-end tax refunds play the role of a timely rain for household economies.
Rather than forcing a large lump sum contribution to meet the tax credit limit, it is more advantageous to consistently contribute a fixed amount monthly via automatic transfer. Manager Kim has maintained a method of setting up an automatic transfer of 500,000 won per month and topping up the remaining amount at year-end for several years. Thanks to this, he receives the highest level of tax refunds that others envy every year during tax settlement, which he enjoys using for family travel. Carefully considering your annual income and available funds to set an appropriate monthly contribution amount is the shortcut to success. While depositing everything at once a year is not bad, the habit of managing funds consistently monthly is far more helpful in the long run.
By filling the maximum tax credit limit of 9 million won by combining pension savings and IRP, you can secure a generous year-end tax refund every year.
3. Efficient Management Methods from Principal-Guaranteed Deposits to Stock Index-Linked Products

In the past, there were many complaints that money deposited in this account was always tied up in low-interest fixed deposits that couldn’t even keep up with inflation. However, over the last few years, as the financial market has diversified, it has become possible to freely invest not only in deposits but also in various funds and exchange-traded fund (ETF) products. Investors who prefer stability can choose fixed-interest deposit products to safely protect their principal while steadily accumulating interest income. On the other hand, young employees who want to grow their assets more aggressively may invest in equity funds or products that track global indices.
As retirement approaches, it is important to naturally adjust your portfolio by reducing the proportion of risky assets and shifting to safe bond-type or mixed-type products. Actual statistics show that pension-type products tend to effectively defend against declines in sharp market drops compared to general investment products. For example, if you have invested in a bond-mixed product when the stock market is highly volatile, you can diversify the impact on your total assets and protect your valuable principal. When you open your financial company’s application, you can see at a glance how your account is performing and its yield, so you should check it periodically. If you are unsure about which products to choose, consulting with an expert or referring to retirement asset allocation guidelines is also a good method.
You should select products that match your investment style, from deposits to various funds, to achieve both profitability and stability.
4. Perfect Preparation for Personal Investment Government Bonds and Mandatory Safe Asset Ratio Regulations
In line with the increasing trend of employees wanting to directly invest in safe government-issued bonds, institutional changes have continued steadily. Due to recent regulatory revisions, it is now possible to purchase 10-year and 20-year personal investment government bonds through DC-type retirement pensions and this account. This is very attractive to those who want to solidly protect their retirement funds, as the state guarantees the principal while providing a premium interest rate for long-term investment. However, since you cannot deposit unlimited amounts into a pension account, you must accurately check the specific purchase limits.
Because of the regulation requiring at least 30% of assets to be safe assets, many employees are concerned about how to structure their assets. It is not necessary to hold only boring deposits; utilizing mixed-type products that combine stocks and bonds allows you to comply with regulations while securing returns. For example, choosing a product that mixes stock index-tracking products and safe bonds in appropriate proportions satisfies regulations and balances your assets. Those who flexibly adjust their asset allocation strategy every time the financial market trends change are the ones who will ultimately smile in retirement. Try building your own unshakable asset fortress by appropriately mixing state-guaranteed safe government bonds and equity assets.
You must understand the allowance for personal investment government bonds and the mandatory safe asset ratio regulations to construct a balanced long-term portfolio.
5. Cautions When You Need Cash and Alternatives to Early Termination
In social life, moments when you suddenly need a large sum of money inevitably arise, such as when buying a house or dealing with a serious illness. In such times, the first thing that comes to mind is the retirement pension account you have been steadily accumulating. However, if you simply terminate it, you will face a massive tax bomb. You must absolutely avoid early termination unless it is for a special reason legally defined, such as purchasing a house as a non-homeowner, securing a deposit for a lease, or requiring medical care. If you proceed with early termination due to a simple change of heart or to raise emergency funds, you must return all the tax credit benefits you have received so far.
Moreover, you must remember that you will have to pay additional taxes at a high rate under the name of miscellaneous income tax, resulting in significant losses. For this reason, the government and financial institutions operate an early withdrawal system based on legal grounds instead of breaking the account when you urgently need money. By submitting relevant documents to your company’s HR department and the financial institution and passing the review, you can withdraw the necessary amount without terminating the account. If you recklessly dismantle your valuable retirement funds just because you need money immediately, your life after retirement could become seriously difficult. The more difficult the time, the more you should carefully understand the document review system and consult with experts to find the direction with the least damage.
Do not simply terminate the account early when you need cash, as you will face a tax bomb; instead, prioritize utilizing the early withdrawal system based on legal grounds.
6. Final Check for a Successful Retirement Using Retirement Pension IRP
Summarizing the content reviewed so far, this account is not just a piggy bank where you put money away, but plays the role of a reliable lifelong companion. The post-retirement life of an employee who consistently accumulates a fixed amount monthly and secures tax credit benefits is worlds apart from that of someone who does not. The habit of steadily accumulating your severance pay in the account every time you change jobs, rather than spending it on daily living expenses, determines your future prosperity. Regardless of how economic conditions change in the future, you need to establish your own unshakable principles and maintain the attitude of periodically checking your account status.
Retirement is a future that everyone faces, but how you prepare for that future depends entirely on the choices you make in this very moment. Starting today, turn on your financial company’s application and check your monthly automatic transfer amounts and the products you currently hold. If there are shortcomings, you must show the decisiveness to increase your contributions up to the tax credit limit and boldly replace products with low yields. Imagine yourself enjoying the second act of retirement with a smile ten or twenty years from now, and start with small practical steps right now. I sincerely hope that, with this account—the most powerful weapon of a wise employee—you will beautifully complete a secure and happy retirement.
You must thoroughly prepare for a stable and prosperous post-retirement life through consistent contributions and periodic portfolio checks.
Frequently Asked Questions
=