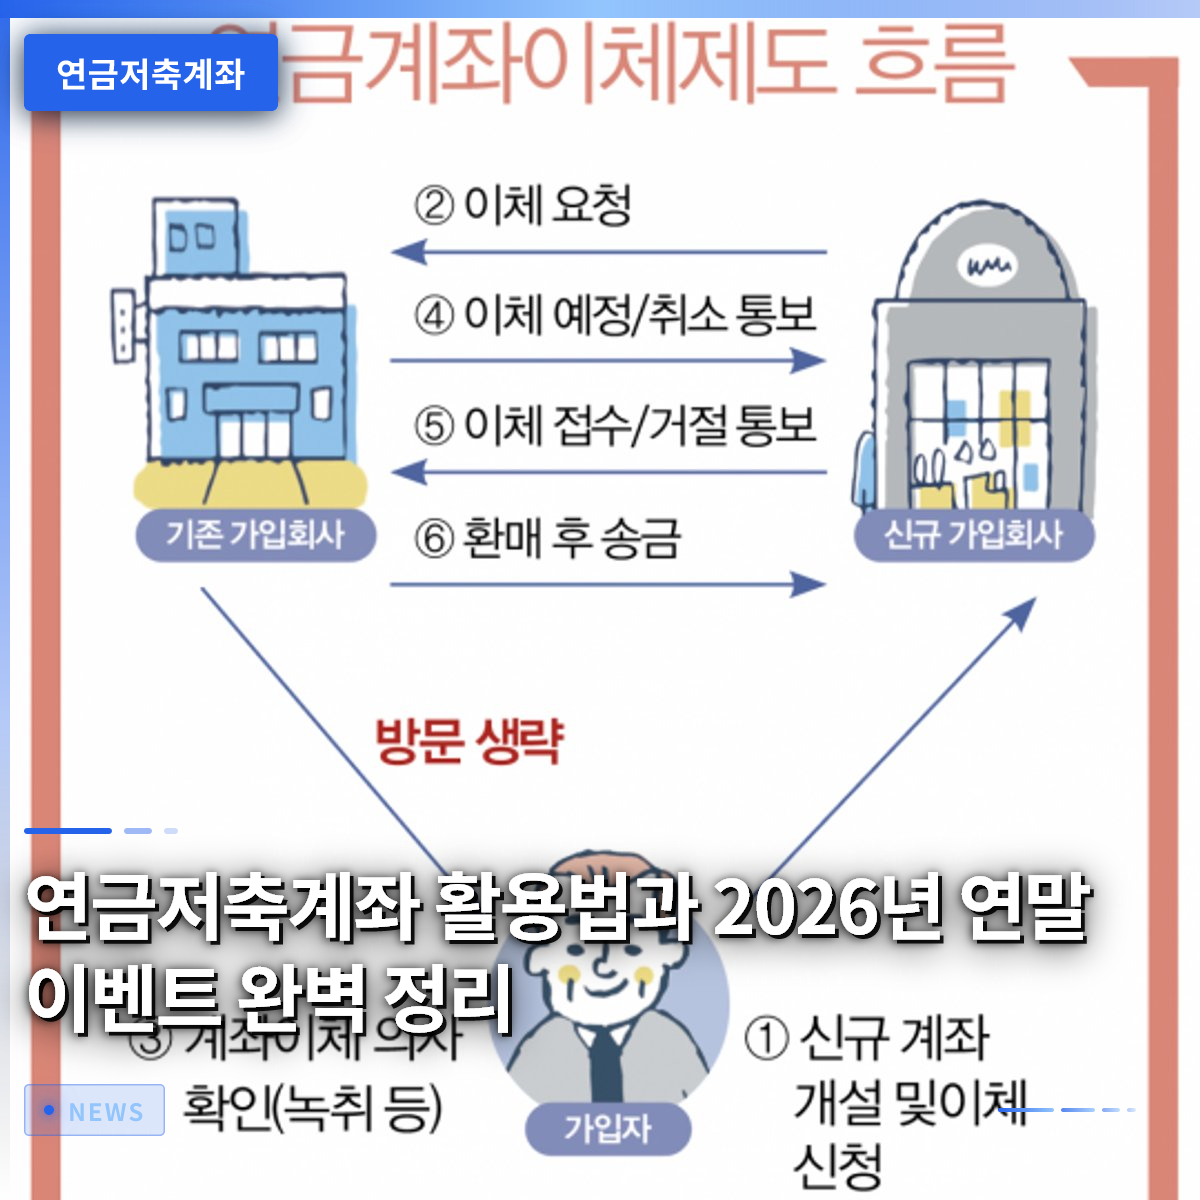
Pension savings accounts are the most practical financial product for preparing retirement funds while enjoying tax deductions. This year, for the 2026 year-end, KB Securities is running a major event offering gift certificates worth up to 1.5 million won to customers who meet the net deposit criteria. By utilizing this alongside Individual Retirement Pensions (IRP), you can double the tax-saving effect. This article first explains the basic concepts of pension savings accounts and the tax deduction mechanism. It then guides you step by step through the specific event conditions and participation methods for KB Securities. Finally, it presents the optimal strategy for combining pension savings accounts and IRPs, using real-world examples.
=
How to Utilize Pension Savings Accounts and a Complete Guide to the 2026 Year-End Event
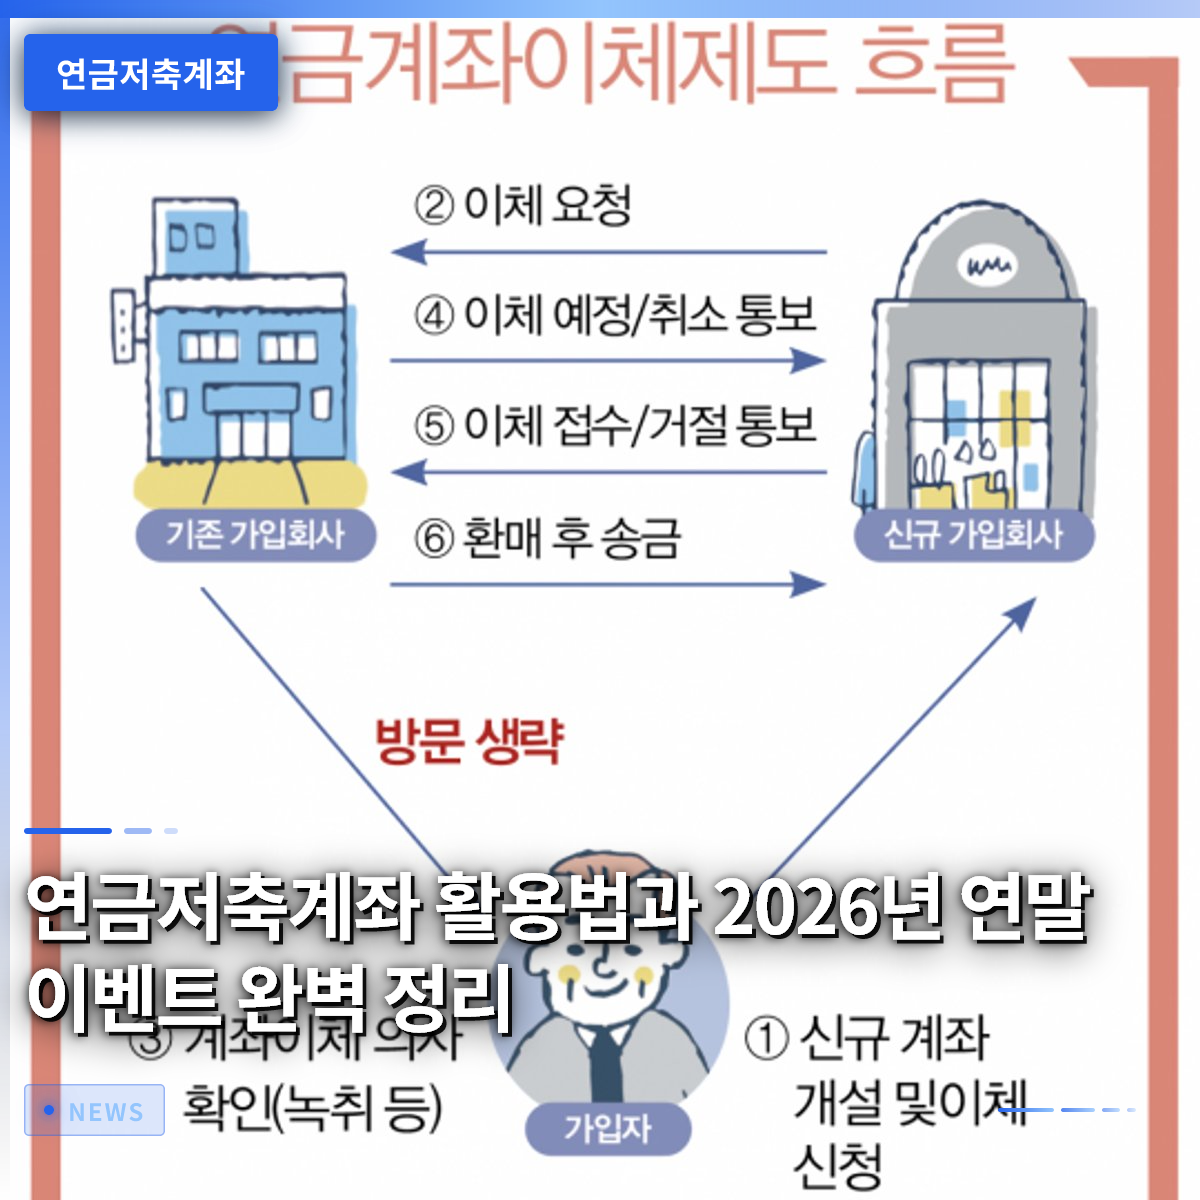
1. What is a Pension Savings Account?

A pension savings account is a financial product that allows individuals to freely contribute and accumulate funds for retirement. You can receive a tax deduction of up to 4 million won annually on your contributions, making it particularly advantageous for employees with high income tax rates. The tax deduction rate is 15% if total income is 50 million won or less, and 13.5% if it exceeds that amount. The deducted tax amount is either refunded or offset during the following year’s comprehensive income tax filing. Opening an account is easy and can be done non-face-to-face at various financial institutions such as banks, securities firms, and insurance companies. You can choose between automatic transfers or manual deposits, and you can adjust the amount at any time.
A pension savings account is a versatile product that reduces immediate tax burden through deductions while preparing retirement funds.
2. Overview of KB Securities’ 2026 Year-End Net Deposit Event

KB Securities is implementing a net deposit event for pension savings account and IRP customers until December 31, 2026. To meet the conditions, you must record a net deposit of 6 million won or more in your account within the year, with at least 1 won of that amount being a personal contribution. Customers who satisfy these conditions will receive a 20,000 won coupon for purchasing pension-specific Exchange-Traded Funds (ETFs). Additionally, for IRPs, young customers (born between 1991 and 2011) who open their first account will receive a separate benefit worth 10,000 won. Customers who have already deposited funds during the event period will have their deposits aggregated and included in the review. The maximum benefit can accumulate up to 1.5 million won, paid in stages as multiple net deposit milestones are achieved.
KB Securities’ year-end event is a prime opportunity to receive cash coupons if you achieve a net deposit of 6 million won or more with at least 1 won in personal contributions.
3. Event Participation Steps and Precautions
First, log in to the KB Securities website or mobile app and find the event application menu. On the application screen, complete identity verification and select either a pension savings account or an IRP account. After selection, click the inquiry button to check your net deposit amount for the current year. If your net deposit is less than 6 million won, you must plan additional deposits to reach the target amount within the remaining period. Deposits can be made via bank transfer or automatic transfer and are reflected in the system immediately upon completion. Once the deposit is complete, you will automatically be reviewed for benefit eligibility on the event page. If eligibility is confirmed, a coupon code will be sent to your registered contact information. This coupon can only be used when purchasing ETFs within KB Securities.
Event participation follows the sequence of application → net deposit check → additional deposit → automatic benefit payment. Be careful not to miss the deposit timing.
4. Differences and Synergy Between Pension Savings Accounts and IRPs
Pension savings accounts have a purely individual pension character, with separate limits for contributions and tax deductions. IRPs are designed to allow employees to continue growing their severance pay without early withdrawal, and may include employer contributions. Both products offer tax deduction benefits, but IRPs can only be joined by those with employment income, and employers may match a certain amount. Pension savings accounts offer a wider range of investment product choices, whereas IRPs often restrict investments to stable assets above a certain level. Therefore, if you want to maximize tax deductions while maintaining investment freedom, it is effective to use pension savings accounts as your primary vehicle and IRPs as a supplement. By splitting contributions between the two accounts, you can combine the annual tax deduction limits to receive deductions of up to 9 million won (4 million won for pension savings + 5 million won for IRP).
Pension savings accounts offer high investment freedom, while IRPs may offer employer matching benefits, so combining them according to your goals is beneficial.
5. Real-World Case: Employee A’s Year-End Strategy
Mr. A is an employee with an annual salary of 60 million won who has been automatically transferring 300,000 won per month to his pension savings account. With a cumulative contribution of 3 million won by October, he can meet the 6 million won condition by depositing an additional 3 million won in the remaining two months. After seeing KB Securities’ event announcement, Mr. A planned to deposit 1.5 million won each in November and December. After the deposits, his net deposit automatically exceeded 6 million won, and he confirmed his eligibility for the coupon on the event page. He used the 20,000 won ETF purchase coupon to make a small investment in a fund focused on domestic dividend stocks. Meanwhile, Mr. A also opened an IRP account simultaneously and received an additional 10,000 won benefit for opening his first account. In total, combining tax deduction benefits and event coupons, he gained an economic benefit of approximately 500,000 won by year-end.
As shown in this real-world case, consistently depositing amounts towards your goal makes it easy to meet event conditions and enjoy additional benefits.
6. Future Outlook and Recommendations for Readers
Tax benefits are likely to be maintained for the next few years, and even during periods of rising interest rates, pension savings accounts can defend real returns thanks to the fixed benefit of tax deductions. Therefore, it is advisable for current employees or freelancers to set annual contribution goals and review them quarterly. Other securities firms besides KB Securities also frequently run similar net deposit events, so it is useful to compare them if you hold multiple accounts. Since employer matching ratios for IRPs vary by company, it is important to check your employer’s welfare policies and utilize them to the fullest. Finally, to prepare for potential tax law amendments, it is wise to re-check the latest tax deduction limits and conditions at the beginning of each year to avoid disadvantages. Log in to your account now to check your deposit status for this year, and if you are short of the target, make a plan and start depositing.
Consistent monitoring and planned deposits are the key to enjoying the maximum benefits of pension savings accounts.
Frequently Asked Questions
=