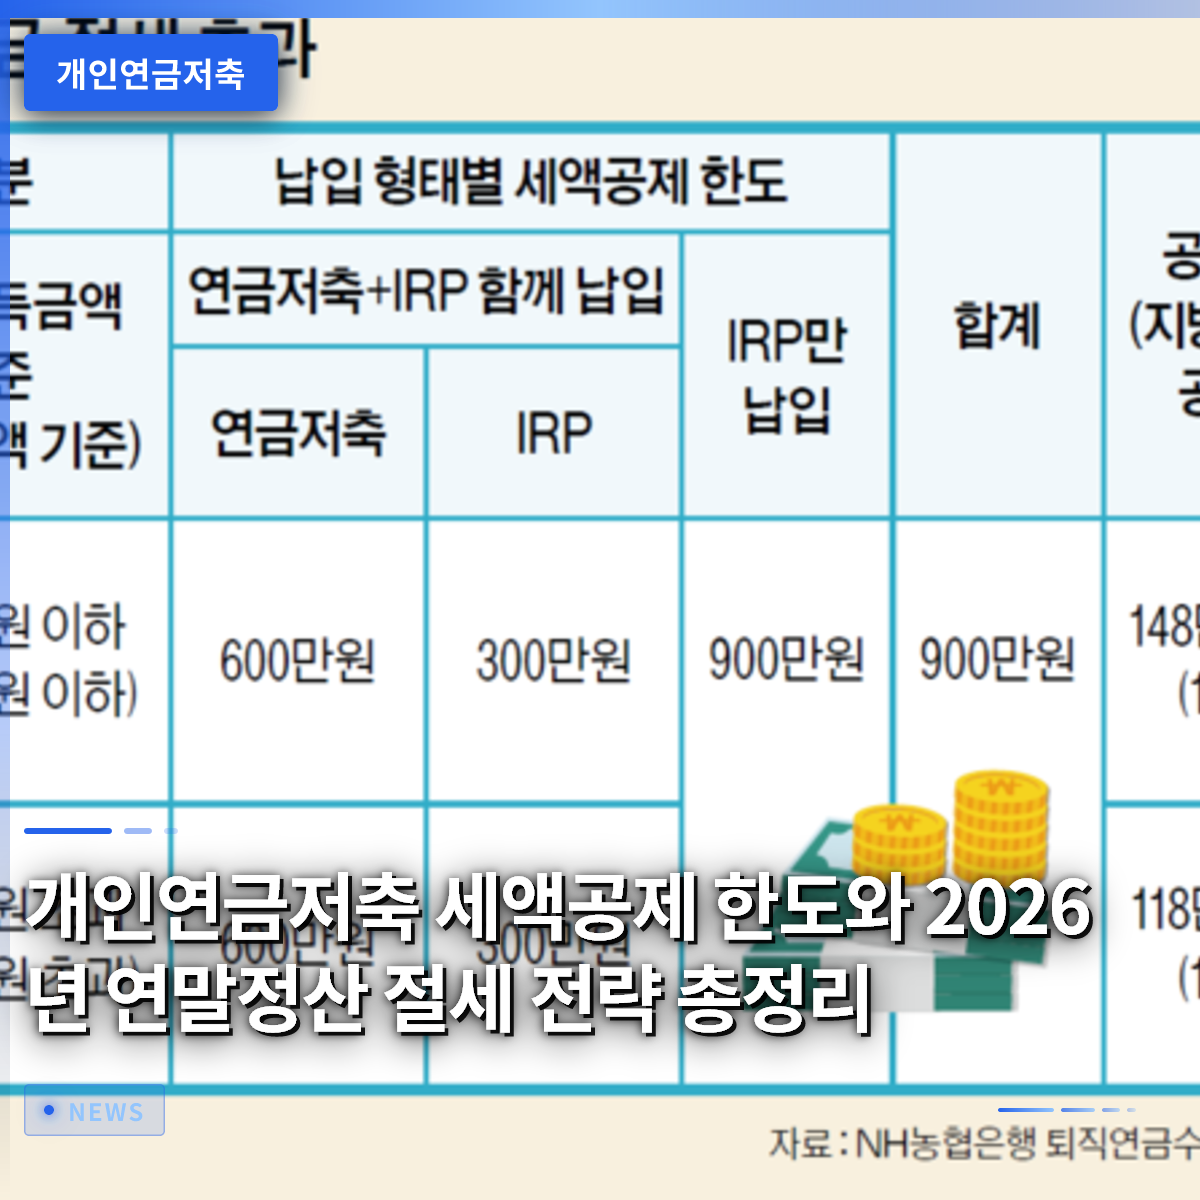
If you contribute 6 million won annually to a personal pension savings account, you can receive a tax refund of up to 990,000 won during the year-end tax settlement, making it an essential financial tool for office workers. Last year, my colleague Min-su was shocked when he saw his year-end tax settlement statement. He received a refund of 790,000 won in his bank account thanks to pension savings, which he had previously paid little attention to. Although he had ignored advice from friends to start saving, receiving a lump sum refund made him realize its importance, and he has since set up a consistent monthly automatic transfer. The personal pension savings system is a program that allows you to achieve both retirement preparation and tax savings. However, when you try to start, it can feel complicated, from understanding tax deduction limits to selecting the right product, causing many to hesitate. In this article, we will look in detail at the exact limits and tax deduction benefits of personal pension savings as of 2026, as well as practical tips for saving on taxes.
=
Personal Pension Savings: Tax Deduction Limits and 2026 Year-End Tax Settlement Savings Strategies
1. Tax Deduction Limits and Benefit Structure

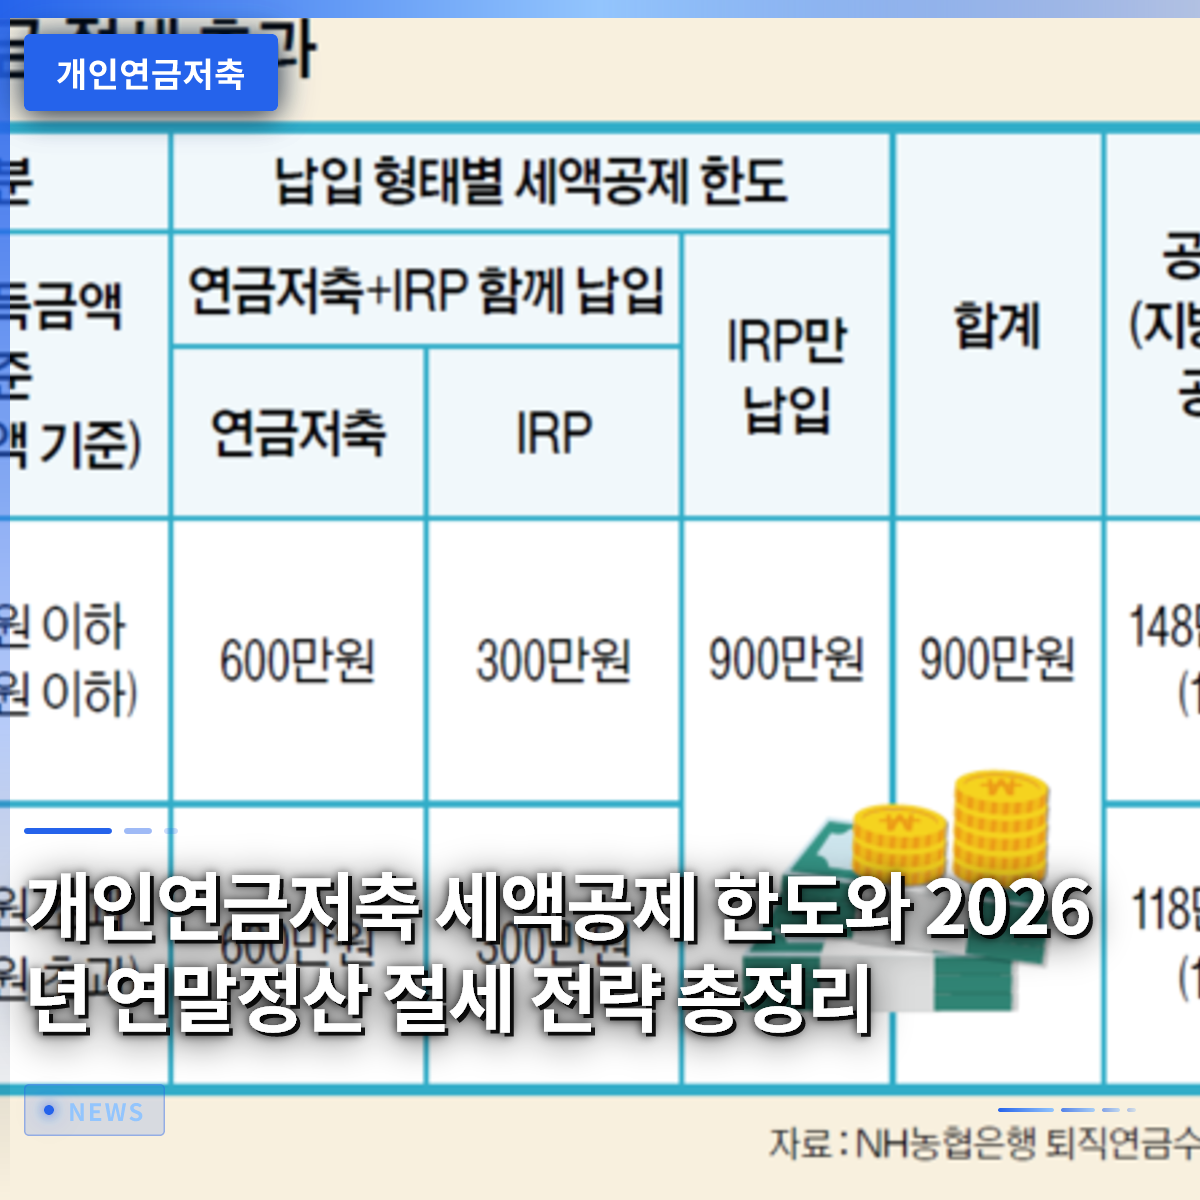
For a standalone personal pension savings account, the annual contribution limit eligible for tax deductions is up to 6 million won. If you additionally utilize an Individual Retirement Pension (IRP) account, the combined total limit increases to a maximum of 9 million won. Employees with an annual salary of 50 million won or less are subject to a 16.5% deduction rate, allowing them to receive a tax deduction of up to 1,485,000 won. If your total compensation exceeds 50 million won, a 13.2% deduction rate applies, enabling you to claim a refund benefit of up to 1,188,000 won.
Some acquaintances mistakenly believe that any amount contributed will be fully refunded, leading them to contribute amounts exceeding the limit. Contributions exceeding the tax deduction limit can be carried over to the following year for deduction or used to reduce the tax burden upon pension receipt, but the tax-saving effect for the current year is only recognized up to the limit. Therefore, it is advantageous to carefully consider your salary level and financial capacity, then consistently contribute an appropriate amount via monthly automatic transfers.
You can receive tax deductions of up to 6 million won for a standalone personal pension savings account, or up to 9 million won when combined with an IRP account.
2. Differences Between Pension Savings Insurance and Pension Savings Funds

Pension savings are broadly divided into insurance products that guarantee stable interest and securities firm funds that allow you to directly choose from various investment products. Last year, Young-hee, who had joined a pension savings insurance plan at a bank, decided to transfer her account to a securities firm’s pension savings fund because she felt the return rate was too low considering inflation. While insurance products offer significant psychological peace of mind due to principal protection, they may fall short in terms of long-term returns during periods of rising prices like the current one.
On the other hand, pension savings funds managed by securities firms allow you to invest directly in various domestic and international Exchange-Traded Funds (ETFs) or equity products, making them suitable for growing your assets. However, due to the nature of investment products, there is a risk of principal loss, so you must carefully consider your investment profile. Rather than blindly investing in high-risk products just because you hear others are making high profits, you should choose assets that you can consistently hold until retirement.
Choose an insurance company if you want principal protection, or a securities firm fund if you seek higher long-term returns.
3. How to Utilize the Transfer System to Other Financial Institutions

If you are not satisfied with the return rate of the product at your current financial institution, you can transfer your account to another institution without canceling it. If you cancel your existing product midway, you must return the tax deduction benefits you have received and pay miscellaneous income tax, so you should never cancel and rejoin. You can easily complete the process by checking your current enrollment details through the Financial Consumer Information Portal or the Integrated Pension Portal, then visiting a new financial institution to fill out a transfer application.
In fact, office worker Min-su also transferred his entire assets to another securities firm because he was dissatisfied with the fee structure of the firm he had previously joined. By using the account transfer system, your existing contribution period and tax deduction benefits are fully carried over to the new account, so you incur no tax-saving loss. Following the guidance of the staff at the new financial institution, you submit the documents and wait about one week (business days) for the transfer procedure to be smoothly completed.
You should use the transfer system to other financial institutions instead of canceling midway to safely move your account without tax disadvantages.
4. Checking Items to Prevent Omissions in Year-End Tax Settlement
Every year, there are repeated cases where people are shocked to find that their pension savings records do not appear in the year-end tax settlement simplification service, despite saving diligently. Last year, during the year-end tax settlement, office worker Ji-hyun discovered that her pension savings contributions were not reflected while checking the tax deduction certificate, causing her to break out in a cold sweat. It turned out that when she opened a new account at the end of the previous year, she had only applied for automatic transfers but failed to consent to the provision of data to the National Tax Service’s simplification service.
To prevent such situations, you must directly verify that the income deduction certificate has been properly registered through the financial company’s website or customer service center before the year-end tax settlement period each year. If it does not appear, you can contact the financial company to issue the document for transmission to the National Tax Service and submit it to your company’s HR department to receive a remedy. To prevent minor mistakes, it is necessary to keep notifications enabled for your financial institution and develop the habit of checking documents before the year-end tax settlement season.
If your records do not appear in the year-end tax settlement simplification service, you must check your consent status for National Tax Service provision and the document registration status with the financial institution.
5. Tax Savings Strategies for Self-Employed Individuals and Freelancers
Pension savings accounts are an excellent tax-saving tool that reduces the burden of comprehensive income tax not only for office workers but also for self-employed individuals and freelancers. A cafe owner I know used to sigh every year during comprehensive income tax filing due to high tax rates, but after starting pension savings on expert advice, she significantly reduced her tax burden. Self-employed individuals with business income can maximize tax savings by simultaneously utilizing income deduction products like the Yellow Umbrella Pension and the tax deduction benefits of pension accounts.
When running a business, cash flow can be fluid, making it burdensome to contribute a fixed amount every month. In such cases, it is much easier to use a method where you do not pre-set an annual contribution limit but freely top up your account whenever you have surplus funds. Even if your income is irregular, you can enjoy the dual benefit of preparing for retirement from a long-term perspective while receiving annual tax refunds.
Self-employed individuals and freelancers can also enjoy effective tax savings benefits through pension savings when filing their comprehensive income tax.
6. Retirement Preparation and Long-Term Outlook
For modern people living in the 100-year age, personal pension savings serve as the most reliable safety net supporting life after retirement. The government is also gradually expanding the scope of tax benefits for pension accounts to mitigate the impact of an aging society. Pension assets accumulated consistently from a young age fill the income gap after retirement and create stable purchasing power.
Even if you start saving solely for the immediate year-end tax settlement refund, it will return as an unexpectedly large lump sum as time passes and the effect of compound interest is added. How about opening the mobile app of your main securities firm or insurance company today to check your pension savings enrollment status and contribution limits? This small step will become the most certain first step toward completing a prosperous and comfortable retirement.
You can achieve both retirement stability and year-end tax settlement savings through consistent contributions and long-term investment.
Frequently Asked Questions
=