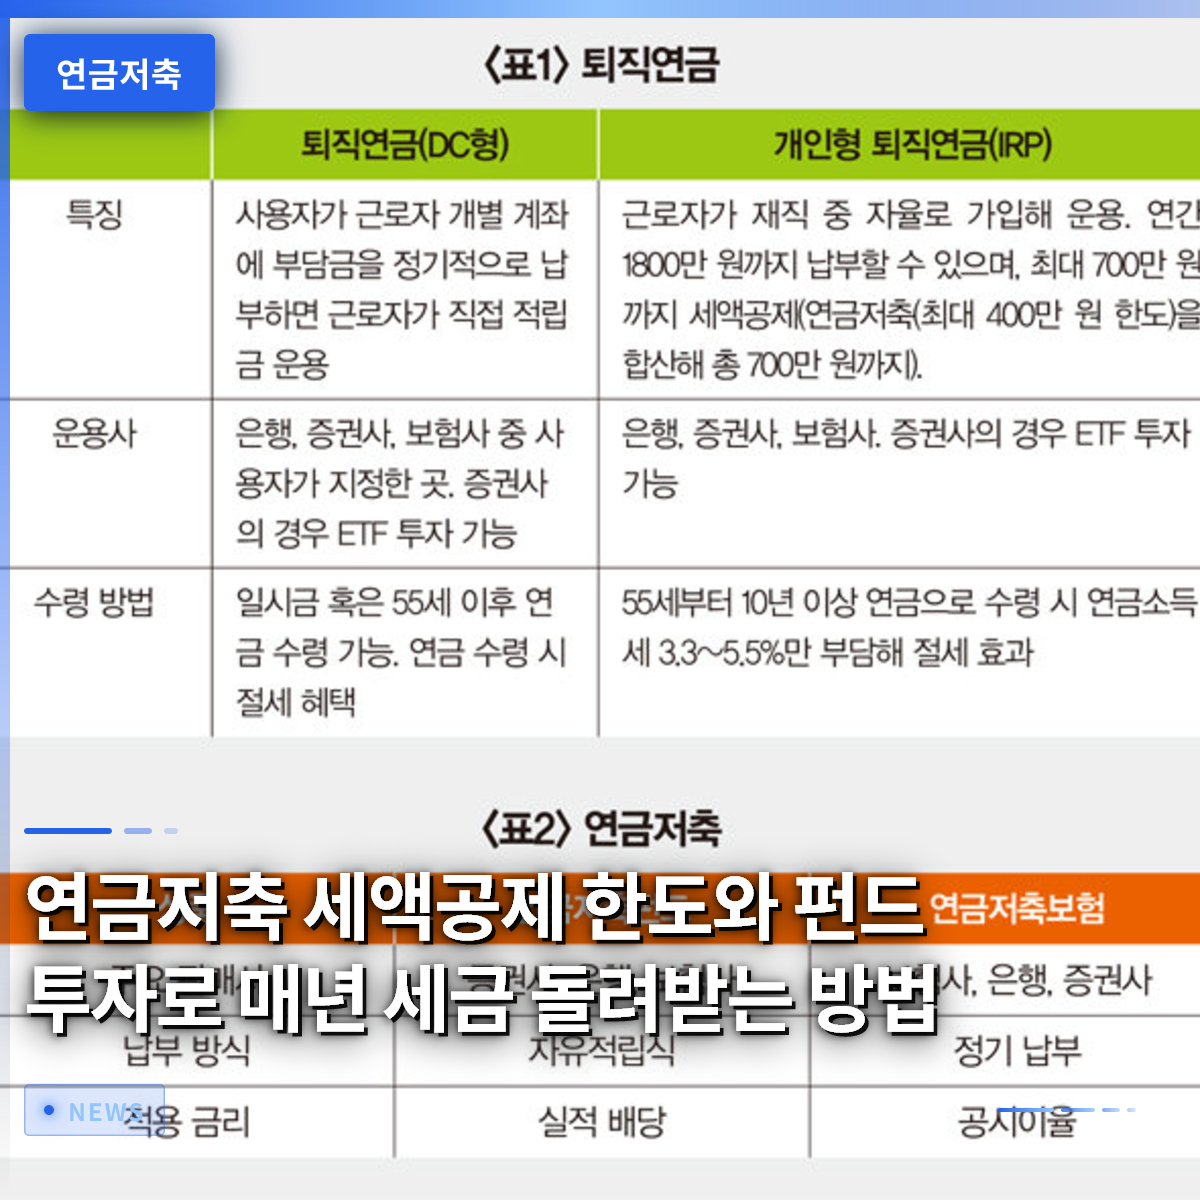
By utilizing a pension savings account, you can receive a tax refund of over 1 million won during your year-end tax settlement, so you should start immediately. Everyone has likely envied a colleague who received a substantial year-end tax refund. In particular, if your total annual income is 55 million won or less, you can benefit from a 15% tax deduction rate, allowing you to get a significant portion of your contributions refunded. Recently, securities firms have also been actively supporting asset management by offering various enrollment events. In this article, we will explore everything about pension savings, an essential tax-saving tool for both employees and self-employed individuals. By reading this article to the end, you will gain specific action guidelines to maximize your year-end tax refund this year.
=
How to Get Annual Tax Refunds Through Pension Savings Tax Deduction Limits and Fund Investments
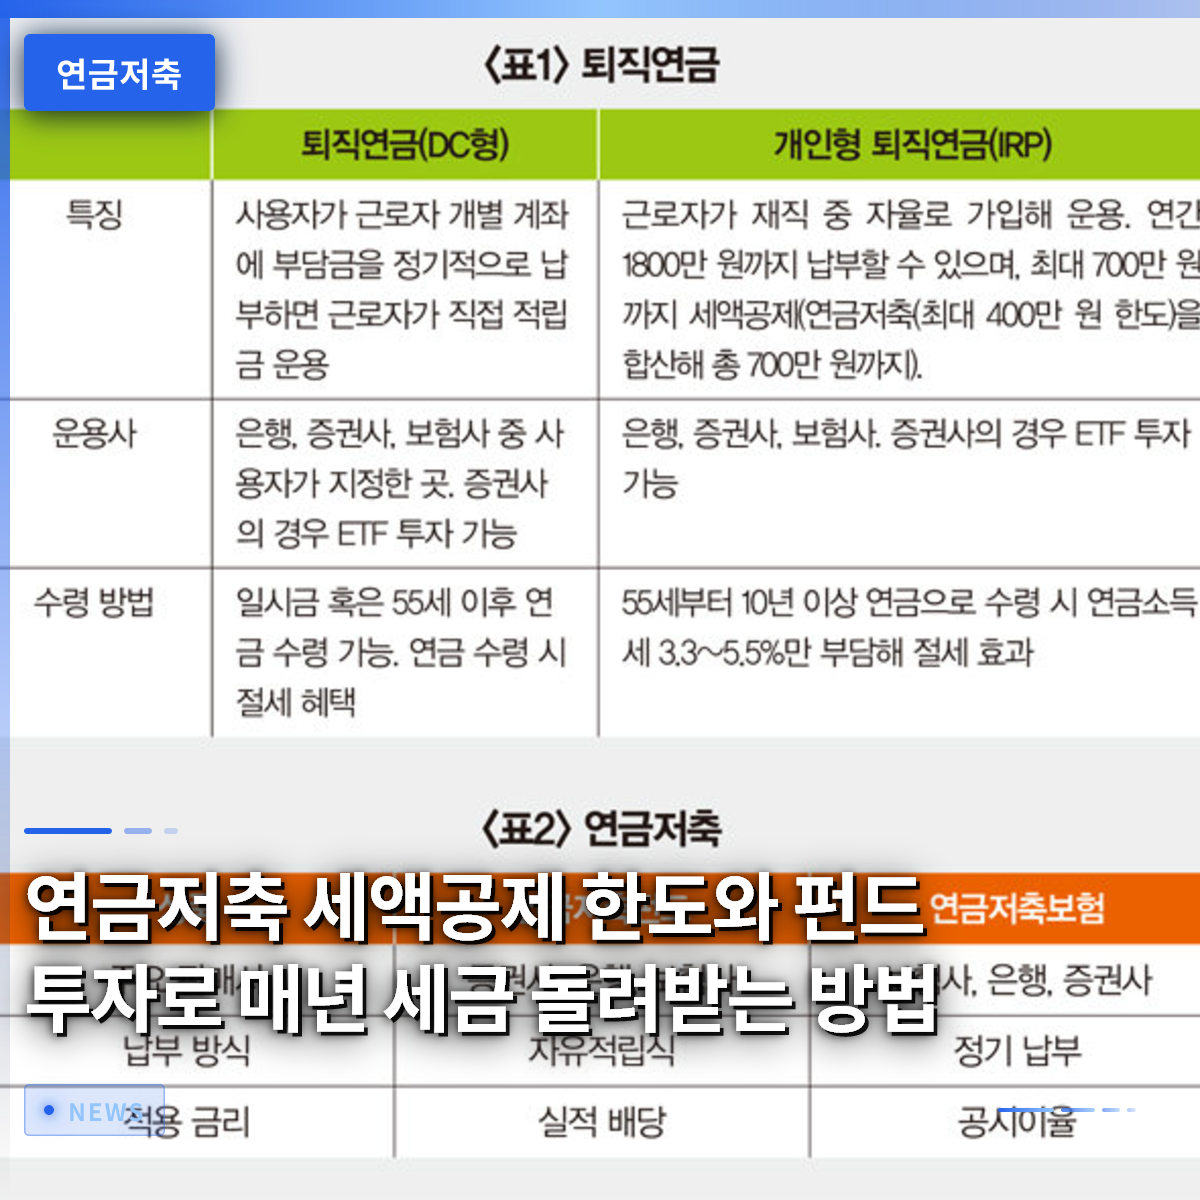
1. Understanding the Pension Savings Tax Deduction Limit and Basic Structure

Pension savings is a legal tax-saving account that refunds a certain percentage of income tax on the amount contributed annually. While many people view it simply as a savings product for retirement preparation, it is essentially a tool for annual tax refunds. According to current National Tax Service guidelines, the tax deduction limit for a standalone pension savings account is 6 million won per year. If you add an Individual Pension Account (IRA), the total limit increases to 9 million won per year. Consistently contributing 500,000 won monthly to reach the 6 million won annual cap can yield significant tax savings for employees.
The applicable deduction rate varies depending on your total annual income, so it is safer to first check your withholding tax receipt. For high-income employees with a total annual income exceeding 55 million won, a 12% deduction rate applies, resulting in a refund of 720,000 won on a 6 million won contribution. Conversely, if your total annual income is 55 million won or less, a higher 15% deduction rate applies, resulting in a tax refund of 900,000 won on a 6 million won contribution. If you max out the 9 million won limit by combining pension savings with an Individual Pension Account, you can enjoy a maximum refund of 1.35 million won based on the 15% rate. For employees who work diligently every month, it is hard to find a more certain and safe return on investment.
Pension savings is an essential tax-saving account that provides a tax deduction benefit of 12% to 15% based on total annual income, within an annual limit of 6 million won.
2. Why Choose Pension Savings Funds Over Bank Products
Some people choose bank trust products to safely preserve their principal, only to suffer the pain of seeing their real assets shrink when inflation is taken into account. In the past, many people enrolled in bank or insurance company products, but recently, there has been a sharp increase in people moving their funds to securities firms’ pension savings funds. A representative example of this trend is a nurse at a general hospital who switched from a mutual aid association system to a securities firm account. The most powerful weapon of this account is its excellent flexibility in asset management and the wide range of product options.
Instead of simply letting money sit idle like in a deposit, you can directly choose stocks or exchange-traded funds (ETFs) or entrust your assets to experts. In particular, investing regularly in ETFs that track U.S. indices over the long term can maximize the effect of compound interest. Asset allocation services and exclusive products recently introduced by securities firms manage portfolios automatically, even for busy employees who do not want to pick individual stocks. To beat inflation and grow retirement funds, you must not stay with the low returns of bank products but should also engage in fund investments.
You should choose pension savings funds over bank products to overcome inflation and achieve long-term compound interest effects through products tracking U.S. indices, etc.
3. The Secret to Enjoying Low Tax Rates When Receiving Pension After Age 55

If you withdraw the funds you diligently saved for retirement all at once, you may face a massive comprehensive income tax bill, so wisdom is needed in how you receive the funds. The true advantage of pension savings is that a magical low-tax benefit is applied when you receive the funds in pension form in installments after age 55, post-retirement. To support citizens’ stable retirement life, the government imposes a low pension income tax rate of 3.3% to 5.5% depending on the pension receipt period. As you get older, the tax rate gradually decreases, allowing you to receive your valuable retirement funds while minimizing the tax burden.
However, be careful: if you withdraw a lump sum at once or withdraw amounts exceeding the pension receipt limit, a 16.5% tax is imposed as miscellaneous income tax. Therefore, it is advantageous to make a long-term plan to receive a fixed amount annually in pension form after retirement. If you contribute consistently every month for 30 years to build a massive asset base and then apply the low tax rate, your actual receipt amount is maximized. Never forget that minimizing the money lost to taxes is the core winning formula for retirement finance.
If you receive the funds in pension form in installments after age 55, a low tax rate of 3.3% to 5.5% is applied, significantly reducing the tax burden.
4. Comprehensive Income Tax Saving Strategies for Self-Employed Individuals and High-Income Employees
This account is an indispensable savior not only for employees but also for self-employed individuals who must file comprehensive income tax returns annually. As business revenue increases, the tax burden grows, causing sighs, but you can avoid a tax bomb using legal tax-saving means. Utilizing pension savings and Individual Pension Accounts simultaneously, along with the Yellow Umbrella Mutual Aid, can lower the taxable standard when filing comprehensive income tax. More and more wise business owners are enjoying the double benefit of diligently running their businesses while reducing taxes.
In fact, looking at self-employed individuals around us, many consult with tax accountants to max out their pension account contribution limits to secure tax benefits. Since the contributed amount is fully utilized as a source for income deductions or tax credits, the actual tax burden decreases noticeably. For self-employed individuals with fluctuating income, this serves as an excellent alternative for managing cash flow while simultaneously preparing emergency retirement funds. True asset management begins not by paying as much tax as possible, but by actively utilizing legally guaranteed systems to protect your assets.
Both self-employed individuals and high-income employees can legally reduce taxes significantly by actively utilizing pension accounts when filing comprehensive income tax returns.
5. Tips for Utilizing Securities Firm Events and Asset Allocation Services
Recently, many securities firms are aggressively promoting pension savings account transfers and new account openings with various benefits to attract customers. Even if you are currently enrolled with another financial institution, you can switch to a securities firm with lower fees and better benefits through a simple account transfer process. If you make good use of event periods, you can also secure small side income such as mobile gift certificates or investment support funds, achieving a double benefit. If you are afraid to pick stocks yourself, it is a wise approach to utilize wrap accounts where experts handle asset allocation for you.
Using securities firm exclusive products or robo-advisor services, your portfolio is automatically and periodically adjusted according to market conditions. This prevents the mistake of hastily selling due to anxiety during stock market downturns, serving as a reliable partner for long-term investment. You should carefully review ongoing events on securities firm websites or mobile apps to find the most favorable conditions for you. Small attention and effort can create a miracle that completely changes the scale of your retirement assets in 10 or 20 years.
By utilizing various new enrollment events from securities firms and expert asset allocation services, you can grow your assets more conveniently and advantageously.
6. Action Guidelines for Successful Retirement Preparation
Now that we have reviewed the tax deduction benefits of pension savings and fund investment strategies, it is time to take actual action. Retirement preparation is too late if you postpone it until you have some spare time, so it is important to execute it immediately. Start by setting an appropriate amount that is not a burden monthly and setting up automatic transfers. As time passes, the magic of compound interest will work, and you will witness an unimaginably large asset accumulating in your account.
As holidays or year-end approach, various notices and event information from financial companies flood in, so you should develop the habit of actively utilizing them. Do not be swayed by flashy investment rumors around you; the safest path is to consistently invest in high-quality index products via regular contributions. The most certain investment for enjoying a comfortable and abundant life after age 55 starts with small savings today. From today, make a contribution plan suitable for your income level and build a solid safety net for your future self.
The key to successful retirement preparation is to stop procrastinating and immediately set up automatic transfers to continue regular investment contributions.
Frequently Asked Questions
=