Pension savings funds are the ultimate wealth management product, allowing you to receive tax refunds ranging from hundreds of thousands to over a million won during your annual tax settlement while simultaneously growing your retirement funds. Many people decide to sign up after seeing colleagues enjoy substantial tax deductions every year, but they often fail to even get started due to confusion over which brokerage to choose and which stocks to buy. Mr. Kim, an office worker, regretted missing out on tax benefits last year, but this year he finally opened a pension savings fund account and started systematic investing. In this article, we will cover everything busy professionals are most curious about, from tax refund rates to criteria for choosing a brokerage and strategies for investing in exchange-traded funds (ETFs) to boost returns. Instead of complex financial jargon, we will explain using everyday examples, so please read through carefully to the end.
=
The Ultimate Guide to Pension Savings Fund Tax Deduction Limits and Tips for Choosing a Brokerage
1. What is a Pension Savings Fund?
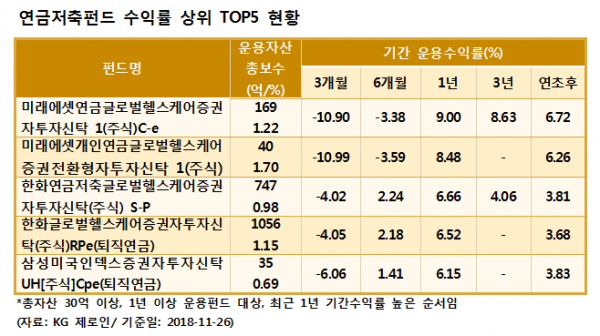
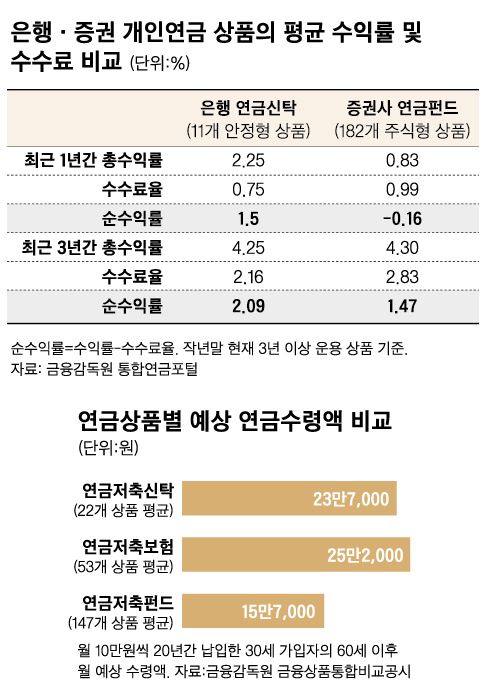
Unlike bank pension savings trusts or insurance company pension savings policies, a pension savings fund is a comprehensive account that allows you to invest in equity products through a brokerage. Similar to a regular stock account, you can directly choose the stocks you like, but its biggest feature is the significant tax benefits provided by the government to encourage retirement planning. You can accumulate funds systematically by setting up automatic monthly transfers, and since you can start with small amounts, it is popular among young professionals. Unlike bank products, principal and interest are not guaranteed, but it has the advantage of defending against inflation and offering the potential for higher long-term returns. The reason people recommend pension savings funds is precisely this special tax benefit and the autonomy in managing funds. Therefore, if you want to grow your assets long-term until retirement, this is an essential account to have. The key to success with pension savings funds is the mindset to consistently invest for over ten years without being swayed by market volatility. It is far more advantageous to approach this with the perspective of creating a stable cash flow for your retirement rather than focusing on immediate returns.
A pension savings fund is a long-term retirement preparation account that allows you to invest in stocks and ETFs through a brokerage while enjoying tax deduction benefits.
2. Tax Deduction Benefits and Refund Amounts
The most powerful weapon of a pension savings fund is the tax deduction benefit received during annual tax settlement, with the refund rate varying based on income level. Employees with a total annual income of 50 million won or less receive a refund of 16.5% of their contributions, while those exceeding 50 million won receive a 13.2% refund. For example, if you max out the annual limit of 6 million won, you can receive a direct tax refund ranging from approximately 780,000 won to a maximum of 990,000 won, depending on your income. Additionally, if you combine this with an Individual Retirement Pension (IRP), the total deduction limit increases to 9 million won, resulting in even larger refunds. Mr. Park, an office worker, consistently saves 500,000 won monthly and enjoys the feeling of receiving an unexpected bonus during tax settlement every year. However, be aware that if you close the account midway, you must return all tax benefits received and will be subject to miscellaneous income tax, so you should absolutely avoid early termination. Even if you unexpectedly need money, it is wise to utilize transfer systems or explore collateral loans rather than closing the account. To avoid a tax burden and fully enjoy the benefits, it is most important to maintain the account consistently until retirement.
Pension savings funds offer tax deduction benefits ranging from 13.2% to 16.5% on annual contributions, depending on income.
3. Which Brokerage Should You Choose?
When choosing a brokerage to open a pension savings fund account, you should carefully compare benefits such as fee waivers and the convenience of mobile apps. Most major brokerages waive online trading fees for pension accounts, so you can simply choose the one that is easiest for you to use. It is not just about opening the account; since you must manage the products within it yourself, a platform with an intuitive mobile interface is preferable. Recently, many brokerages frequently run promotions offering coffee coupons or investment support funds for opening accounts non-face-to-face, which can be a small but enjoyable perk. If you are experienced in stock trading, opening an additional pension account on the brokerage app you already use is the most familiar and convenient option. For beginners, it is advantageous to choose a brokerage that offers advice from asset management experts or has well-developed automatic buying features. Since transferring to another brokerage later can be cumbersome, you should carefully consider events and customer service quality when first signing up. Be sure to confirm that the environment allows you to trade various domestic and international products without restrictions, tailored to your investment style.
It is advantageous to choose a brokerage for your pension savings fund that offers convenient mobile usability and waived online trading fees.
4. Building a Portfolio with ETFs
Within a pension savings fund account, you cannot buy individual stocks directly, but you can freely invest in various domestic exchange-traded funds (ETFs) and mutual funds. A common investment strategy is to balance your portfolio with products tracking major U.S. indices or those holding domestic semiconductor companies. For example, if you seek stable growth, you can systematically accumulate an ETF tracking the U.S. Nasdaq 100 index by buying a fixed amount each month. Recently, many products with very low management fees and excellent performance have emerged, gaining great popularity among long-term investors. Some brokerages also offer customized management services where their asset allocation committees meet monthly to review portfolios, which is worth considering. The core of asset management is appropriately adjusting the ratio of equity to bond products according to your investment goals and retirement timeline. Rather than putting all your assets into a single stock, diversified investing centered on high-quality indices to reduce volatility is beneficial for mental health. By setting up automatic purchases on your payday, you can grow your assets without worrying, even amidst a busy daily life.
In pension savings funds, you should systematically invest in high-quality ETFs, such as U.S. indices or domestic semiconductor funds, to aim for long-term growth.
5. Differences Between IRP and Pension Savings Funds
Both pension savings funds and Individual Retirement Pensions (IRP) are tax-saving accounts for retirement, but they differ significantly in the types of investable products and limits on risky assets. Pension savings funds allow up to 100% allocation to equity assets, whereas IRPs have a mandatory safe asset ratio, limiting equity investments to 70%. Additionally, while IRPs have very strict conditions for early withdrawal, pension savings funds have relatively flexible requirements. Managing both accounts simultaneously to reach the annual tax deduction limit of 9 million won is the most popular tax-saving formula among office workers. For young professionals or those who prefer aggressive investing, pension savings funds, which allow a higher equity ratio, are a much more attractive option. On the other hand, employees who want to safely manage their severance pay alongside their retirement funds should consider combining it with an IRP. It is necessary to accurately understand the characteristics of both products and allocate them in a ratio that suits your financial situation and preferences. You should start with surplus funds, as forcing contributions solely for tax benefits can lead to difficulties if you need cash urgently.
Pension savings funds allow up to 100% allocation to risky assets, whereas IRPs require maintaining a safe asset ratio of at least 30% (limiting risky assets to 70%).
6. Practical Strategies for a Successful Retirement
Pension savings funds are not a speculative tool for making quick money, but a solid shield for a prosperous retirement 10 or 20 years from now. The most important thing is the bold action of opening an account on a brokerage app today and starting your first contribution, even if it is a small amount. Those who set up automatic transfers on a fixed date each month and steadily accumulate assets without being shaken by market fluctuations will ultimately win. If you consistently enjoy the definite reward of tax deductions while benefiting from compound interest, you will have significantly larger assets than expected by the time you retire. Rather than being swayed by rumors or chasing events, please establish your own clear investment principles and consistently manage your account. The small seeds of savings you plant now will undoubtedly become the most reliable and warm comfort for our future selves. When receiving your pension after retirement, a lower pension income tax rate is applied, allowing you to use your retirement funds with minimized tax burden. We hope you will take the first step toward a happy and stable future with a pension savings fund starting today.
Pension savings funds truly complete tax savings and retirement preparation only when practiced from a long-term perspective through automatic transfers and systematic investing.
Frequently Asked Questions
=