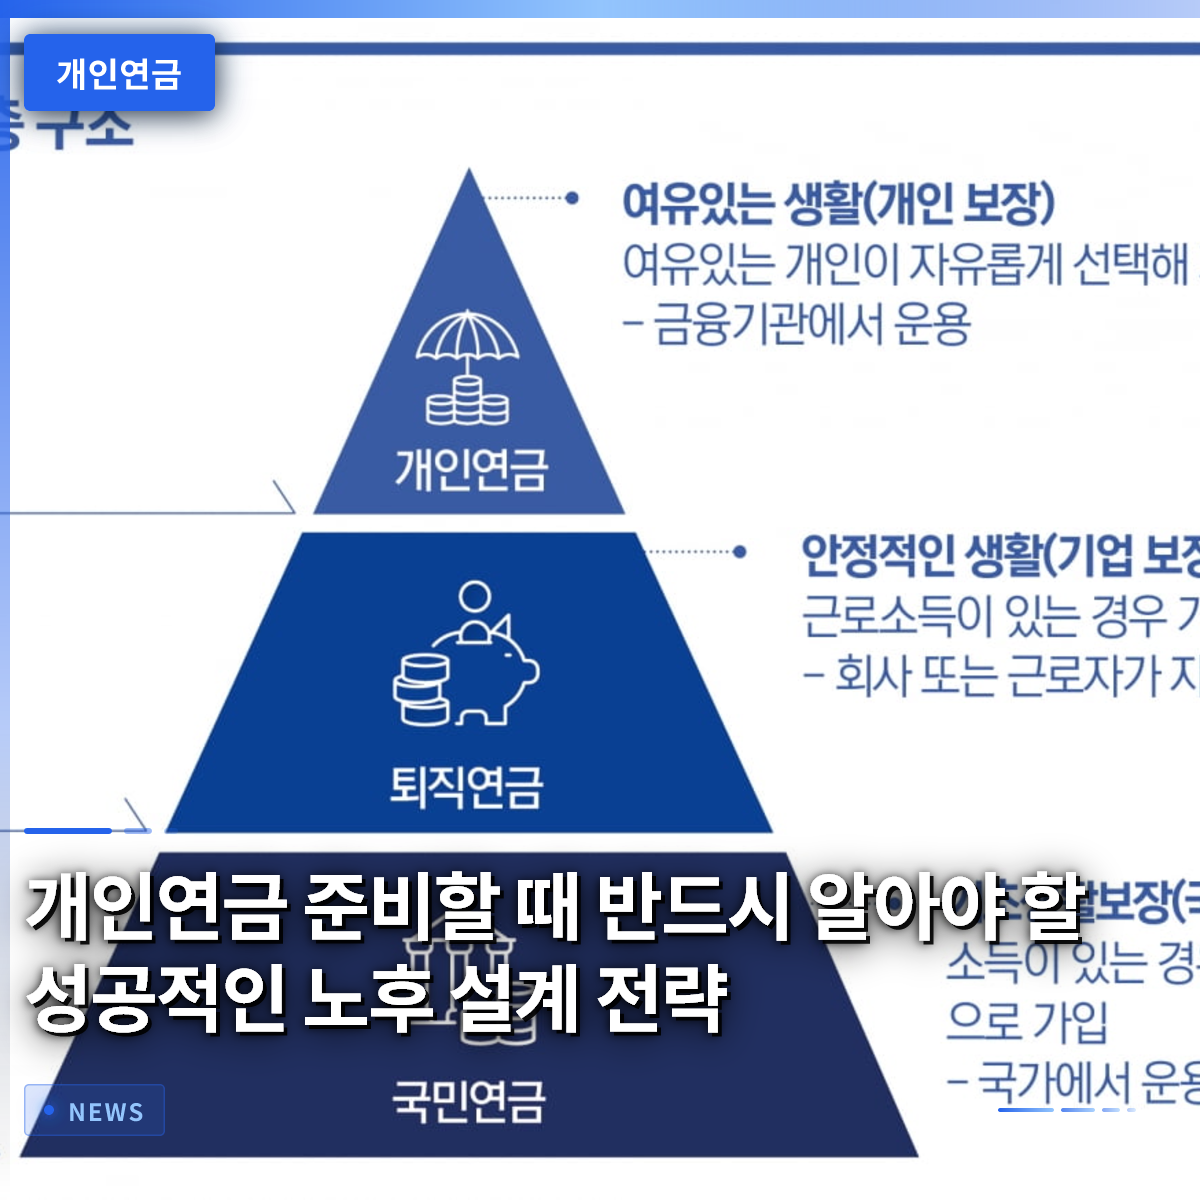
If you want a successful retirement, you must not rely solely on the National Pension; you need to start preparing a personal pension immediately. Many people dream of having over 3 million won in monthly living expenses after retirement, but the cold reality is that the National Pension alone is far from sufficient. As you cover children’s education costs and pay off loan principal and interest, you may suddenly find yourself approaching retirement age in a panic. In fact, it is easy to find people around you who only realize the severity of their retirement situation after turning forty, slapping their foreheads in regret. Therefore, we must organically combine the National Pension, corporate pensions, and personal pensions to build a robust framework for multi-layered asset formation. In this article, we will thoroughly examine realistic pension allocation strategies that ordinary office workers can implement, as well as hidden tax-saving benefits.
=
Essential Strategies for a Successful Retirement Plan When Preparing for Personal Pensions
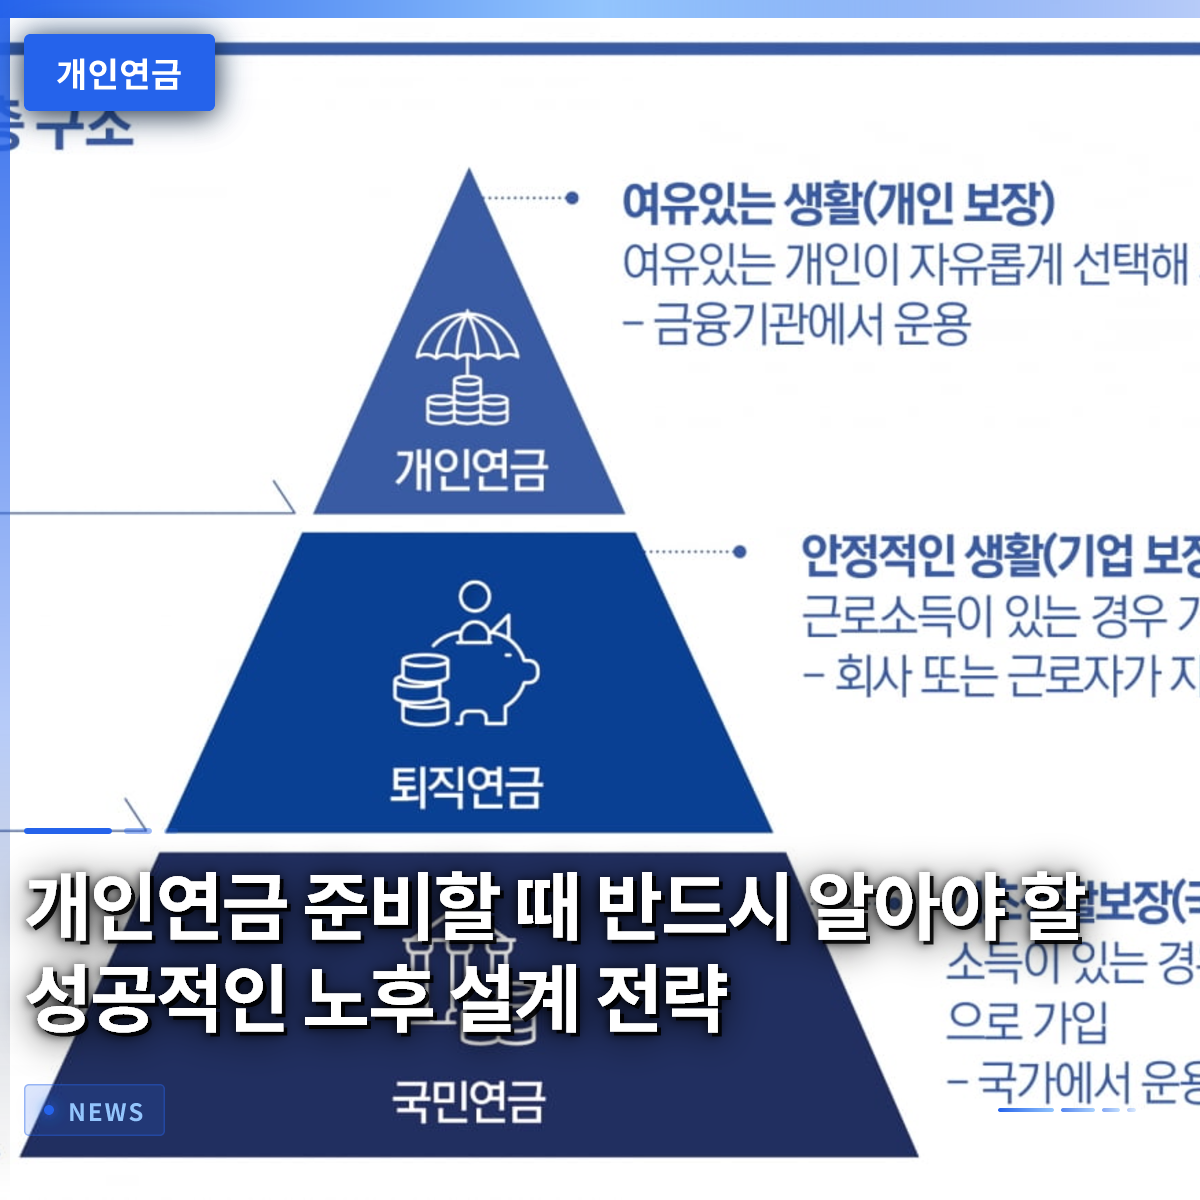
1. Understanding and Utilizing the Three-Tier Pension Structure

To complete a stable retirement, you must steadily build up corporate and personal pensions on top of the solid foundation provided by the National Pension. The state-operated National Pension plays a crucial role as an inexhaustible spring that meets basic minimum needs for food, clothing, and shelter. However, the payment amount is insufficient to fully cope with inflation, so it must be backed by the corporate pension accumulated through your working life. Adding a personal pension, which you voluntarily join, completes this perfect three-tier safety net. Take the story of my friend Minsu, for example. He left his company and left his severance pay in his bank account without a plan, gradually spending it all. He still regrets this decision to this day. While severance pay may look like a lump sum of cash in your pocket, it is actually our precious retirement asset earned through years of hard work. Had he systematically invested it by linking it to a personal pension account, he would likely be enjoying a level of abundance comparable to that of a building owner receiving steady monthly rent. Therefore, it is essential to accurately understand the unique characteristics of each pension and wisely allocate them according to your financial situation.
You must seamlessly build a three-tier retirement safety net by combining the National Pension, corporate pension, and personal pension.
2. Tax Deduction Benefits and Tax-Saving Strategies

The most powerful and definitive reason to join a personal pension is the significant tax deduction benefit provided during the annual year-end tax settlement. If you want to save even a single won in taxes from your hard-earned income, you should actively utilize pension savings accounts and individual retirement pension (IRP) accounts. Since you can receive a certain percentage of your contributions back, it is effectively no different from the state providing a subsidy to support your retirement. Yeonghee, an office worker who used to sigh over the tax bomb she faced every time she filed her comprehensive income tax return, listened to an expert’s advice last year and maxed out her pension savings limit. As a result, she received a refund of several hundred thousand won during this year’s year-end settlement, finally smiling brightly and proudly sharing the news with her colleagues. In this way, tax deductions act as a magical tool that provides a guaranteed rate of return beyond simple savings. However, if you cancel the pension midway, you must return the benefits received and may also be subject to miscellaneous income tax, so caution is absolutely necessary.
Tax deduction benefits through pension savings and corporate pension accounts are the most reliable tax-saving wealth management tool for office workers.
3. Tips for Selecting Investment Products and Asset Allocation

From stable principal and interest-guaranteed products to highly volatile exchange-traded funds (ETFs), there is a wide variety of investment options available within a personal pension account. Putting all your assets into a single product simply because it offers a high interest rate is extremely dangerous in a rapidly changing financial market. In your younger years, you should actively grow your asset pie by increasing the proportion of equity funds or high-growth equity ETFs. As you approach retirement in your fifties, you should decisively shift to a defensive posture, gradually increasing the ratio of safe assets to protect your wealth. Recently, mobile trading apps equipped with AI analysis features allow you to easily invest in various dividend products worldwide. If you accumulate high-dividend products in your personal pension account that provide steady monthly dividends, living expenses will naturally accumulate in your account after retirement without the need for additional work.
Asset allocation, which appropriately mixes equity assets and safe assets according to your age and investment style, is essential.
4. Protecting Pension Assets in Times of Crisis
As we live our lives, we often face unexpected economic crises or debt adjustment situations that make our hearts sink. When a business fails or excessive debt leads to personal rehabilitation or bankruptcy proceedings, it is terrifying to wonder what will happen to your assets. Fortunately, retirement security assets such as the National Pension, corporate pensions, and personal pensions are strictly distinguished from general property. Courts have established mechanisms to protect a portion of pension assets from compulsory execution to ensure a minimum standard of dignified living and retirement. In fact, Donghoon, who lost everything and fell into despair due to business failure, was able to preserve part of his personal pension thanks to the court’s wise judgment, providing a stepping stone for his recovery. However, since not all assets are unconditionally protected, you must consult deeply with an expert depending on the nature of the product and the contribution period. It is crucial to maintain the habit of carefully checking whether your pension accounts are safely protected, especially during times of crisis.
Even in the process of legal debt adjustment, there is a path for personal pension assets intended for retirement to receive a certain level of protection.
5. Methods for Integrated Family Asset Management
Modern securities apps are going beyond simply assisting with individual stock trading to offer family-oriented management features that cover parents and children. Preparing for retirement alone can feel overwhelming and tiring, but sharing goals and communicating with the whole family makes the journey much more enjoyable. Community spaces that allow you to instill financial concepts in children from a young age and give parents a clear overview of their stable retirement assets are gaining popularity. Ji-hye and her husband, a dual-income couple, have recently actively utilized a family integrated pension management service to fill in each other’s contribution gaps. The wife carefully monitors the tax deduction limits that the husband might miss, and they have experienced the joy of seeing their household’s total assets visibly grow. In this way, pensions are not a lonely battle fought alone, but a warm, shared project to build the future with your precious family. If you actively utilize the various financial platforms that will become even more sophisticated in the future, the difficulty of preparing for retirement will be significantly reduced.
Retirement preparation becomes much easier when the whole family uses an integrated system to share and manage their asset status.
6. Setting Realistic Goals and Ensuring Sustainability
To realistically prepare a large retirement fund of 3 million won per month, you must consistently contribute amounts you can afford to pay right now. Instead of being swayed by news of people making big money in the stock market, it is much wiser to set a monthly contribution amount that you can sustain until the end. If you greedily put in a large amount and then cancel it before even a few months have passed, all your previous efforts will be for nothing. Starting today, try creating a system where you reduce fixed expenses leaving your account and automatically transfer the remaining surplus to your personal pension account. Imagine the future you, smiling brightly ten or twenty years from now, and walk the path steadily without impatience. You must also remember to be diligent in periodically checking your pension account in line with various government policy supports and changes in the financial market. The small seeds of interest and savings you plant now will become a vast, inexhaustible oasis of retirement that will warmly embrace our lives in the future.
The key to success is to abandon excessive greed and consistently contribute an amount you can sustain until the end.
Frequently Asked Questions
=