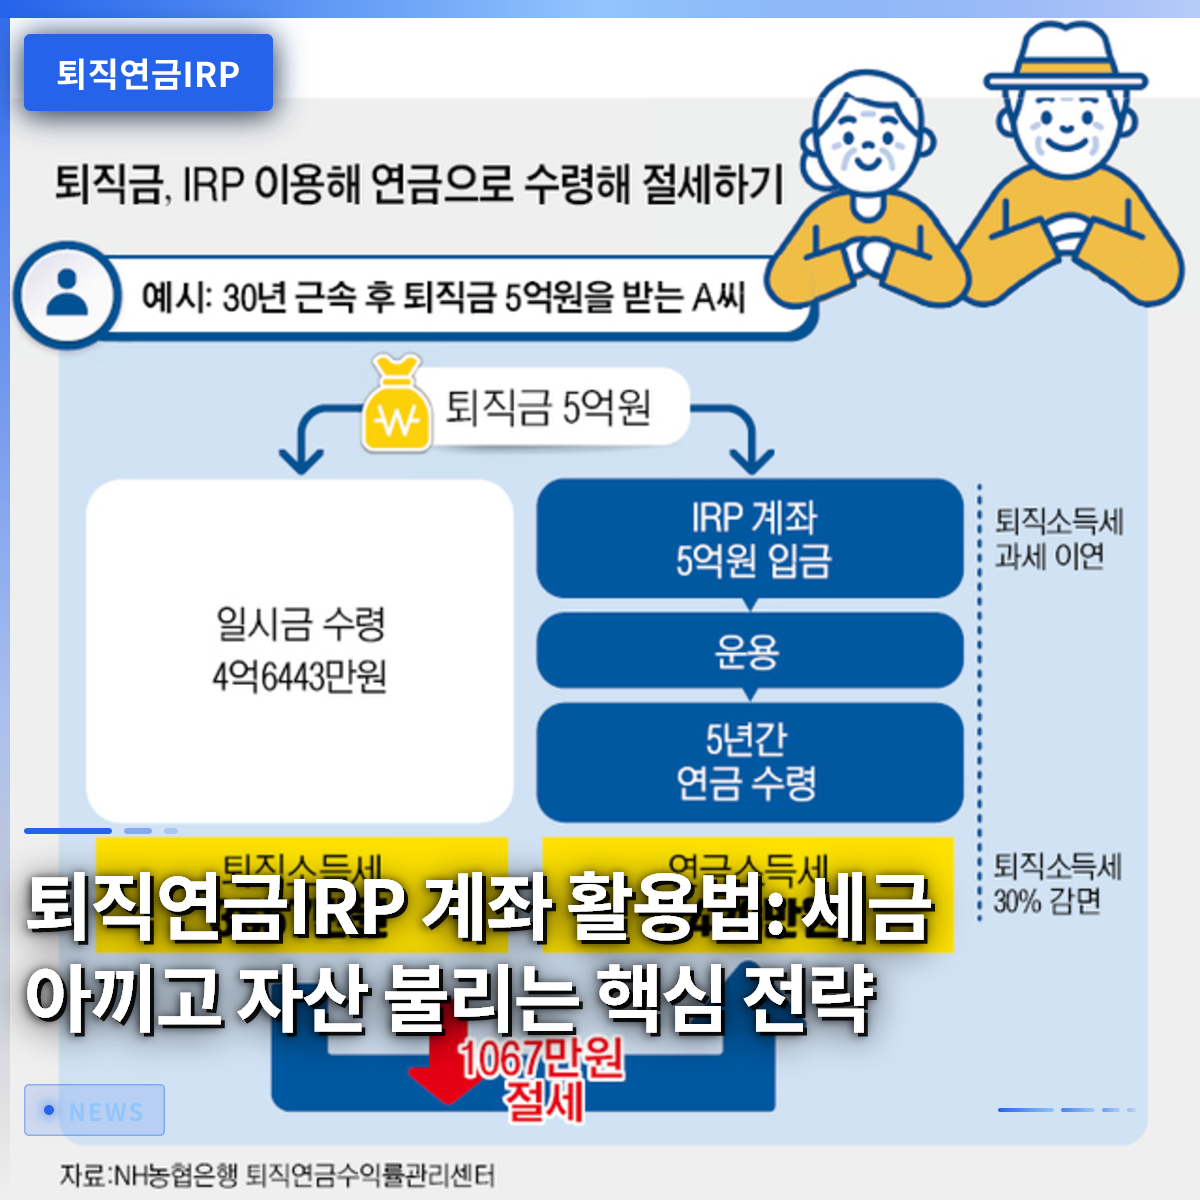
The Individual Retirement Pension (IRP) account is an essential tax-saving tool that every employee should have. If you receive your severance pay in a regular bank account, you will incur significant tax costs. However, if you transfer it to an IRP account, you can defer tax payments, allowing your assets to grow over time. Many employees are unaware of the full benefits of this system and end up losing valuable money to taxes. Today, we will explore in detail how to effectively utilize your IRP account to minimize taxes and build a secure financial foundation for your retirement. By reading this article to the end, you will gain the wisdom needed to protect your valuable assets.
=
How to Utilize Your IRP Account: Key Strategies for Tax Savings and Asset Growth
1. Why You Should Always Receive Severance Pay in an IRP Account

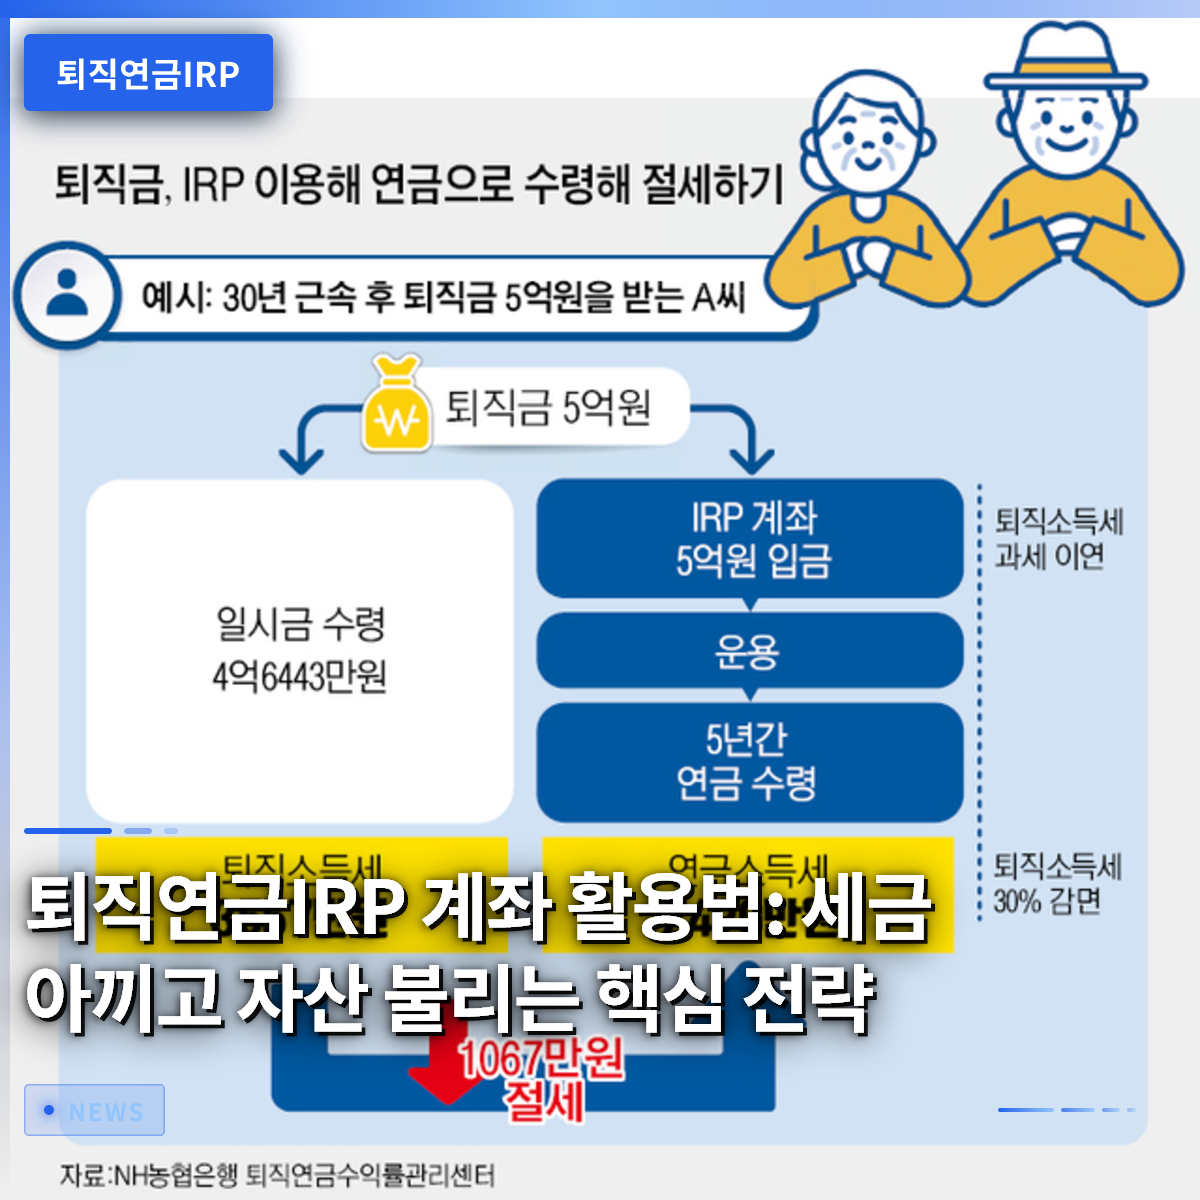
When changing jobs or retiring, you must receive your severance pay in an IRP account to avoid a massive tax burden. Legally, unless there are special circumstances, severance pay is required to be paid into an IRP account in the employee’s name. If you receive your severance pay directly into a regular bank account, you will be subject to withholding tax on your retirement income, significantly reducing the amount you actually take home. In contrast, transferring it to an IRP account allows the funds to be accumulated without immediate tax deduction, enabling you to benefit from compound interest. If you receive this money as a pension over a longer period, you will pay significantly less tax than if you received it as a lump sum. Mr. Kim, an employee approaching retirement, almost received his severance pay from his previous job in a regular bank account. However, following advice from a friend, he opened an IRP account instead. As a result, he was able to avoid paying several million won in taxes immediately and keep the funds in the account to grow. The taxes saved this way will grow over time, eventually transforming into a solid financial cushion for your retirement. While you may be tempted to spend your severance pay immediately upon receiving it, keeping it in the account is far more advantageous in the long run. To fully enjoy the tax benefits, choosing an IRP account at the stage of receiving your severance pay is the wisest first step.
You should receive your severance pay in an IRP account rather than a regular bank account to defer taxes and maximize the effect of compound interest.
2. Tips for Maximizing Tax Deduction Limits and Year-End Tax Refunds

Every year during the year-end tax settlement season, the biggest concern for employees is how to get their taxes back. The IRP account delivers significant tax-saving effects when used in combination with pension savings products. By utilizing both accounts together, you can enjoy tax deduction benefits up to the maximum limit set by law, making them essential products for employees. Because you receive a high percentage of tax refunds on the amounts you have consistently contributed, the perceived benefit is substantial. Even just saving a small amount each month can give you the feeling of receiving a bonus from the government. Mr. Park, an employee who has been interested in saving since he started his career, strives to reach the maximum limit every year during his year-end tax settlement. He developed a strategy of depositing a certain amount into his pension savings and filling the remaining limit into his IRP account. Thanks to these contributions, he receives a considerable refund every winter, which he uses to buy gifts for his parents or fund his travel. Although it may seem like money is leaving your account, you get it back as a year-end tax refund, significantly reducing the actual financial burden. The basic principle of tax planning lies in how thoroughly you utilize the systems that others overlook.
By utilizing pension savings and IRP accounts together, you can enjoy tax deduction benefits up to the maximum limit, thereby maximizing your year-end tax refund.
3. Lowering Fees and Boosting Returns Through Non-Face-to-Face Account Opening

One hidden obstacle to watch out for when investing in financial products is various fees. If you visit a bank branch in person to open an IRP account, you may incur higher fees than expected, which can erode your long-term returns. Recently, it has become common to open or transfer accounts non-face-to-face (online) via smartphone apps. By opening an account or converting an existing one to a non-face-to-face account, you can save significantly on management fees. Even a small difference of 0.1% can make a huge difference in amount over several decades, so it is essential to check the fee conditions. Mr. Lee, an employee, accidentally learned from a bank clerk about converting his existing IRP account to a non-face-to-face type. Upon seeing the noticeably lower fee rate, he nodded in realization, wondering why he hadn’t done it sooner. As your accumulated funds grow, the amount lost to fees becomes significant, making the switch to a non-face-to-face account a necessity rather than an option. It can be handled simply with a few taps on your smartphone screen, making it easy for not only younger generations but also middle-aged and older individuals approaching retirement to follow. Saving on small costs is the most certain way to increase your investment returns.
Opening or converting your IRP account via non-face-to-face methods can significantly lower management fees, thereby increasing long-term returns.
4. Safely Structuring Your Portfolio with Safe Assets and Individual Investor Bonds
When managing your retirement pension account, it is not always best to put all your money into risky stocks. Legally, you are required to maintain a certain percentage of safe assets, so you should appropriately mix in bonds or hybrid products. Recently, the range of options has expanded significantly as Individual Investor Bonds (IIBs) can now be subscribed to directly within IRP accounts. Long-term government bonds, such as 10-year or 20-year issues, can be purchased directly starting from small amounts, making them very popular among investors who prioritize stability. A major advantage is that you do not need to invest a lump sum; you can safely manage your funds by splitting them into smaller amounts. Mr. Choi, an employee who used to suffer greatly every time the stock market fluctuated, recently made significant changes to his portfolio. While adhering to the safe asset regulations within his retirement pension account, he directly included the newly introduced Individual Investor Bonds. Since the government guarantees the principal, he can sleep soundly while also enjoying decent interest benefits. By appropriately allocating between risky assets and safe government bonds, he can maintain peace of mind regardless of market fluctuations. Since safety is the top priority for retirement funds, it is wise to utilize reliable products like government bonds.
By meeting safe asset regulations within your IRP account and utilizing the newly introduced Individual Investor Bonds, you can achieve stable long-term investment.
5. Resisting the Temptation of Early Withdrawal and Enjoying the Benefits of Pension Receipt
During your working life, you may face sudden large expenses that tempt you to break into your savings or pension accounts. In fact, many people withdraw from their IRP accounts prematurely, depleting their valuable retirement funds. However, early withdrawal requires you to return the tax deduction benefits you previously received and also incurs additional income tax, resulting in significant losses. When you urgently need a large sum of money, it is better to carefully review the exceptions allowed by law, such as for home purchases or deposit payments for rental housing, rather than breaking the account. You can only enjoy the true magic of compound interest if you resist the temptation and maintain the account until the end. Seeing colleagues suddenly buy new cars or move to larger houses can make you want to withdraw your funds. However, Mr. Jung, an employee who has steadfastly maintained his IRP account, endured the temptation by thinking about the benefits he would receive when claiming his pension. After retirement, receiving the pension regularly each month results in much lower tax deductions compared to receiving a lump sum, thereby increasing the actual amount received. To fully receive the tax benefits provided by the government, the key is to not give up midway and complete the journey until the pension receipt age. The quality of your life in retirement is ultimately determined by how well you resist immediate temptations today.
Early withdrawal can result in a massive tax burden, so you should resist the temptation and receive your funds as a pension to enjoy maximum tax savings.
6. Practical Strategies for a Successful Retirement with IRP
As we have seen, the IRP account is not just a savings account but a sturdy shield that protects your life after retirement. The formula for success is to properly manage your severance pay into the account when changing jobs, fill the year-end tax settlement limit every year, and lower fees through non-face-to-face methods. Going forward, you need to maintain a mindset of managing your account wisely in line with various changes in government tax policies. Retirement preparation is not achieved overnight but is completed through long-term, consistent attention and practice. Why not start today by checking the status of your IRP account and filling in the gaps one by one? The process of preparing for retirement can feel lonely and overwhelming, but it becomes much easier when you utilize reliable institutional tools. Do not be swayed by rumors; you must cultivate the ability to diversify and manage your assets in the way that is most advantageous for you. Small practices accumulate to create a prosperous and stable life after retirement. Open your smartphone app right now to check your retirement pension status and review your portfolio with the help of expert advice. Start today with the wise choices that your future self will be most grateful for.
By utilizing your IRP account through consistent attention and systematic management, you can complete a prosperous and stable life after retirement.
Frequently Asked Questions
=