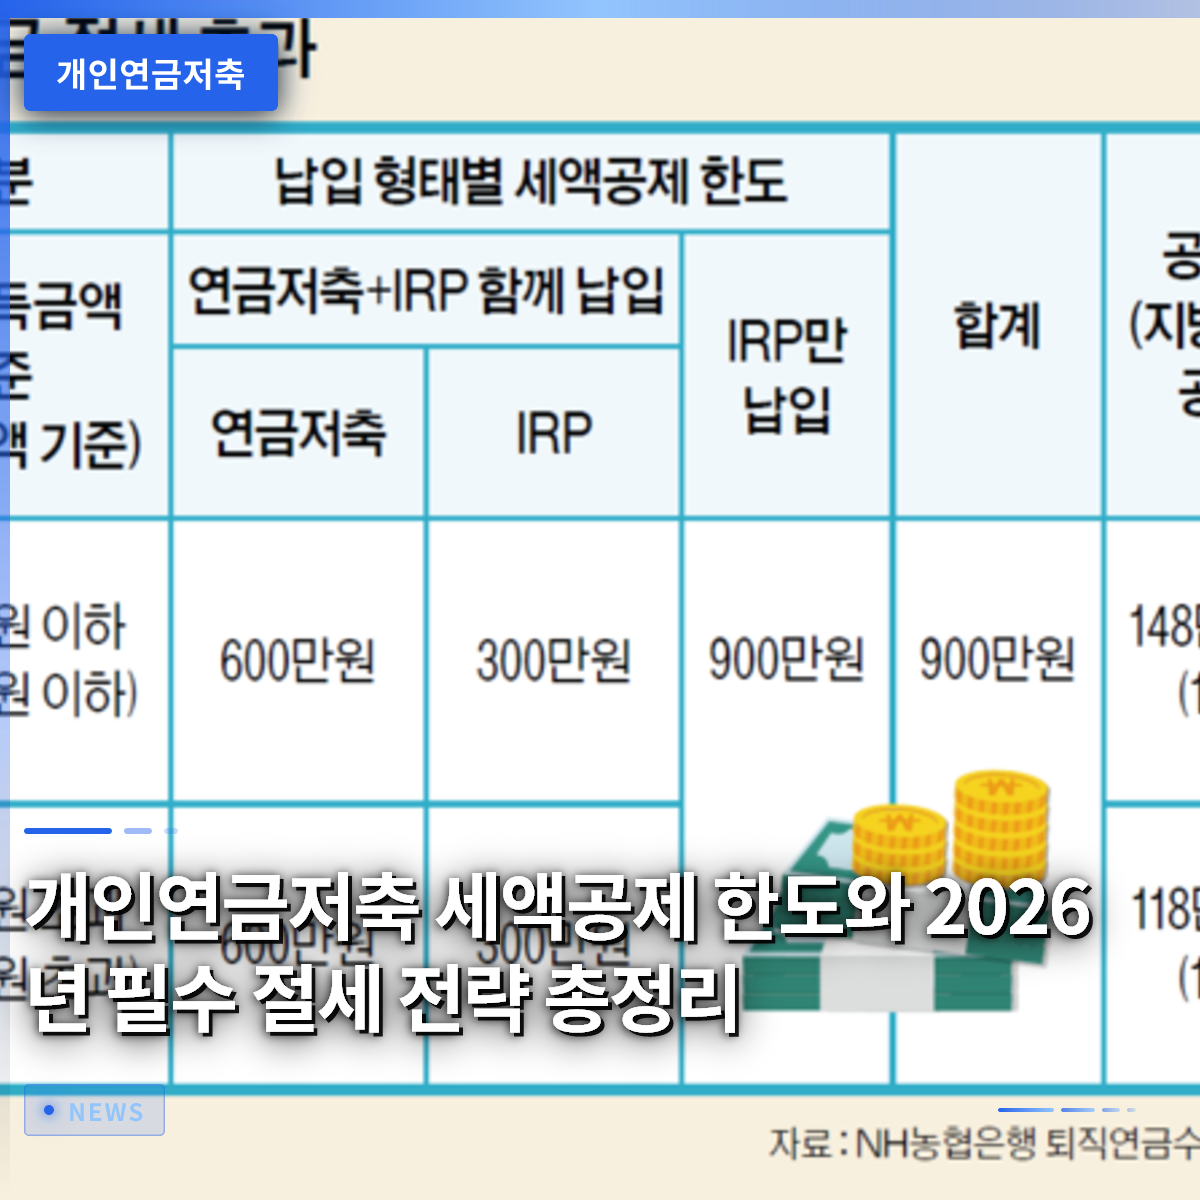
Personal pension savings are an essential tax-saving account for employees, offering tax deductions of up to 9 million KRW annually during year-end tax settlement. If you want to save on the taxes deducted from your monthly salary, you need to review your pension account immediately. You probably remember feeling envious when you saw colleagues receiving additional year-end tax refunds of several hundred thousand KRW. The secret is that they consistently contributed to pension savings funds and individual retirement pensions. In this article, we will thoroughly examine the limits and tax benefits of different pension account types in a way that is easy for beginners to understand. We will look in detail at smart asset management methods that allow you to enjoy the power of compound interest while getting your taxes back.
=
Personal Pension Savings Tax Deduction Limits and Essential Tax-Saving Strategies for 2026: A Complete Guide
1. Differences Between Personal Pension Savings and Pension Savings Funds

Pension savings are broadly divided into pension savings insurance purchased from insurance companies and pension savings funds managed by securities firms. In the past, insurance products offering stable interest rates were popular, but recently, many people prefer securities firm accounts that allow them to invest in stocks or exchange-traded funds (ETFs) themselves. Using pension savings funds offers the advantage of diversifying investments across various global assets while deferring taxation on capital gains. Since even housewives without income or minors can join, it is useful to create accounts for family members to save funds in advance. Setting up automatic monthly transfers helps build a forced saving habit, which greatly aids in asset formation. Instead of just envying acquaintances who boast about high returns from their securities accounts, you should choose the product that suits you. Insisting on high-interest products from the past carries the risk of your real asset value declining as it fails to keep up with inflation. Therefore, it is essential to first determine whether your investment style is stability-oriented or aggressive return-seeking. You can easily open an account non-face-to-face through a securities firm app, so you can complete the preparation anytime, even on weekends. Without complex document submissions, you can create your own tax-saving account in just a few minutes with a smartphone authentication. Once you have set up this account, consistently depositing even small amounts will eventually lead to a smile as you discover your thickened asset balance. We strongly recommend turning on your smartphone right now, accessing a securities firm application, and starting with opening an account.
Pension savings funds are accessible to anyone and are a useful tool for investing in various assets through securities firms while enjoying tax benefits.
2. Tax Deduction Limits and Maximization Strategies
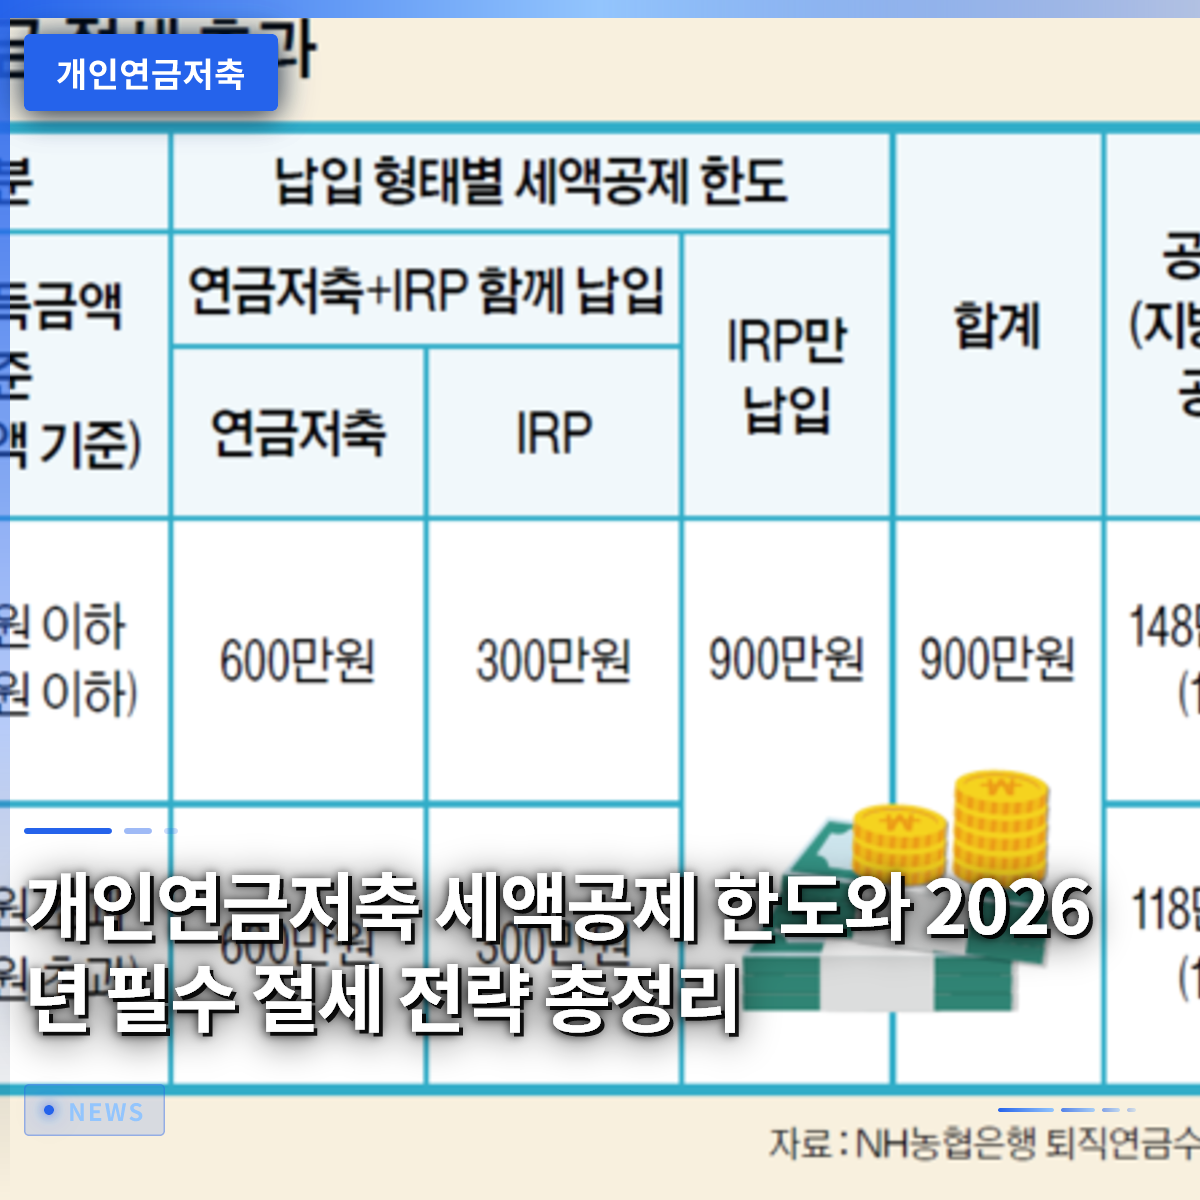
By utilizing both pension savings accounts and individual retirement pensions, you can enjoy tax deduction benefits of up to 9 million KRW annually. Pension savings alone offer a deduction of up to 6 million KRW, but the limit increases to 9 million KRW when combined with individual retirement pensions. If your total salary is 55 million KRW or less, a deduction rate of 16.5% is applied, allowing you to receive a substantial tax refund of up to 1.485 million KRW. Even if your total salary exceeds 55 million KRW, a deduction rate of 13.2% is applied, allowing for a refund of up to 1.188 million KRW. Since the calculation is based on contributions made from January to December, it is more advantageous to pay in monthly installments rather than rushing to deposit a lump sum at year-end. If you want to receive the year-end tax settlement refund that employees call their “13th-month salary,” you must definitely fill this limit. If your colleagues receive generous refunds every year while you are paying out or receiving little, you should review your account contribution records. Trying to find a lump sum to deposit in a rush at year-end can place a heavy burden on your household economy, so you should make a plan from the beginning of the year. If you develop the habit of consistently contributing 500,000 KRW each month, filling the limit by year-end will not be difficult. This is a strong system established by the state to encourage citizens to prepare for retirement, so actively utilizing it is the attitude of a smart consumer. The joy of getting back valuable money that was about to go to taxes becomes a great source of vitality in working life. Right now, open your last year’s tax settlement receipt and check how much tax you paid.
By combining pension savings and retirement pensions to fill the annual contribution limit of 9 million KRW, you can receive a maximum tax deduction refund of 1.485 million KRW.
3. Comparison of Pension Savings Funds and Individual Retirement Pensions

Pension savings funds and individual retirement pensions may look similar, but they show clear differences in eligibility and investment style. Pension savings funds can be joined by any Korean citizen regardless of age or income, so housewives and students also use them. On the other hand, individual retirement pensions are only available to those with income, such as employees, business owners, and public officials who have earned income or business income. There is also a difference in the asset composition ratio of investable products; retirement pensions have a mandatory safe asset ratio of at least 30%. Therefore, if you want to invest 100% in aggressive equity assets, it is much more advantageous to use a pension savings fund account as your main vehicle. Investment experts commonly advise cleverly combining the limits of both accounts to construct the portfolio that best suits you. In your early career, your income may be low, so you might not be able to fill the tax deduction limit, but as your years of service increase, you will realize the value of the limit. As your salary rises, your tax burden also increases, making the importance of tax-saving accounts more emphasized over time. The reason why senior colleagues with rich financial knowledge unanimously advise you to fill your pension accounts first lies here. Do not be intimidated by complex financial terms; it is enough to seriously open one securities firm account in your name. Small actions accumulate to create a significant asset gap in a few years, becoming a sturdy support for your retirement. On your way home from work today, please carefully compare the differences between the two accounts again using a smartphone app on the subway.
Pension savings funds are open to everyone and allow for a high equity ratio, while retirement pensions are for income earners and require maintaining a safe asset ratio.
4. Early Termination Risks and Unavoidable Reasons
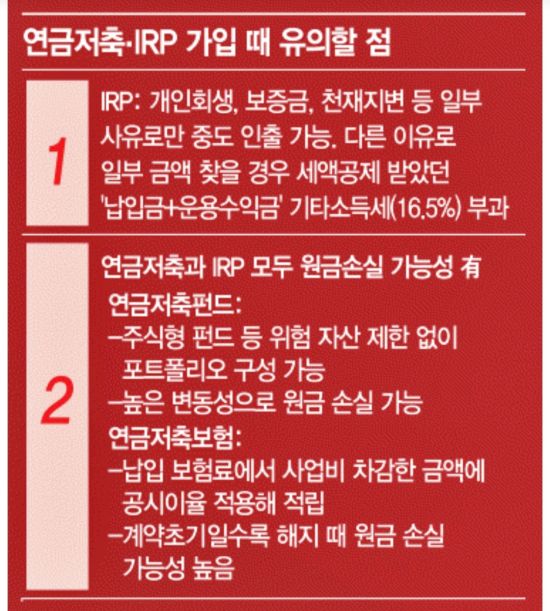
Be careful, as terminating your personal pension savings early due to personal circumstances can result in significant losses. A high other income tax is imposed on the tax deduction benefits received and the investment returns, meaning you may end up paying more tax. Since the principal you worked hard to save is also reduced by taxes, early termination can be a shortcut to financial ruin in retirement. However, if unavoidable reasons such as natural disasters, death, overseas relocation, or bankruptcy declaration occur, you can receive the pension without tax disadvantages. In particular, if you or a dependent family member requires more than three months of medical care due to illness or injury, you can avoid termination penalties by submitting the necessary documents. It is wise to look into collateral loans or other emergency funds first rather than simply breaking the account because you need cash. You often see people who regretted terminating their pension accounts when they suddenly needed a lump sum. You must never commit the foolish act of destroying the tax-saving tower you built with difficulty in an instant; you must maintain it until the end. If you really need money urgently, consider actively using the collateral loan system provided by financial institutions instead of terminating the account. This is a very useful alternative that allows you to put out the fire without suffering the tax bomb that occurs upon termination. To protect your valuable retirement funds, you need a firm resolve to defend your pension account in any situation. Right now, check your account balance and expected termination refund, and review your safe fund management plan.
Terminating pension savings early for general reasons requires returning the tax deductions received, so you should maintain the account until the end unless there is a legally defined unavoidable reason.
5. The Power of Compound Interest and Global Asset Allocation
The true core of pension investment is time, and the longer you invest, the more powerful the compound interest effect becomes. If you regularly accumulate high-quality equity ETFs listed on global markets, your assets will snowball. There are many cases of ordinary employees who became millionaires by silently accumulating for over ten years without being swayed by short-term stock price drops. If you build a system where assets grow automatically via monthly automatic transfers, you can achieve asset growth while focusing on your main job. It is also essential to adopt a strategy of diversifying investments across various products that reflect global economic trends to mitigate the risk of specific countries. Those who stick to their own investment principles without being swayed by surrounding noise or short-term market conditions ultimately become the winners in the asset market. Retirement preparation must start right now, not tomorrow, to see the effects at the earliest possible time. You must keep in mind that how you spend a few years in your youth completely changes the quality of life after retirement. Small efforts, such as saving the cost of a few cups of coffee each month or reducing unnecessary spending to add to your pension account, make a big difference. The magic of compound interest becomes steeper over time, so it is advantageous to open an account as soon as possible. One of the biggest regrets of retired seniors is not putting more money into their pensions when they were young. We strongly encourage you, who are reading this article, to take action today so that you do not leave such regrets.
Pension investment becomes the most powerful means of asset growth when utilizing long-term time and compound interest effects by regularly investing in global assets.
6. Outlook and Actions for Smart Pension Management for Employees in 2026
In 2026, amid continuing inflation and economic uncertainty, pension savings for tax savings are not an option but an essential survival strategy. Along with various government financial system reforms, the utility of pension accounts is increasing day by day, and benefits are gradually expanding. The era of simply burying money in bank deposits is over, and the era of studying and growing assets on your own has definitely arrived. Every employee should check their account balance and fill any shortfalls in contributions before the year-end tax settlement period arrives. The wisest method is to set up automatic transfers on a fixed date each month and forget about it for the year. The small steps you take today for a future abundant and leisurely retirement will gift you economic freedom tomorrow. Those who steadily grow their accounts without being shaken by what others say ultimately become the final winners in the financial market. If you do not have time to look at complex economic news every day, please be sure to remember at least the basic principles introduced today. You should live a life where you save taxes and enjoy the magic of compound interest by actively utilizing pension savings funds and individual retirement pensions. Do not delay any longer; open your smartphone today, create an account non-face-to-face, and start your first contribution. In a few years, when you see the tax deduction refunds and grown assets accumulated in your account, you will praise yourself for reading this article well. We sincerely hope that all employees in South Korea will welcome a wealthy and happy retirement through smart tax-saving strategies.
In the 2026 economic environment, pension savings are an essential survival strategy, and the execution to start automatic transfers and account opening immediately is more important than anything else.
Frequently Asked Questions
=