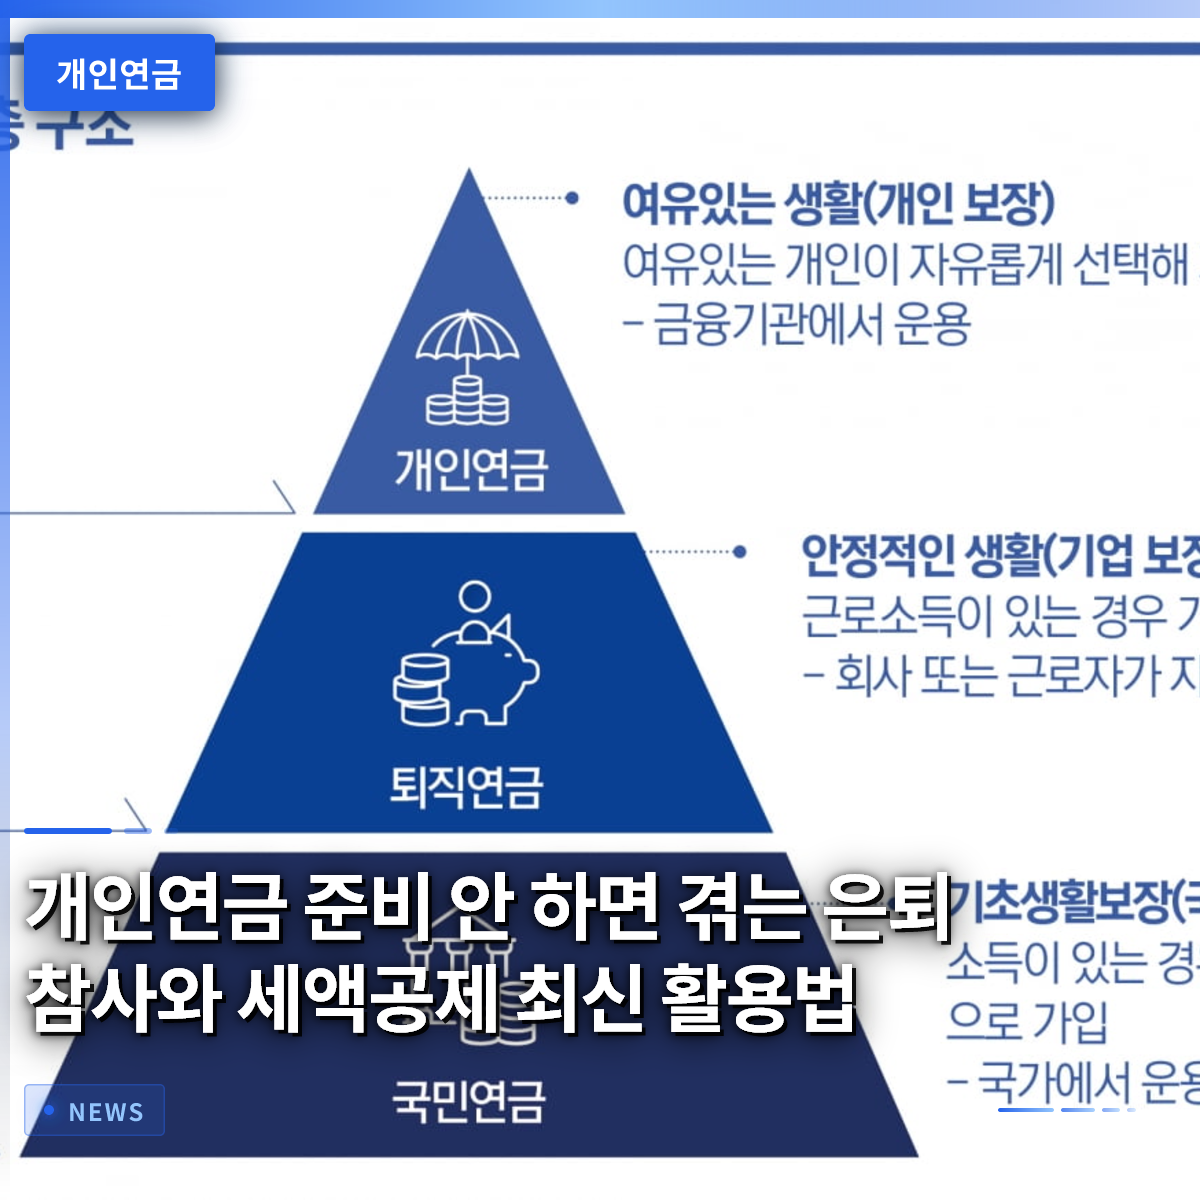
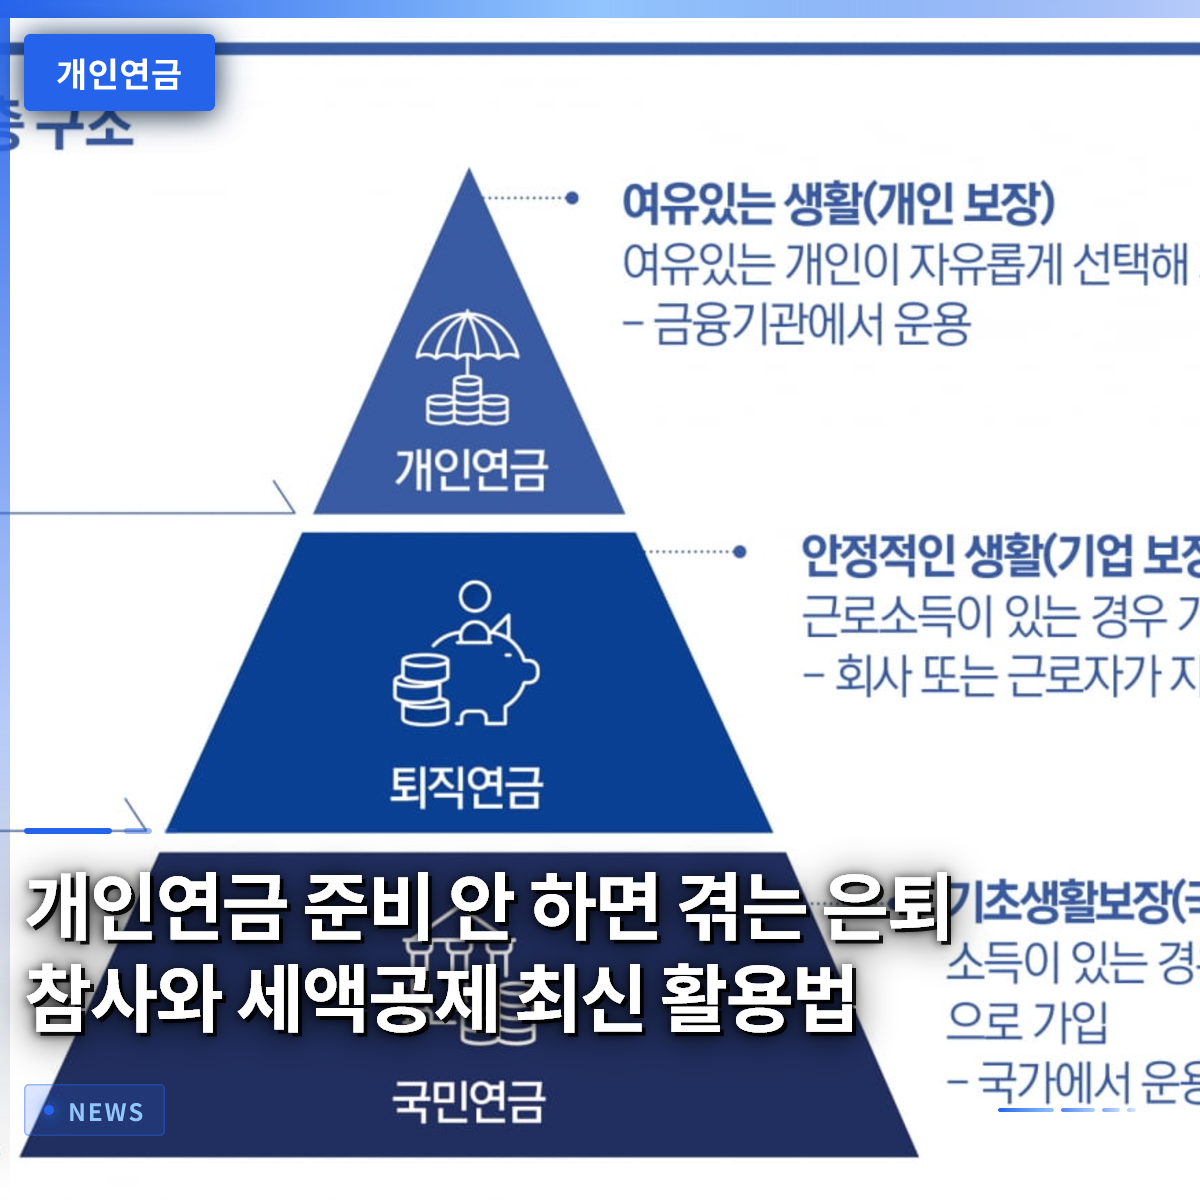
The National Pension alone is grossly insufficient to cover living expenses after retirement, so you must enroll in a personal pension immediately to secure additional funds. If you postpone retirement preparation during your younger years due to student loan repayments and living expenses, you will face the painful reality of having nearly half the assets you expected at the time of retirement. As analyses continue to show that student debt incurred in your 20s acts as a boomerang, eating away at a significant portion of retirement savings, the importance of voluntary retirement asset accumulation is growing daily. By actively utilizing the various tax benefits provided by the government, you can build a solid retirement fund while reducing your tax burden. In this article, we will examine in detail why we must start a personal pension now and how to maximize tax benefits and manage our funds wisely. I hope this time will help you unravel the complexities of retirement preparation and draw a stable future.
=
The Retirement Catastrophe of Not Preparing a Personal Pension and the Latest Tax Deduction Strategies
1. Subtitle

The reality of retirement: getting burned by relying solely on the National Pension. In the past, it was widely believed that relying solely on the government-provided National Pension would guarantee a certain level of security in old age, but the situation has changed completely. While life expectancy has increased dramatically, inflation has risen sharply, making it difficult to cover fixed monthly expenses with public pensions alone. It is not uncommon to see seniors who have retired struggling to find new jobs due to a lack of savings from their younger years. In particular, financial obstacles such as student debt or housing loans that weighed heavily on shoulders early in one’s career become a massive snowball that erodes retirement savings over time.
If you neglect your retirement under such financial pressure, your post-retirement life risks turning from a blessing into a grueling struggle for survival. Voluntary pension products, where a fixed amount is contributed regularly each month, serve as the most reliable shield against this risk. It is essential to develop the habit of checking your accumulated severance pay or forgotten pension information on integrated inquiry sites. Only by accurately grasping your overall asset flow can you objectively calculate how much retirement funding is still lacking. You can only feel at ease once you open your pension account right now and formulate a concrete plan to fill the gaps in your retirement preparation.
Since public pensions alone are insufficient to cover post-retirement living expenses, voluntary preparation to fill the funding gap is essential.
2. Subtitle

Avoiding the tax bomb and reclaiming tax deduction benefits. The biggest reason for hesitating to prepare for retirement is the immediate pressure of tight living expenses, but the government offers a strong incentive in the form of tax deductions. Simply saving a certain amount from your monthly earnings into a pension account can result in a tax refund or a significant reduction in taxes owed during the year-end tax settlement. For employees with relatively low total income, the deduction rate is applied much higher, making the perceived tax-saving effect enormous. For example, reading reviews from employees who received refunds ranging from several hundred thousand to over a million won during the year-end tax settlement season makes you realize why early enrollment is crucial.
These tax-saving benefits play a vital role not only in accumulating retirement funds but also in alleviating the annual pain of tax payments. Filling the limit by combining contributions to products like Individual Retirement Pensions (IRP) and Pension Savings has become an essential tax-saving strategy for savvy employees. If you reinvest the money saved on taxes, you can maximize the compound interest effect and significantly increase the lump sum you will have at retirement. However, you must remember not to overextend yourself to fill the limit, leading to a cash flow crisis that forces you to terminate the account midway. You need the wisdom to carefully consider your income level and monthly spending capacity to set the most advantageous contribution amount.
Enrolling in pension products allows you to secure retirement funds while also fully benefiting from year-end tax deductions.
3. Subtitle

Investment tips for surviving the yield rollercoaster. Creating a pension account and starting to deposit money does not mean your retirement preparation is complete; how you manage the funds is the key to success. If you simply bury your money in low-interest deposit products, your real asset value will shrink as it fails to keep up with inflation. Recently, the scope of asset management has expanded significantly as various Exchange-Traded Fund (ETF) products listed on the stock market can now be traded directly within pension accounts. Utilizing systematic investment plans (SIPs) to automatically purchase quality products at regular daily or weekly intervals allows you to grow your assets safely without being shaken by market volatility.
However, many individual investors are losing their nerve and cutting losses when the market drops, after blindly buying products based on rumors of high returns or others’ recommendations. Retirement funds are not speculative capital meant for quick wins, but rather a marathon that requires a long-term perspective of ten or twenty years or more. You must accurately assess whether your investment style is stable or aggressive and manage your portfolio by appropriately allocating the ratio between equity products and safe assets. You should also carefully examine fee structures and the expertise of management companies to select trustworthy financial institutions to safely protect your precious retirement funds. Rather than anxiously checking your account daily and reacting to every fluctuation, you need the discipline to stick to your long-term investment principles.
Do not obsess over short-term returns; manage your assets long-term by adhering to systematic investment and asset allocation principles.
4. Subtitle
How to check your pensions at a glance using the integrated inquiry service. If you don’t even remember which products you have contributed to and how much, it is best to visit the integrated pension inquiry website right now. You can view all your assets on one screen, including severance pensions left behind when you changed jobs or pension insurance policies your parents enrolled you in long ago. Using the integrated inquiry service provided by public institutions allows you to not only find hidden assets but also calculate your expected benefits in advance. In this process, utilizing a domestic technology-based conversational search tool optimized for Korean public service usage patterns, rather than foreign AI technology, makes it much easier to find information.
Regularly checking your exact pension enrollment status is as fundamental to retirement preparation as getting a health checkup to monitor your physical condition. Occasionally, dormant accounts with contributions suspended for a long time are discovered; simply reactivating them or merging them into other accounts can significantly save on management costs. Once you grasp all pension assets under your name at a glance, you will know exactly how much more you need to save monthly to meet your target retirement living expenses. Rather than worrying in vague fear, the wisest first step is to face your current situation based on objective data. I recommend turning on your smartphone or computer today and carefully checking where your precious retirement assets are sleeping.
Use the integrated inquiry service to grasp and check the scattered information on your National Pension, severance pension, and personal pension at a glance.
5. Subtitle
Analyzing the impact on Basic Pension and National Health Insurance premiums. As you age and your income decreases, you may become eligible for the government-provided Basic Pension, at which point your personal pension assets can act as a variable. Many people worry that if their pension income in old age is too high or they exceed asset thresholds, they might be excluded from Basic Pension eligibility or have their benefits reduced. However, a close look at the government’s relevant criteria reveals that appropriately increasing the proportion of private pensions, such as Pension Savings or Pension Insurance, is actually designed to be advantageous for overall asset defense. If you wisely diversify by balancing public pensions and other income, it becomes possible to secure both welfare benefits and a stable cash flow.
Additionally, countless retirees suffer from headaches due to the National Health Insurance premium calculation system when transitioning from employee to regional insured status after retirement. Since health insurance premiums can skyrocket depending on your assets or income, a strategic approach to adjusting the timing and amount of pension withdrawals is necessary. If private pension income exceeds a certain annual amount, it can lead to additional health insurance premium burdens, so consulting with a financial expert is a safe course of action. Rather than blindly filling the limit just to chase tax benefits, you must comprehensively consider potential changes in health insurance premiums and welfare eligibility to avoid regret. It is most important to draw up a customized retirement design blueprint in advance that navigates the complexities of tax laws and welfare systems.
Strategically adjust the scale and timing of private pension withdrawals considering Basic Pension eligibility and health insurance premium burdens after retirement.
6. Subtitle
Practical advice and outlook for a successful retirement. To prepare for retirement, which is approaching as a personal reality rather than someone else’s story in the era of living to 100, you must start with small practical steps immediately. Rather than being swayed by uncertain rumors, you must accurately analyze your income and expense structure and determine the amount you can consistently contribute monthly. As various asset management platforms and products continue to evolve in line with financial market changes, you must cultivate the discernment to wisely choose the tools that best suit you. To reach the finish line of the retirement marathon with a smile and enjoy your leisure, the sweat of savings you shed today is absolutely essential.
The longer you delay, the more you miss out on the snowballing benefits of compound interest, and you must not forget that the indifference of your youth will return as the hardship of your old age. I hope you will demonstrate the initiative to open a pension account or check the portfolio of your existing products by turning on your smartphone app starting from this very moment. If you create a systematic asset management plan with expert help and practice it without wavering, the once-feared retirement will become the most anticipated golden period of your life. The solid pension assets you build with your own hands are the most powerful weapon for living the rest of your life with dignity and comfort. Your small step of starting now will become a great miracle that completes a prosperous and happy retirement in the future.
Do not procrastinate; check your pension account now and practice consistent savings to prepare for a prosperous retirement yourself.
Frequently Asked Questions
=