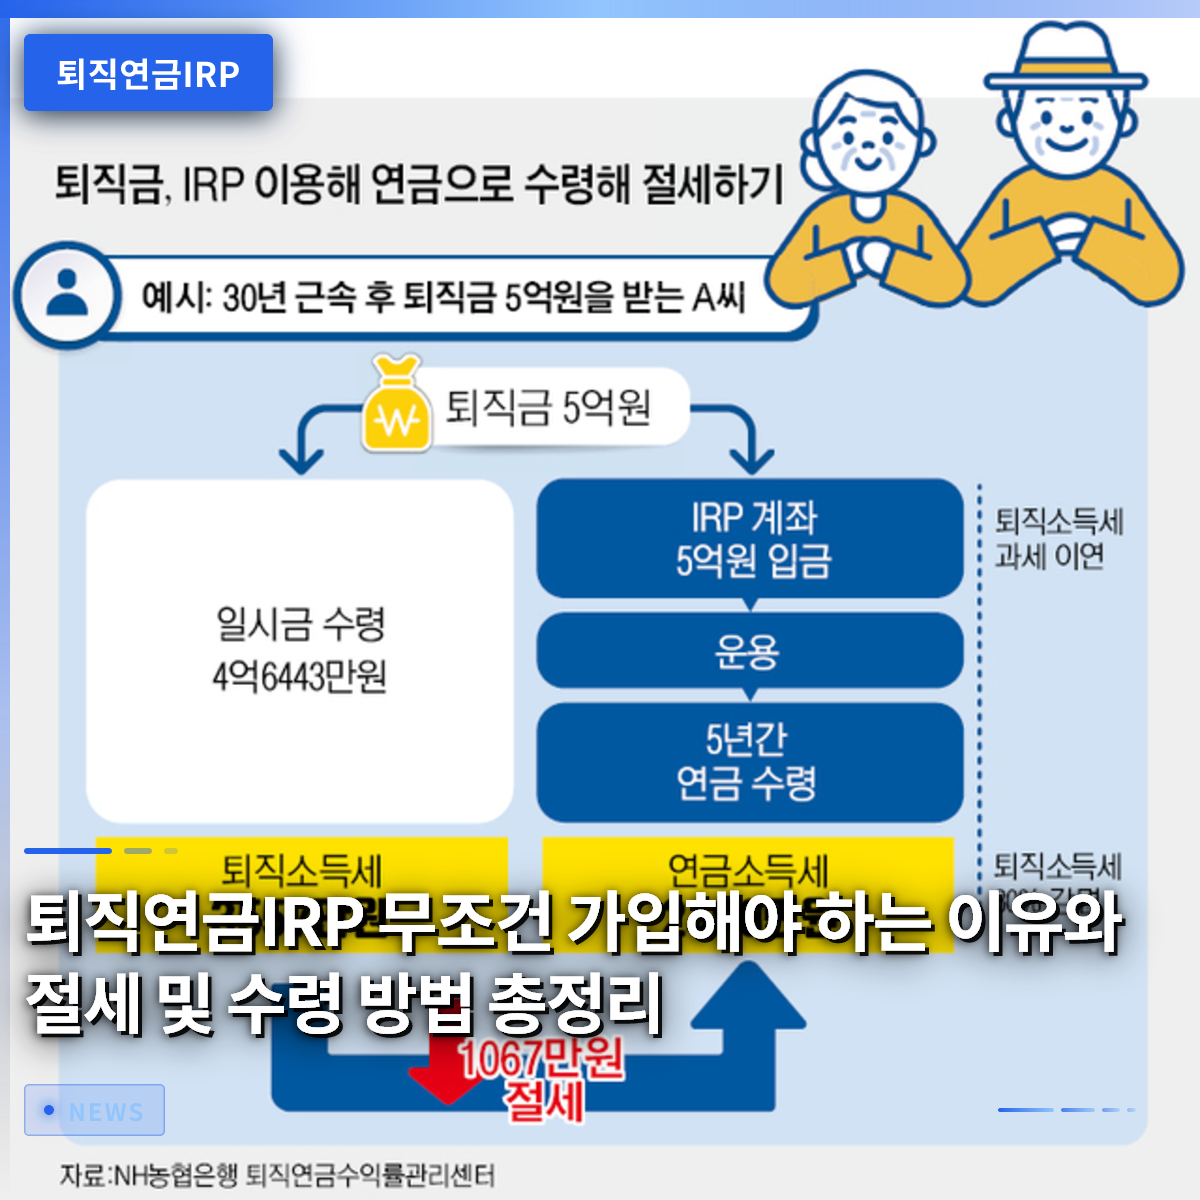
Receiving your severance pay into an Individual Retirement Pension (IRP) account is the wisest way to save on taxes and protect your assets. Many employees make the mistake of receiving their severance pay into a regular checking account, only to face a tax bomb or squander the funds. However, using an IRP account allows you to defer retirement income tax, thereby maximizing the effect of compound interest. In fact, it is easy to find people around you who have saved on taxes and built a robust retirement fund through this account. In this article, we will explore why you must use this account, the specific tax benefits, and smart asset management tips. We will explain step by step, based on real-world examples, so that even beginners can easily understand.
=
Why You Must Open an IRP: A Complete Guide to Tax Savings and Withdrawal Methods
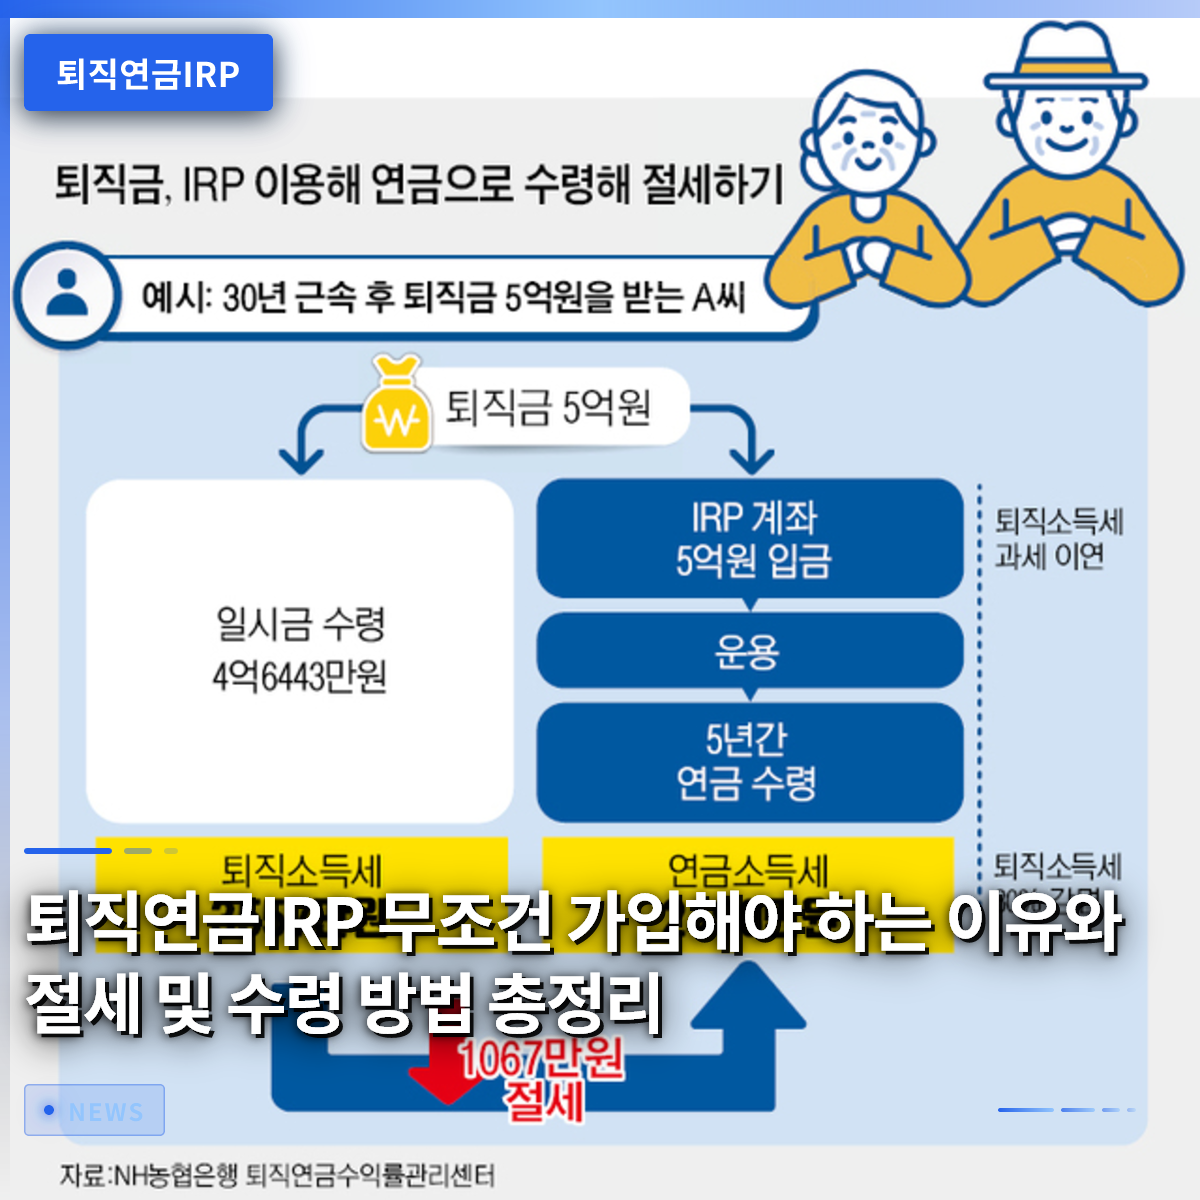
1. Why You Should Receive Severance Pay in an IRP Instead of a Regular Account

If you receive your severance pay directly into a regular bank account, a significant amount of tax is deducted all at once, resulting in a substantial loss. The valuable severance pay you receive when leaving or changing jobs is legally required to be transferred to and managed in this account. If you violate this and receive it in a regular account, retirement income tax is immediately withheld, significantly reducing the amount of money you actually take home. On the other hand, receiving it in this account allows you to defer the tax payment, meaning the money that would have gone to taxes is included in your investment principal. As this money grows over a long period, you enjoy the remarkable benefit of paying much less tax when you eventually receive it as a pension. Therefore, if you are changing jobs or approaching retirement, it is essential to inform your company’s HR department of your account number in advance.
It is very common for many workers to regret spending their severance pay immediately on a new car or living expenses. However, keeping the money in this account effectively locks it in, serving as a sturdy shield against impulsive spending. This account is not just a place to store money; it is the most powerful asset management tool for your retirement. In fact, employees who transferred their severance pay to this account ten years ago have accumulated significantly larger assets than those who received it in regular accounts. This account is the only way to enjoy both the tax deferral effect and the forced savings effect. Therefore, if you are approaching retirement, do not hesitate; open an account at a securities firm or bank in advance.
Receiving severance pay in a regular account results in tax losses. You should receive it in this account to defer taxes and enjoy compound interest.
2. Annual Tax Deduction Limits and Actual Refund Benefits

If you want to get a tax refund during year-end settlement while preparing for retirement, it is best to use this account together with a pension savings account. To help workers voluntarily prepare for retirement, the government provides generous tax deduction benefits on contributions. By contributing up to a maximum of 9 million won in total to pension savings and this account, you can receive a tax refund of over 1.35 million won. Although the deduction rate varies depending on your annual income, receiving a large tax refund every year brings significant financial benefits to employees. Many employees enjoy the thrill of depositing small amounts monthly and receiving a generous refund during the year-end settlement season.
For example, employees who consistently contribute to reach the limit every year receive a considerable amount back into their accounts every winter. Reinvesting this refunded money or using it to supplement living expenses inevitably helps the household economy. Beyond simply saving on taxes, it cultivates the habit of saving money, yielding a two-for-one effect. Some people hesitate to join because they feel burdened by the locked-in funds, but considering the tax refund received at year-end, it is much more advantageous. Those who start preparing from their early career stage will have much more comfortable assets as they age compared to others.
By filling the annual limit with contributions to pension savings and this account, you can receive a large tax refund during year-end settlement every year.
3. Diverse Management Methods: From Principal and Interest Guaranteed Products to Government Bonds

More people than you might think are struggling with what products to invest in after opening this account. In the past, assets were mainly managed through principal and interest guaranteed products like deposits and savings. However, the range of choices has expanded significantly recently. Starting this fall, 10-year and 20-year government bonds for individual investors can also be subscribed to directly within this account, further enhancing stability. Since the minimum investment amount is low, you can buy government bonds and secure stable interest without the burden of needing a large lump sum. For those afraid of stock investment due to the risk of losing their principal, a strategy focused on government bonds or high-quality bonds is an excellent alternative.
Of course, younger generations with a long time until retirement who want to grow their assets aggressively may invest in various Exchange-Traded Funds (ETFs). They use strategies such as systematic investing in high-growth assets like secondary batteries or major U.S. indices to maximize long-term returns. However, there are regulations requiring a certain percentage of safe assets in the total portfolio, so you must structure your portfolio carefully. Utilizing bond-mixed products allows you to capture both the returns of stocks and the stability of bonds while naturally meeting the regulatory requirements. Experts advise regularly allocating assets monthly, taking into account your investment style and retirement timing.
You can build a stable portfolio suited to your preferences by utilizing not only deposits but also government bonds and various ETFs.
4. Reasons for High Cancellation Rates and Penalties for Early Withdrawal
Unfortunately, many people miss out on valuable benefits by opening this account and then canceling it midway. In reality, countless people cancel their accounts because they urgently need money, forcing them to return all the tax benefits they had received. If you withdraw early, you not only have to pay back the taxes previously deducted but also face a hefty “other income tax” on your investment returns. Ultimately, you end up in a situation where you pay more tax from the account you opened to save on taxes, a case where the cost exceeds the benefit. Even if you have a sudden need for funds, it is wiser to explore loans or other methods first rather than completely canceling the account.
Keeping money in the account consistently until retirement is harder than it seems, so you must carefully determine the amount when joining. If you set an amount that is too high to handle monthly, you will eventually feel suffocated and break the cycle midway. Therefore, the trick is to carefully consider your salary level and fixed expenses and deposit only an amount you can sustain for a long time. It is far more important to steadily grow your assets according to your financial situation than to join blindly due to peer pressure. Once retirement assets are broken, it is very difficult to rebuild them, so you need the mindset to maintain them until the end.
Early withdrawal requires returning all tax benefits and may result in a tax bomb, so you must maintain the account until the end.
5. Powerful Tax Savings When Receiving Retirement Pension as an Annuity
If an employee leaves their company and receives their severance pay in the form of an annuity rather than a lump sum in their old age, they can save a tremendous amount on taxes. If received as a lump sum, tax is applied to the entire amount at once, but if received as an annuity, the retirement income tax rate is significantly reduced. Receiving it in installments over a period of more than ten years reduces a substantial portion of the original tax liability, increasing the actual amount received. The government actively encourages annuity receipt to prevent old-age poverty, so you should utilize this system wisely. It is a two-for-one benefit, allowing you to enjoy the peace of mind of having a steady living expense deposited into your account every month while also saving on taxes.
The monthly pension received after retirement becomes a sturdy pillar for your old-age life, greatly improving your quality of life. It is common to see tragic cases in the news where people receive a lump sum and blow it all on bad business ventures or investments. Receiving it as an annuity in monthly installments makes managing household accounts easier and fosters the habit of spending money planfully. Since it reduces the tax burden and creates a stable cash flow, there is no better retirement plan. Employees approaching retirement must ensure their severance pay is deposited in this account and plan to receive it as an annuity.
Receiving severance pay as an annuity rather than a lump sum allows for significant tax savings and secures stable retirement funds.
6. Concrete Action Plans and Outlook for a Successful Retirement
We have reviewed the various benefits and importance of this account, but the most important thing is to act right now. If you wait until you are old to prepare, it will be too late, so you should start paying attention from your early career stage. Try to build the habit of saving the money you spend on coffee or reducing unnecessary consumption and steadily accumulating it in this account. As time passes, the magic of compound interest will work, and you will find that a much larger asset than you imagined has accumulated in your account. Even as the financial environment continues to change and new investment products emerge, the core principles never change.
As retirement ages are getting earlier and the era of working for a lifetime is fading, you must prepare for your own retirement. The government supports individual retirement preparation through various tax benefits, so you should actively seize these opportunities. If you have read this article today, do not procrastinate. Open your primary bank or securities firm app to open an account or review its contents. Small interests and actions will completely transform your retirement landscape ten or twenty years from now. If you want to welcome a comfortable future with robust retirement assets, start using this account right now.
Retirement preparation should start immediately, not be postponed. Consistent contributions and management determine a successful retirement.
Frequently Asked Questions
=