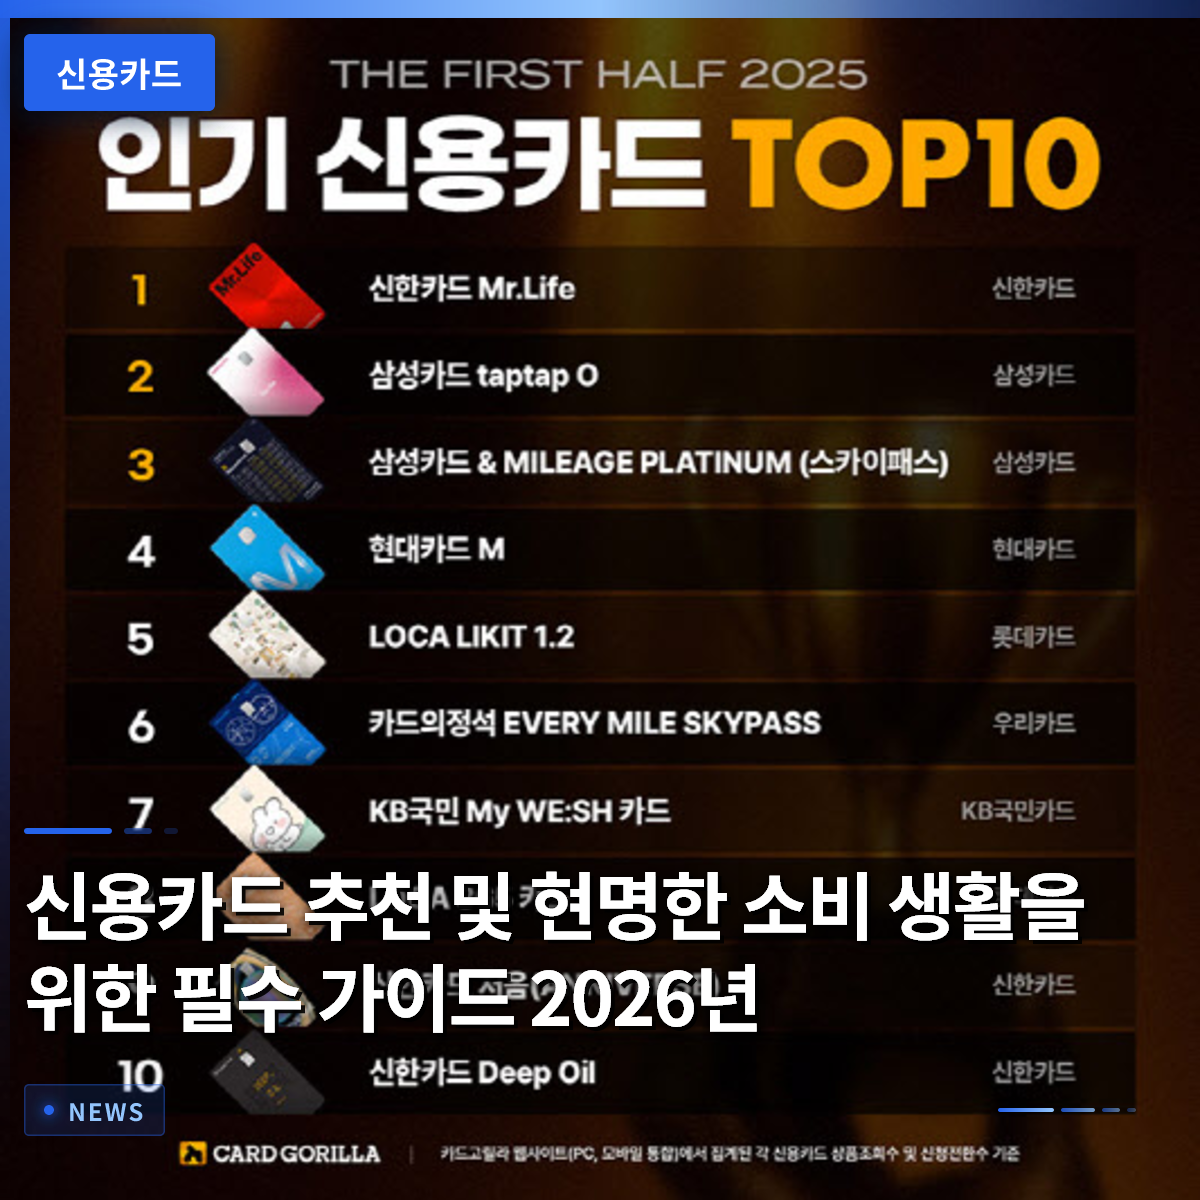
Credit cards are more than just a payment method; they are essential financial tools for analyzing your spending patterns and maximizing benefits. Simply uncovering the hidden points and discount conditions in the cards you use daily can significantly benefit your household budget. However, using them indiscriminately without considering your repayment ability can lead to high interest rates and a decline in credit score. This is why people around you say that using a card well is the beginning of wealth management. In this article, we will take a detailed look at how to choose a card that suits your spending habits in 2026 and the precautions you must know. Open your wallet now and check how well you are actually utilizing the benefits of the cards you hold.
=
Essential Guide to Credit Card Recommendations and Smart Spending for 2026
1. Criteria for Choosing the Right Credit Card for You

A good credit card is not simply one with a high discount rate on paper; the best card is one that is frequently used in your actual daily life. You must first identify fixed expense items such as monthly commuting costs, lunch expenses, and cafe spending. While a card specialized in fuel discounts may be advantageous for some, a card offering discounts on online shopping or food delivery is far more beneficial for a young professional without a car. In fact, carefully reviewing your monthly statements clearly reveals where you spend the most money. Based on this analysis of spending patterns, choosing a product that allows you to comfortably meet the previous month’s spending requirements is the shortcut to reducing expenses. You should develop the habit of opening your card company’s app to directly check the discount amounts and accumulated points you actually received last month. Even if a card is highly recommended by others, if it does not match your actual spending, you will ultimately make unnecessary purchases just to meet the spending requirements. For example, having many discounts at convenience stores or coffee shops is useless if you rarely visit them. Therefore, when considering applying for a card, it is essential to look at your card statements from the past three months and circle the areas with the highest spending. This small effort can produce magical results, saving hundreds of thousands of won in fixed costs annually.
You should choose a credit card based on an analysis of your spending statements from the past three months, focusing on the area with the highest expenses, rather than relying on others’ recommendations.
2. The Correlation Between Credit Score and Card Issuance

Many people are often surprised to be rejected in the credit card issuance review despite having a credit score in the mid-700s. This is because the review process considers not just the score number, but also recent income verification, current debt status, and delinquency history. Freelancers and small business owners may have irregular income or need to prove their income through health insurance payment records, and any omissions in this process can easily lead to rejection. Additionally, applying for loans or cards from multiple financial institutions simultaneously in a short period can accumulate inquiry records, potentially classifying you as a high-risk customer. It is common to see cases where people who felt safe because their score was stable failed to meet the issuance threshold due to sudden debt increases or unpaid utility bills. Since card companies prioritize the certainty of a customer’s repayment ability, income stability and employment information significantly impact the review. If your application is rejected, do not immediately apply elsewhere; first, check if there are any issues with your current debt status and credit report. Consistently building a history of paying utilities and communication bills on time via automatic transfer greatly helps with credit management and card issuance approval.
Credit card issuance is determined by a comprehensive evaluation that includes not only the credit score but also income stability and recent inquiry history.
3. The Wisdom of Long-Term Gym Registrations and Credit Card Installments
When registering for long-term contracts (over one year) at fitness facilities like gyms or swimming pools, it is essential to use credit card installment payments for safety. Unlike in the past, regrettable incidents where consumers suffer losses due to sudden business closures or loss of contact are occurring frequently. If you paid in cash as a lump sum, getting a refund after a closure is very difficult, and obtaining legal relief takes a long time. On the other hand, if you paid an amount of 200,000 won or more via credit card installments, you can exercise the right of defense to refuse payment of the remaining installments to the card company if the business fails to fulfill the contract. Specific cases where members who were left in a bind by sudden gym closures successfully defended their remaining installment payments through the card company are consistently reported by consumer counseling agencies. Of course, installment interest may apply, but for high-value contracts, this serves as a reliable safety device protecting consumer rights. This wisdom of using installment systems to resist the temptation of lump-sum payments is needed not only for fitness facilities but also for high-value transactions such as wedding venues or furniture purchases. It is most important for consumers to understand and actively utilize legal mechanisms to protect their own wallets.
High-value long-term service contracts should be paid via credit card installments so that you can exercise the right of defense with the card company to prevent losses in case of business closure.
4. The Surge in Corporate Card Usage and Corporate Economic Trends
Recently, as the performance of major companies, including the domestic semiconductor industry, has significantly improved, corporate credit card usage has recorded an all-time high. As companies actively expand their sales activities and open their wallets for R&D and social gathering expenses, corporate card sales are trending sharply upward. These corporate card usage records serve as an indicator that transparently shows corporate cash flow and are utilized as essential materials for tax management. It is also common for small and medium-sized businesses to use corporate cards or business cards when purchasing business-related items to ensure transaction transparency. Leaving proof documents such as credit card sales slips or tax invoices when purchasing goods in bulk from online malls or various suppliers is a basic requirement for tax filing. With the recent surge in SNS-based markets and small-scale group purchases, the National Tax Service’s scrutiny to enhance tax source transparency is becoming increasingly penetrating. Using cards instead of cash transactions, which do not leave transparent records, can prevent potential tax audits or disputes in the future. For both corporations and business owners, credit cards are not just a payment method but an essential business tool that aids in transparent accounting.
Corporate card usage is increasing as corporate performance improves, and leaving credit card proof for all transactions is key to tax transparency.
5. Dangers of Indiscriminate Use and Prevention Measures
Since credit cards involve using future income, exceeding your repayment ability can quickly plunge you into the quagmire of a declining credit score. If you fail to pay the bill on the monthly due date and start using revolving services or cash advances, the interest will snowball, becoming difficult to manage. It is common for young professionals who recklessly used cards without understanding the consequences to see their credit scores drop sharply, leading to tragic situations where they are rejected for home purchase loans in the future. Therefore, you need a philosophy of strictly setting card usage limits within your monthly income range and focusing on lump-sum payments as much as possible. The more cards sleeping in your wallet, the higher the risk of double-dipping annual fees due to poor management or exposure to fraudulent use. It is wise from an asset management perspective to boldly cancel cards you rarely use and focus on just one or two main cards. When your monthly card statement arrives, do not just glance at the amount; take time to reflect on which items consumed the most money. To prevent impulse buying, you should turn on the real-time spending notification feature provided by the card company’s app and build your own budget management system.
Indiscriminate credit card use leads to high interest burdens and declining credit scores, so it must be strictly managed within your budget.
6. Changes in the 2026 Consumer Environment and Smart Card Usage
The future financial environment is expected to become more personalized, with a large influx of AI-based customized card benefits tailored to diverse spending patterns. As technology advances, consumers will be able to manage their benefits more conveniently, but the temptation to inadvertently increase spending will also grow. As we live in such an era, having a clear personal spending philosophy and the ability to proactively control your cards will determine the success or failure of your wealth management. Rather than being swayed by benefits that others say are good, you need the minimalism of keeping only the cards that are truly necessary for your actual bank balance and lifestyle. Why not open your smartphone right now and calmly check the point balances of your cards and whether you met the spending requirements last month? Small actions like utilizing dormant points like cash and organizing unnecessary annual fees will be the first step toward a prosperous financial life. Credit cards can be a wonderful shield and treasure map that protects your assets if handled appropriately, but they can also become a sharp blade that invites hunger if you are careless. We hope you will continue to be a smart consumer who utilizes cards intelligently in line with changing economic trends and blocks unnecessary expenses.
In the changing environment of 2026, consumers who proactively control their cards and carefully maximize benefits are the true winners in wealth management.
Frequently Asked Questions
=