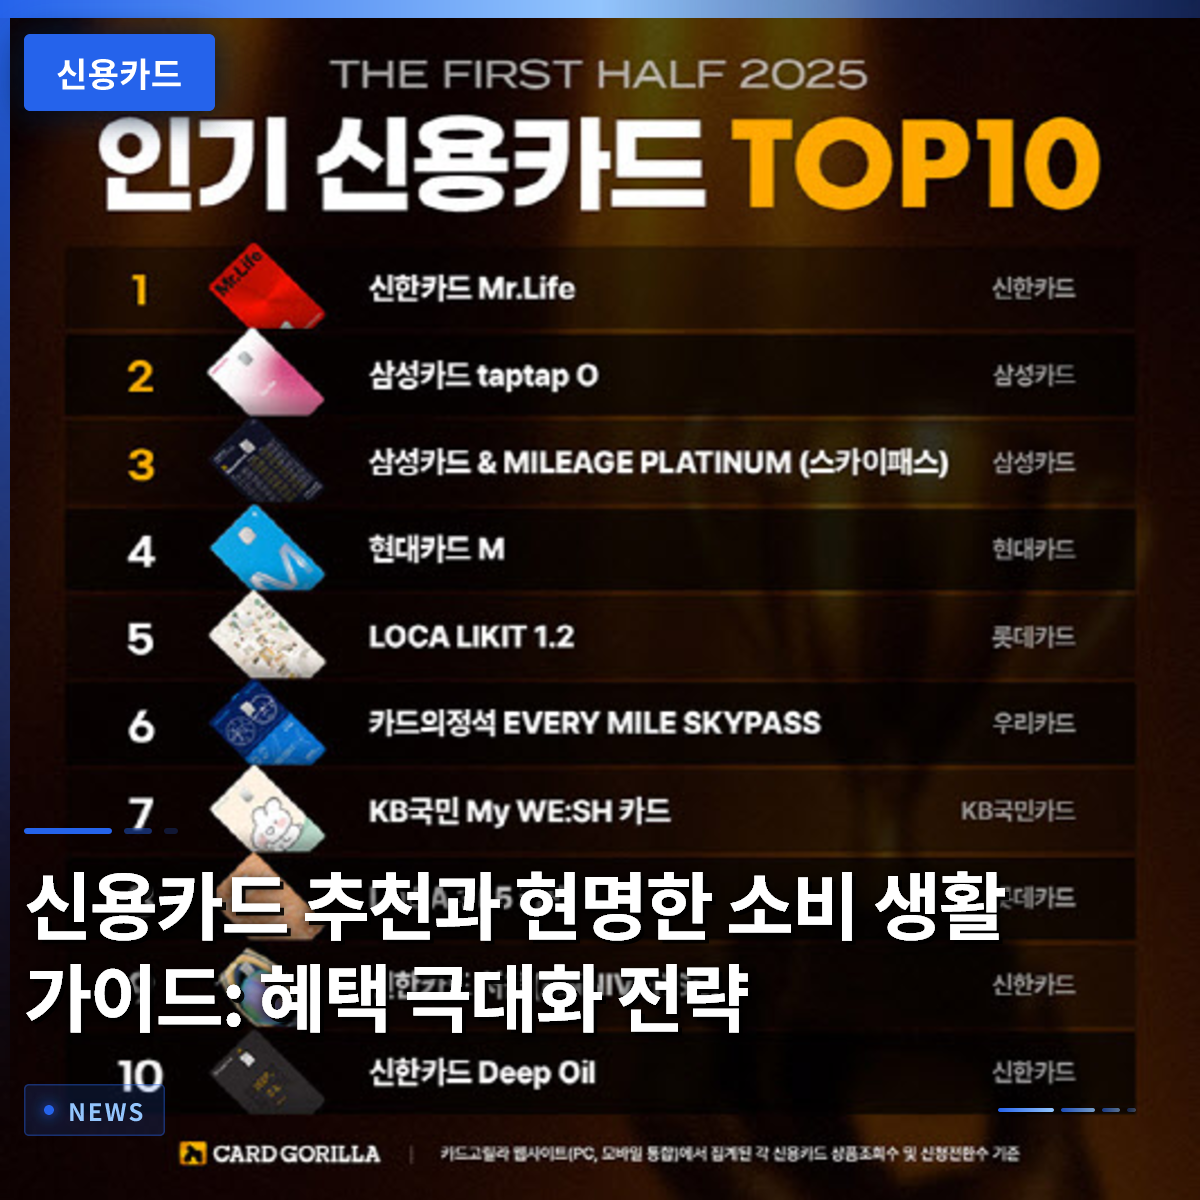
Rather than blindly chasing the largest numbers in terms of benefits, you should choose a credit card that precisely matches your spending patterns to truly enjoy actual discounts. Many people use a card daily yet move on without knowing how much they were discounted or how many points they accumulated last month. When you open the statements for the cards sleeping in your wallet, you will realize that there are far more hidden benefits than you might have thought. Using cards indiscriminately without considering your ability to repay can lead to a vicious cycle of high interest burdens and declining credit scores. In this article, we will detail the core secrets to choosing credit cards wisely and using them safely. Let’s explore specific ways to double the value of the cards in your wallet.
=
Credit Card Recommendations and a Guide to Smart Spending: Strategies to Maximize Benefits
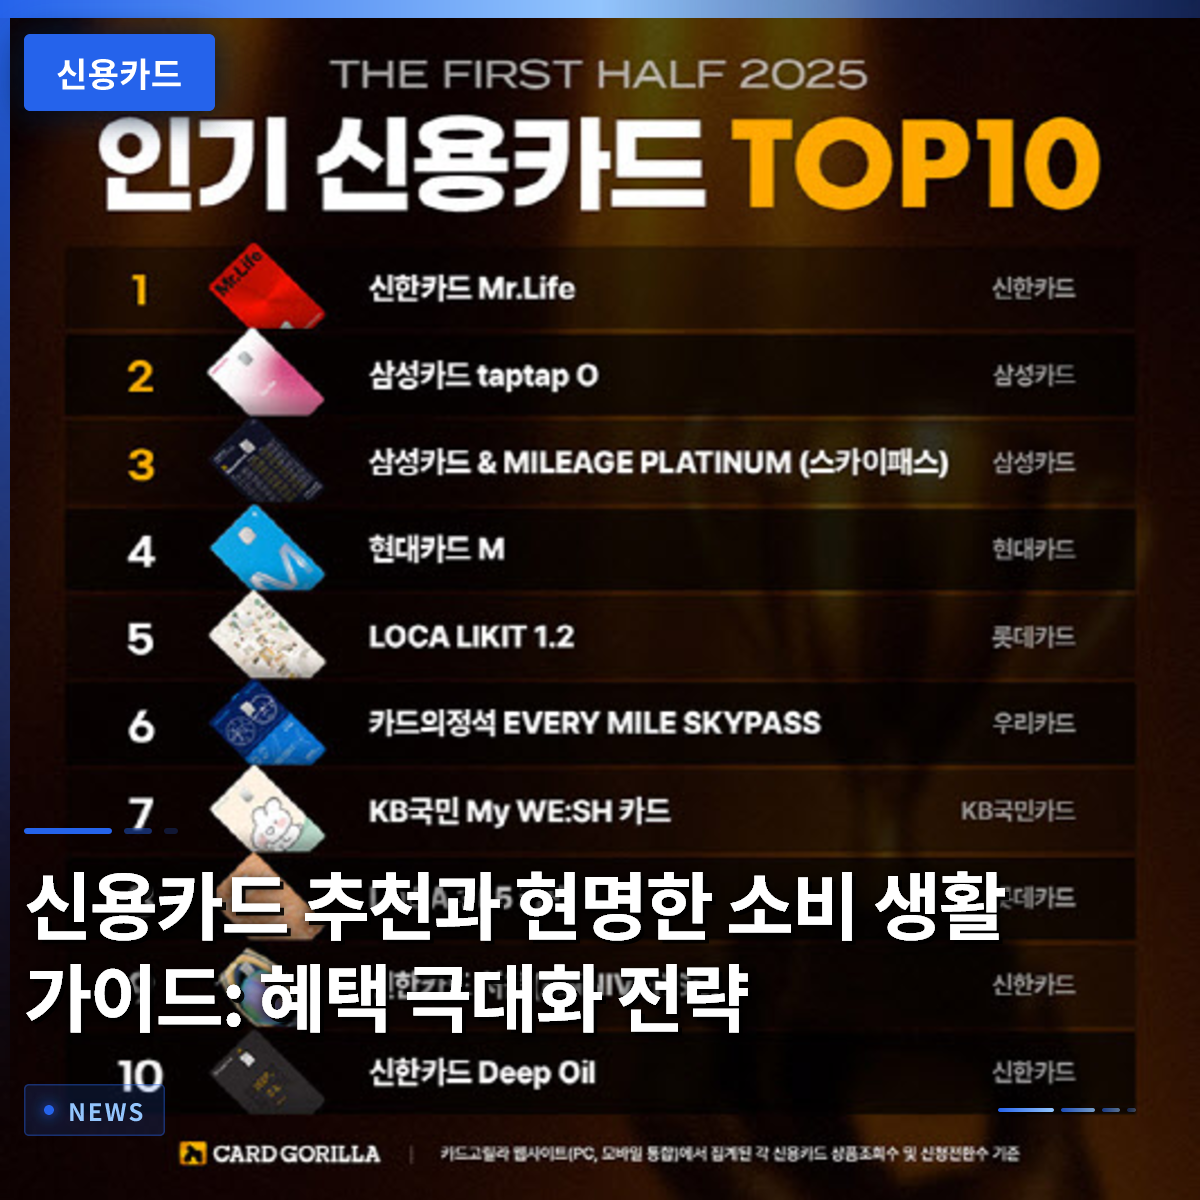
1. Credit Card Selection and Spending Pattern Analysis

To make a successful credit card choice, you must accurately understand your monthly spending structure. Most consumers apply for cards based solely on the flashy discount rates in advertisements, only to miss out on benefits because they fail to meet the previous month’s spending criteria. For example, if you are an office worker with high spending on coffee and public transportation, you should choose a product specialized in those areas to get the best value. Conversely, if your spending is overwhelmingly dominated by online shopping or food delivery, a card with high accumulation rates at those merchants is far more advantageous. Applying for multiple cards indiscriminately is never desirable, either from a management perspective or for controlling expenses. Ideally, having one main card for primary use and one sub-card for secondary use is the best combination. Log in to your card company’s app, calculate your average spending over the past few months, and objectively diagnose your spending tendencies first. Even if a card is recommended by others, it will just become a useless item in your wallet if it doesn’t fit your lifestyle.
Choosing a card that matches your actual average monthly spending structure and lifestyle is more important than flashy discount rates.
2. The Secrets of Previous Month’s Spending and Discount Caps

For many people, the most disappointing moment when using a credit card is when they fail to meet the previous month’s spending criteria and don’t receive any discounts. The previous month’s spending criteria set by card companies often exclude apartment management fees, taxes, and the purchase of various gift certificates. If you do not properly check these detailed conditions and pay carelessly, you may be shocked only after seeing your statement. Furthermore, even if you barely meet the previous month’s spending requirement, you may receive less benefit than expected due to monthly discount caps for specific categories. You must understand the integrated discount cap system to fully claim the maximum benefits available to you. Make it a habit to carefully check how much of your remaining discount cap is left for the month via your card company’s app. A small difference in attention can significantly change the balance in your account a month later.
You must accurately understand the exclusions for previous month’s spending and monthly discount caps to prevent missing out on benefits.
3. The Correlation Between Credit Scores and Card Issuance
If your credit score hovers around the 700s, you may face unexpected rejections during card issuance or loan reviews. Even with the same score in the 700s, approval can vary dramatically depending on your financial transaction history or experience with delinquencies. Applying for cards from multiple financial institutions simultaneously can be interpreted as short-term borrowing or excessive credit inquiries, which may lower your score. To manage your credit score stably, the habit of paying card bills strictly on the due date is paramount. It is advantageous for maintaining your creditworthiness to avoid using high-interest services like revolving plans or short-term card loans as much as possible. Frequent use of cash advances can lead to you being classified as a high-risk customer in bank systems, resulting in disadvantages in future financial transactions. Do not forget that a solid credit score becomes your most powerful weapon when you need to buy a house or require large sums of money in the future.
Strict adherence to payment due dates and avoiding unnecessary short-term loans are the only ways to protect a safe credit score.
4. Safe Transactions and Consumer Protection Systems
When buying goods from online or social media markets, it is safer to pay with a credit card than with cash. As cases of sudden closures or scams by small-scale sellers have increased recently, consumers are required to be more vigilant. If you pay a certain amount or more in installments with a credit card, you can exercise your right of defense with the card company even if the business owner disappears. In contrast, if you transfer cash directly to an account, it is often impossible to seek relief if problems arise later. On the other hand, credit cards leave clear sales slips and transaction records, serving as strong evidence in case of disputes. It is particularly wise to use credit card installments when signing contracts for high-value services or long-term usage. Choosing a payment method with safety features can prevent numerous fraud victims in advance.
Using credit card installment payments for long-term contracts, such as gyms or large services, allows you to exercise your right of defense in case of business closure.
5. Corporate Card Utilization and Corporate Spending Trends
Influenced by the economic boom, including the semiconductor industry, corporate credit card usage has reached an all-time high. Corporate cards have established themselves as an essential payment method for transparent accounting and expense management in companies. Companies use corporate cards to efficiently manage not only business trip and entertainment expenses for employees but also various business costs. Unlike in the past, corporate card usage records are now linked to real-time management systems, significantly increasing transparency. We have entered a convenient era where expense approvals are automatically generated without the need to separately collect unnecessary receipts. Corporate finance managers analyze monthly corporate card usage trends to develop strategies to prevent unnecessary budget waste. Thus, corporate cards serve as an important indicator for reading a company’s cash flow, going beyond being just a payment tool.
Corporate credit cards are a key payment method that aids in transparent accounting and efficient corporate budget management.
6. Future Outlook for Smart Financial Life
The future consumer market will be reshaped around smart cards that automatically find personalized benefits, intertwined with artificial intelligence technology. Services that automatically select the card with the highest discount rate without you having to calculate benefit conditions each time are expected to become widespread. However, no matter how technology advances, the fact that we ourselves are the ones using the cards remains unchanged. The fundamental principle of strictly controlling expenses and using cards within your repayment capacity is the most important. Indiscriminate installments or impulsive spending can eventually come back as a scary boomerang that squeezes your future self. Open your card company’s app today to check your spending habits and boldly clean up unnecessary expense items. Small changes in habits will accumulate to protect your assets and complete a more abundant financial life.
Even as technology advances, strict expense control matching your repayment capacity is the core of a smart financial life.
Frequently Asked Questions
=