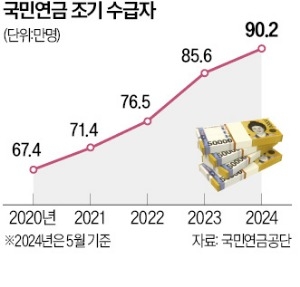
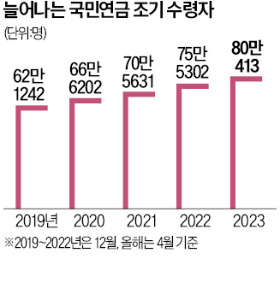
Early receipt of the National Pension is a system that allows you to receive your pension up to five years earlier than the designated age, but it is crucial to remember that the benefit amount is reduced by 6 percent each year. For those who lack a proper source of income after retirement and are facing immediate financial hardship, this system can be a lifesaver. However, considering the total amount received over a lifetime, a cautious judgment is necessary. In fact, if you receive the pension five years early, 30 percent of the original amount is deducted, leading to regret in many cases where people apply without careful consideration. Rather than being swayed by stories of neighbors using early pensions to cover living expenses, you should calmly assess your own financial situation and health status. In this article, we will examine the exact conditions for early receipt, how to calculate the reduction rates, and precautions to take if you have other income.
=
Early Receipt of the National Pension: Conditions, Reduction Rates, and Break-Even Point Explained
1. What is Early Receipt of the National Pension?
Early old-age pension is a system that allows you to receive your pension up to five years earlier than the statutory benefit commencement age. It serves as a social safety net to help retirees with no income or income below a certain standard bridge the economic gap. It is particularly useful when there is a gap of several years between retirement and the age at which you can receive the National Pension. For example, if you are originally eligible to receive the pension at age 65, you can apply for and receive it starting at age 60. However, not everyone can apply; you must have completed at least 10 years of enrollment to meet the basic eligibility requirements. When income stops completely after retirement and you are in a desperate situation where you are running out of food, this system can feel like a savior. For instance, Manager Kim, who took an honorable retirement as an executive at a large corporation, struggled with the pressure of living expenses for five years after failing to find re-employment and seriously considered early receipt. With fixed monthly expenses remaining unchanged and no cash coming in, he found himself losing sleep more often. While it is a useful tool for filling income gaps, you must accurately understand the pros and cons of the system to avoid financial loss later on.
Early receipt, which allows you to receive benefits up to five years before the statutory age, helps bridge income gaps but requires thorough calculation.
2. Calculating the Reduction Rate and the Deducted Amount
The biggest cost of early receipt is that, in exchange for receiving the pension earlier, you must accept a reduced amount for the rest of your life. For each year you receive the pension early, a reduction of 6 percent per year, or 0.5 percent per month, is applied. If you choose to receive it five years early, the pension will be paid for life with a total reduction of 30 percent. A person who would normally receive 1 million won per month would only receive 700,000 won if they choose to receive it five years early. This reduced amount is not temporary but remains in effect for life, leading to a significant long-term difference. In retiree communities, some people rejoice that their immediate financial pressure is relieved, but when calculating for 10 or 20 years down the line, the cumulative loss can reach tens of millions of won. Considering inflation, the monthly difference of 300,000 won will inevitably feel even larger over time. Unless you are in a special situation where your health is very poor or your livelihood is immediately threatened, you should not take the weight of this reduction rate lightly. You can even find people around you who applied blindly based on others’ advice and later regretted it when they visited the pension office.
For each year of early receipt, the amount is reduced by 6 percent, meaning receiving it five years early results in a permanent 30 percent reduction.
3. Having Income Can Lead to Pension Reduction or Suspension

Many people mistakenly believe that if they apply for early receipt and then do some part-time work or find re-employment to increase their income, they can still receive the full pension amount. However, if you earn income above a certain level while receiving the early old-age pension, your pension payments may be partially or fully suspended. If you exceed the income standards set by the National Pension Act, your pension may be reduced or stopped entirely. Every year, there are seniors who start part-time jobs at convenience stores or security work thinking it is just for pocket money, only to be shocked when their pension is cut off. Mr. Park started working at a small store to relieve boredom after retirement, only to receive an unexpected notification. Because his income during the early receipt period exceeded a certain threshold, his monthly pension was significantly reduced or suspended. He had expected his retirement to become more comfortable with both pension and labor income, but it is only natural that he felt frustrated when his pension was cut. Therefore, if you are considering early receipt, you must carefully check whether your expected additional labor income violates legal standards.
Be aware that if you earn income exceeding a certain standard during early receipt, your pension may be partially or fully suspended.
4. The Secret of the Age 77 Break-Even Point
The break-even point that determines whether early receipt is a gain or a loss is formed around the age of 77. When comparing receiving the pension at the normal age versus receiving it five years early, the advantage shifts around age 77. Before age 77, the total amount received is higher with early receipt, making it seem advantageous. However, after age 77, the normal recipient receives a higher monthly amount, causing the cumulative total to reverse. In other words, assuming you live a long and healthy life, it is much more advantageous to wait and receive the pension at the normal age rather than receiving a 30 percent reduced amount for life. Conversely, if your health is poor or you are likely to pass away earlier than the average life expectancy, choosing early receipt to use the funds sooner becomes a wise choice. For this reason, experts advise that you should make your decision by coldly analyzing your health status and family history. It is not enough to simply receive the money early and deposit it in your bank account; you must calculate based on your expected life expectancy.
Based on the break-even point around age 77, normal receipt is advantageous if you live longer, while early receipt is advantageous if your life is shortened.
5. Utilizing Local Government Support and Other Alternatives
If you retire at 60 and face an income gap until the National Pension eligibility age of 65, early receipt is not your only option. Recently, some local governments operate programs that provide small support funds to bridge the income gap between ages 60 and 65. In regions like Gyeongsangnam-do, for example, they provide a certain monthly amount to eligible retirees to prevent immediate financial distress. Utilizing these local government support programs, or other assets such as corporate pensions and personal pensions, is a way to avoid the loss from early pension reduction. Manager Lee, who needed money immediately after retirement, was about to apply for early receipt but looked for other options on the advice of those around him. He converted his existing corporate pension from a lump sum to a pension form and also looked into local government support programs for middle-aged and older adults. As a result, he secured a source of funds that allowed him to safely bridge the five-year income gap while keeping his National Pension intact. You need the wisdom to comprehensively check whether you have corporate pensions, housing pensions, or personal pensions before blindly reaching for the National Pension.
You can prevent reduction losses by utilizing various alternatives such as local government support funds and corporate pensions, in addition to early receipt.
6. The Final Choice for a Wise Retirement
Early receipt of the National Pension is a grateful system that provides relief to desperate retirees, but it comes with the fatal cost of receiving a reduced pension for life. Therefore, rather than applying just because others are traveling on early receipts, you should seriously consider your own life blueprint. You must find your optimal receipt time by comprehensively considering your future health status, expected life expectancy, and the presence of other income sources. To avoid the mistake of sacrificing future income to relieve immediate hunger, please calculate carefully based on the information learned today. Life after retirement is longer than you think, and expenses never stop, so it is wise to defend your pension assets as much as possible. At this very moment, countless retirees are likely losing sleep while agonizing over whether to choose early or normal receipt. If it is difficult to judge on your own, visiting a National Pension Service branch to simulate your expected pension amount and consult with an expert is a good method. Thorough preparation and cold calculation will be the most certain keys to guaranteeing a prosperous and stable retirement.
You should carefully decide whether to choose early receipt by comprehensively considering your health and financial situation to ensure a stable retirement.
Frequently Asked Questions
=