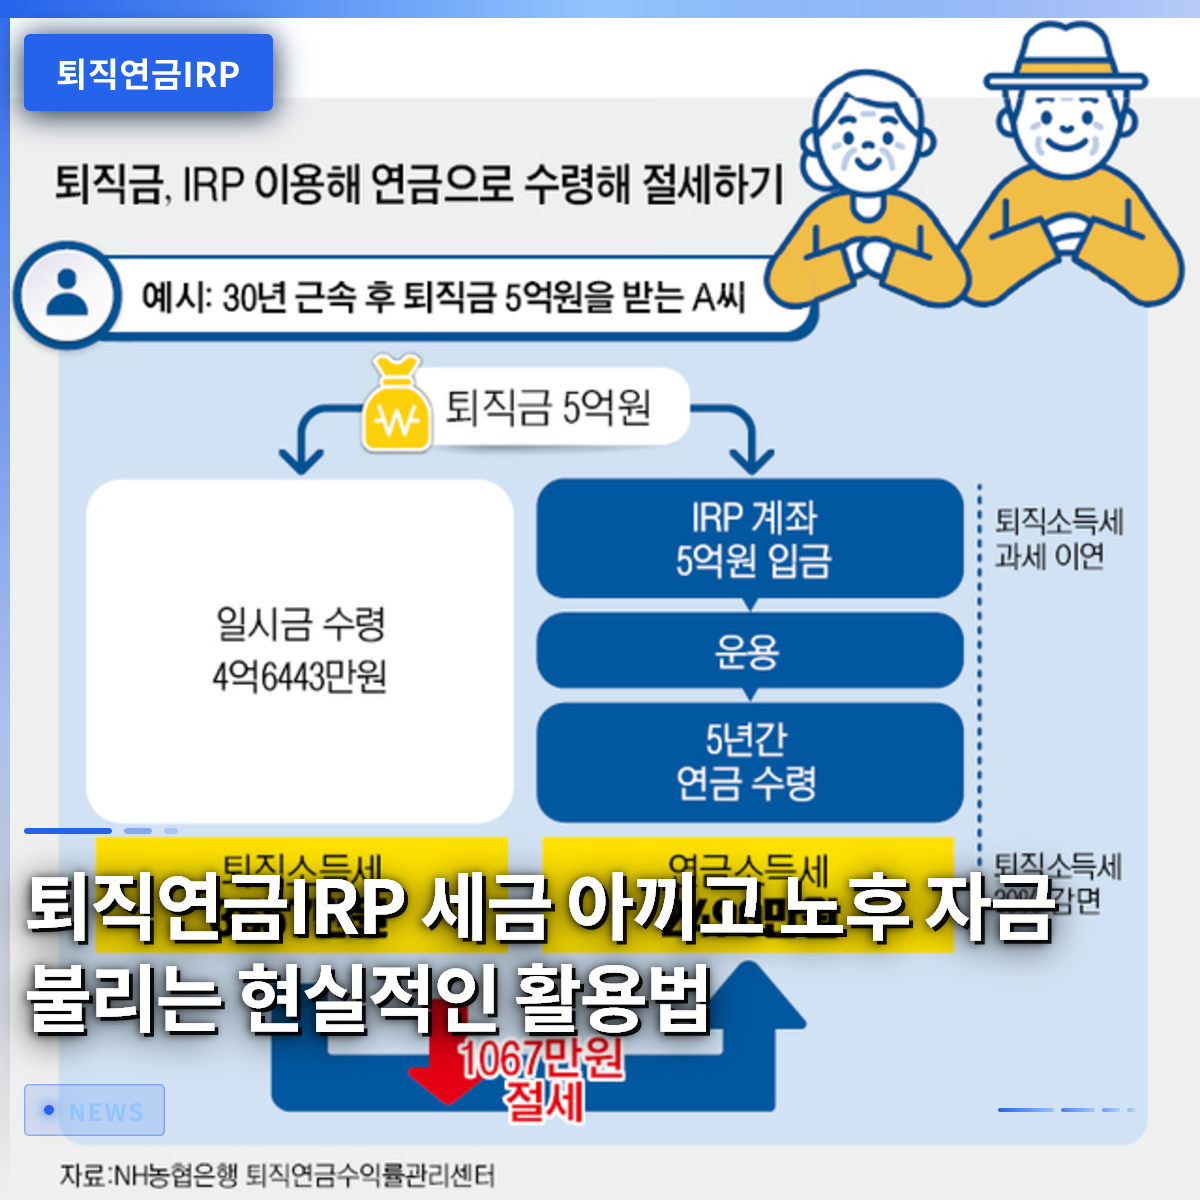
Properly utilizing your Individual Retirement Pension (IRP) account can significantly reduce unnecessary taxes and help you grow your retirement funds more advantageously. If you carelessly receive your severance pay into a regular checking account when leaving or changing jobs, you will end up paying a substantial amount of severance income tax. In reality, many office workers miss out on tax benefits because they do not immediately transfer their severance pay to an IRP account. In this article, we will outline the key methods for saving taxes and protecting your assets safely through an IRP account. Thoroughly reviewing the basic concepts of the system, specific tax-saving effects, and the latest investment products will be of great help. From here, we will explain these complex financial systems in a way that is easy for anyone to understand.
=
Practical Ways to Save Taxes and Grow Retirement Funds with Your IRP
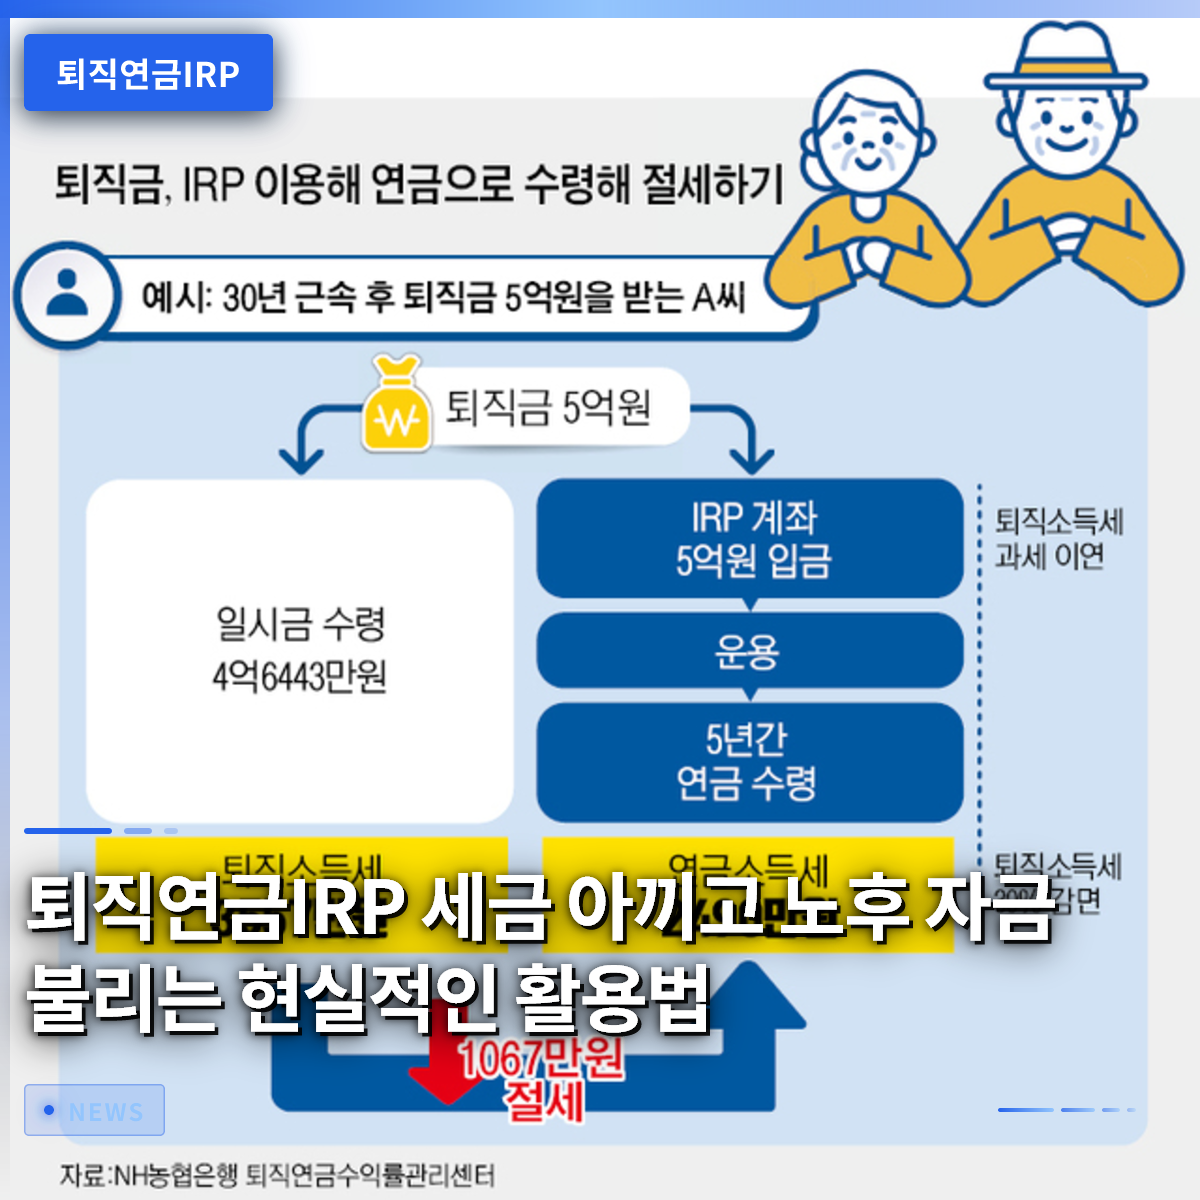
1. The Real Reason You Should Receive Severance Pay in an IRP Account

When receiving severance pay, routing it through an IRP account is overwhelmingly advantageous from a tax perspective. If you receive your severance pay into a regular account upon retirement or job change, severance income tax is withheld immediately, significantly reducing the amount of money you actually take home. However, if you transfer your severance pay to an IRP account, you can benefit from tax deferral, meaning taxes are not deducted immediately but postponed until you receive the pension. This allows the money that would have gone to taxes to remain in the account, where it can grow into a larger sum through the power of compound interest.
Opening and transferring funds to this account is an essential step for office workers concerned about securing retirement funds. It is not uncommon to see acquaintances sigh in disappointment after receiving their severance pay, only to have a large chunk deducted as tax after working diligently for over ten years. If you transfer your severance pay to an IRP account, you can receive a tax reduction of more than 30% on the severance income tax when you receive it as a pension after age 55. If you do not urgently need a lump sum, choosing the pension receipt method is a much wiser decision for tax savings.
You must transfer your severance pay to an IRP account to benefit from tax deferral and severance income tax reductions.
2. Maximizing the Hidden Gem of Year-End Tax Settlement: Tax Credit Benefits

By utilizing both pension savings and IRP accounts together, you can receive a substantial tax credit refund during your annual year-end tax settlement. While every office worker looks forward to their “13th month salary” during year-end tax preparation, using these accounts allows you to avoid a tax burden and maximize your refund. A combined annual contribution limit of up to 9 million won applies for tax credits, meaning the amount you get back can be quite significant depending on your income level. Employees with a total annual salary of 70 million won or less benefit from a higher deduction rate, often receiving refunds ranging from several hundred thousand to over one million won back into their accounts each year.
Young professionals and early-career workers can catch two birds with one stone—retirement preparation and tax savings—by starting this system early. You can directly feel the joy of seeing small monthly automatic deposits accumulate into a large refund every year-end tax season. Instead of just envying colleagues who receive large refunds every year, it is best to check your own contribution limit right now. Assets that are consistently grown from the time income is generated become a sturdy pillar and the best retirement strategy after retirement.
You can maximize your year-end tax settlement refund by combining pension savings and IRP contributions to receive tax credits of up to 9 million won.
3. Building a Portfolio That Balances Safety and Returns

IRP accounts, which handle retirement funds, require appropriate asset allocation rather than simply being kept in principal-guaranteed products. Interest from principal-and-interest guaranteed products may struggle to keep up with inflation, making the use of equity assets or Exchange-Traded Funds (ETFs) important. However, pouring all your money into volatile stocks is risky, so you should maintain a safe asset ratio of at least 30%. For example, it is safe to approach this from a long-term perspective by appropriately mixing bond-hybrid products with stable domestic and international index-tracking products.
Whether it is a Defined Contribution (DC) pension accumulated monthly at your workplace or an account managed personally, it is essential to manage it according to your investment style. You should be cautious of cases where people, hearing success stories about stock investments, recklessly invest their entire fortune in thematic products and end up with losses. Since retirement funds are not money you need to use tomorrow, the shortcut to victory is a strategy of staying steady, looking long-term, and diversifying into assets with an upward trend. Diligence is required to periodically check your account’s return rate and review your portfolio in line with market conditions.
You should build a long-term portfolio by combining index products with upward trends while adhering to safe asset regulations.
4. New Opportunity: Direct Investment in Individual Investor Bonds
Recently, it has become possible to directly purchase Individual Investor Bonds (IIBs), which are guaranteed by the state, in both DC pension and IRP accounts. This is wonderful news for subscribers who have been hesitant to invest in volatile products like stocks or funds. You can now subscribe directly to long-term government bonds, such as 10-year or 20-year bonds, starting from small amounts, which further enhances the stability of your portfolio. Since the structure adds a premium to the coupon rate, you can stably enjoy higher interest rates than bank deposits.
For office workers approaching retirement or subscribers who prioritize safe asset allocation, including government bonds is an excellent option. You do not need to invest a lump sum all at once; you can make split purchases starting from as little as 100,000 won, which eases the pressure on fund management. The biggest appeal is that you can entrust your long-term funds to the state without worrying every time market interest rates fluctuate. If you want to upgrade the quality of your retirement asset account, it is worth seriously considering including government bonds this time.
You can enhance stability in your IRP account by directly purchasing 10-year and 20-year Individual Investor Bonds.
5. Fatal Temptations Leading to Early Cancellation and How to Handle Them
A surprisingly large number of subscribers cancel their IRP accounts midway, which has become a serious problem. If you break into the assets you have accumulated when you urgently need a lump sum or face temporary financial difficulties, you must bear enormous losses. In fact, while trillions of won have been transferred to these accounts over the past few years, nearly half of that amount has been canceled midway. If you cancel early, you not only have to return the tax credit benefits you received but also face additional miscellaneous income tax, resulting in a severe financial blow.
It is not difficult to see people around you who regret canceling their pension accounts due to sudden expenses. Unless it is an unavoidable situation, it is wiser to look for alternatives such as policy loans or other institutional options before canceling the account. The most important thing is the perseverance to maintain the account without wavering for a long period, keeping in mind that retirement funds are not an emergency fund. Simply maintaining the account without breaking it midway is the most certain way to prevent old-age poverty and guarantee a prosperous retirement life.
Early cancellation results in the clawback of tax benefits and tax disadvantages, so long-term maintenance is absolutely advantageous.
6. Practical Strategies for a Successful Retirement
The IRP account is the key to determining your life after retirement, so you should check the status of your account immediately. If you have scattered severance pay left behind from previous job changes, you should start by consolidating them into a single account. You need to make an effort to gradually increase your automatic transfer amounts to meet the tax credit limit, even amidst fixed monthly expenses. You should select investment products suitable for your age and style, referring to expert advice, and consistently grow your assets through regular contributions.
To prepare for the coming era of an aging population, the power to protect your own retirement comes from thorough financial knowledge and correct execution. We recommend that you do not just sign up reluctantly because everyone else is doing it, but rather experience the joy of managing and growing your assets with your own hands. Starting today, try reducing unnecessary expenses, checking the amount you contribute to your pension account, and designing a secure future. The only secret to smiling at the point of retirement lies in how wisely you utilize your IRP account from this very moment.
You should prepare for a stable retirement by consolidating scattered severance pay and maintaining consistent contributions and asset management.
Frequently Asked Questions
=