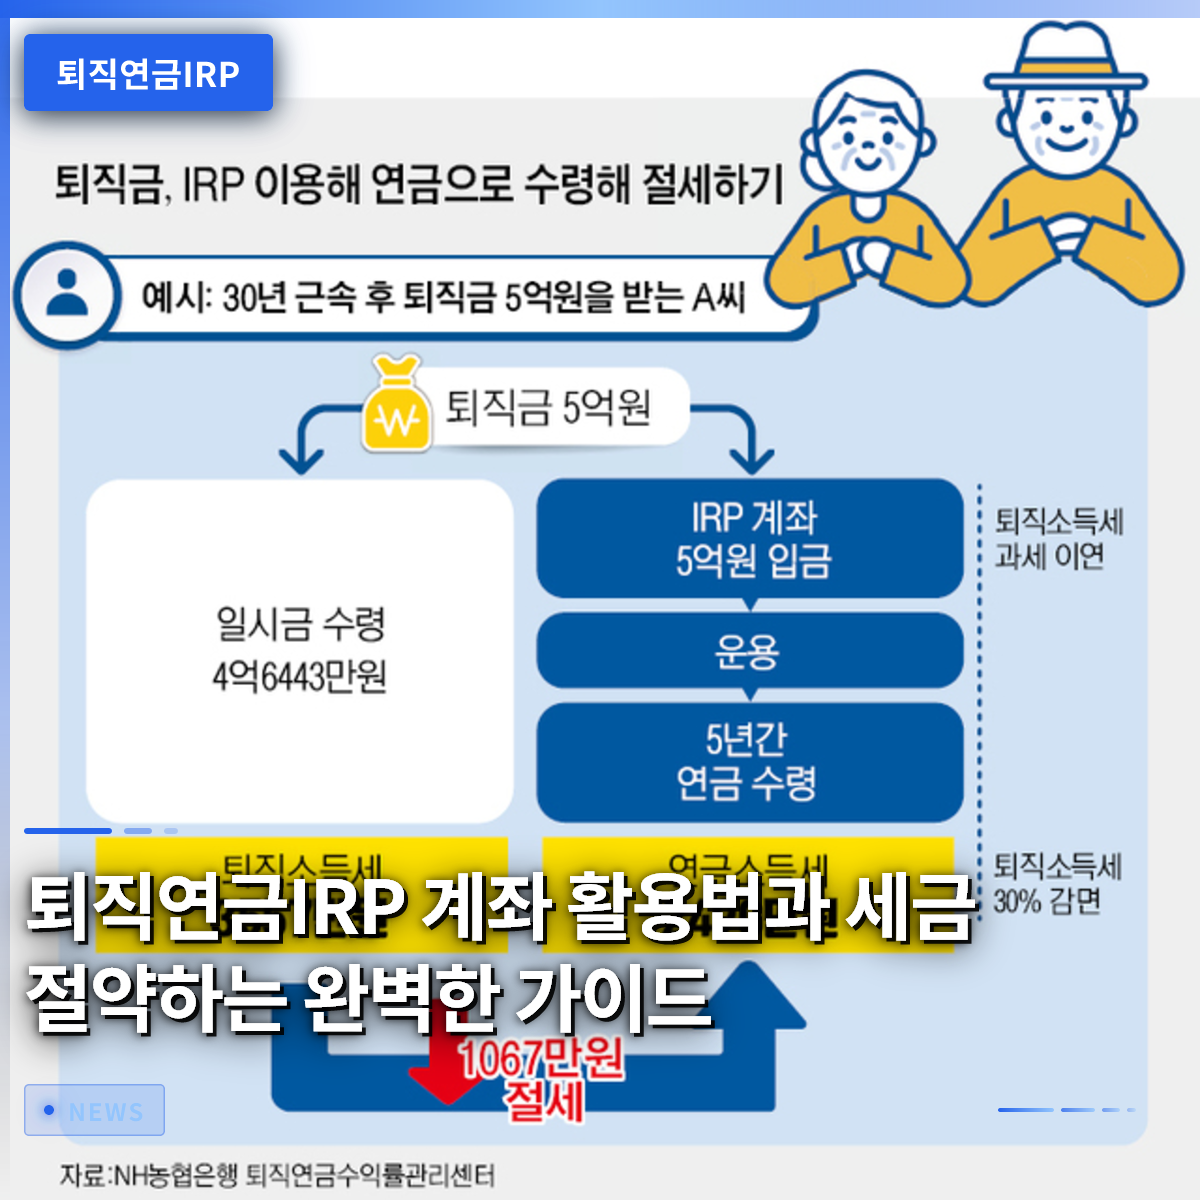
By utilizing an Individual Retirement Pension (IRP) account, you can significantly reduce your retirement income tax and safely grow your funds for old age. Many employees regret receiving their severance pay in a regular checking account without a second thought, only to end up paying millions of won in taxes. However, by law, severance pay must be transferred to an individual retirement pension account, and receiving it as a pension can greatly lower your tax burden. Recently, the range of investable products has expanded, allowing you to directly purchase stable government bonds. In this article, we will look in detail at specific tips for safely protecting your severance pay and maximizing tax benefits. If you are looking for wise asset management, please read on to the end.
=
How to Use Your IRP Retirement Account: The Ultimate Guide to Saving on Taxes
1. Why You Should Receive Your Severance Pay in an IRP Account Instead of a Regular Bank Account

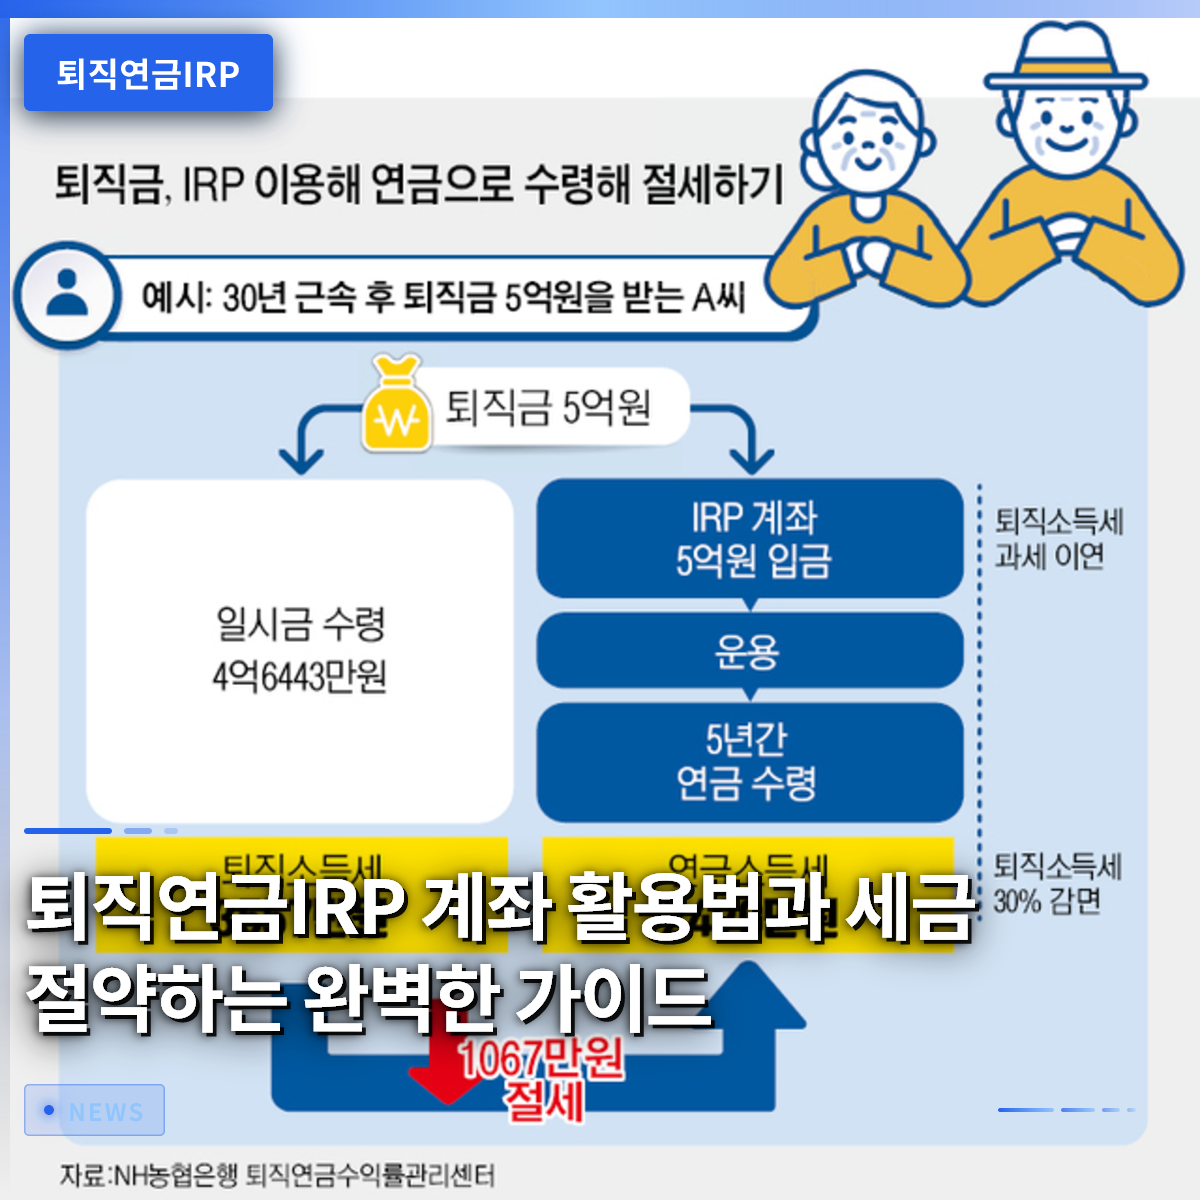
If you receive your severance pay directly into a regular bank account, retirement income tax is withheld at the source, significantly reducing the amount you actually take home. On the other hand, if you receive it through an Individual Retirement Pension (IRP) account, the tax is deferred rather than deducted immediately, giving you a powerful tool to grow even the money that would have gone to taxes through compound interest. In reality, it is common to see people who spent their entire severance pay on living expenses after changing jobs, only to struggle greatly at the point of retirement. This account is an institutional mechanism designed to allow you to gather and manage your valuable severance pay in one place when you change jobs or retire. Therefore, to save on taxes and systematically grow your assets, you must designate this account at the stage of receiving your severance pay.
To protect your valuable severance pay, it is essential to inform the relevant department of your Individual Retirement Pension account number in advance when leaving the company. Except for certain exceptional circumstances, companies are required by regulation to pay severance pay to the account designated by the employee. You should be cautious, as terminating the account early due to an urgent need for cash may require you to return the tax benefits you have received so far. Statistics show that while a massive amount of money has been transferred to these accounts in recent years, the rate of early termination is also quite high. Rather than rushing to terminate the account, it is most important to adopt an attitude of managing your funds with a long-term perspective until retirement.
Receiving severance pay in an IRP account defers taxes, allowing you to enjoy compound interest effects, and you should avoid early termination.
2. The Art of Receiving a Pension to Reduce Taxes and Prepare for Old Age

If you withdraw your severance pay as a lump sum, the joy of holding a large amount of cash is fleeting, but you may face a tax bomb. However, if you receive this fund as a monthly pension, you can receive a much larger reduction in retirement income tax compared to taking it as a lump sum. The government actively supports these tax benefits to help workers create a stable cash flow after retirement in preparation for an aging society. For retirees who need monthly living expenses, this is the most rational way to lower the tax burden while generating regular income.
The longer the period you receive the pension, the lower the applicable tax rate, so it is advantageous to plan your withdrawal strategy from a long-term perspective. A very wise strategy is to link your fund withdrawal with tips on reducing national health insurance premiums at the time of retirement. Looking at cases where retired seniors saved on taxes by adjusting their pension receipt periods can be very helpful. Since there are many ways to legally save on taxes with just a little attention, it is also a good idea to consult with a financial expert. To make your post-retirement life comfortable, you must carefully design your pension receipt method in advance.
Receiving your severance pay as a pension reduces your tax burden and allows you to enjoy a stable retirement life.
3. Safeguarding Your Principal with Individual Investment Government Bonds

If you are anxious about investing your severance pay in stocks or risky assets, you can utilize the individual investment government bonds newly introduced in September. You can now directly subscribe to and purchase 10-year and 20-year government bonds in both Individual Retirement Pension (IRP) accounts and Defined Contribution (DC) pension accounts. Since the minimum investment amount starts from 100,000 won, there is no burden of having to put in a large sum all at once. Because it is a safe product where the state guarantees the principal and interest, you can protect your assets with peace of mind even in volatile market conditions.
In reality, government bond investment becomes an excellent alternative for employees who are too worried to buy stocks with their severance pay, often losing sleep over it. The coupon rates are also set at attractive levels, making them more favorable than regular bank deposits, which continues to draw investors looking for better conditions. You can expect stable interest income over the long term by trusting the state, without having to check complex economic news every day. If your investment style is conservative, try constructing a portfolio where a significant portion of your pension assets is filled with safe government bonds. It serves as a sturdy fence that protects your principal while defending against inflation.
You can directly purchase 10-year and 20-year government bonds in your IRP account, allowing for safe investment without worrying about principal loss.
4. Insider Tips for Saving on Fees by Switching to Non-Face-to-Face Accounts
The management fees paid to financial institutions are like an invisible enemy that erodes your returns over long-term investments. You can save significantly on fees by switching to a non-face-to-face account via a smartphone app compared to accounts opened by visiting a branch. For example, if your accumulated funds are less than 50 million won, simply switching to a non-face-to-face account can drop the fees by more than half. While it may seem like a small difference, over a long period of 10 or 20 years, it creates a huge gap in your final asset size.
Employees who lack the time to visit bank or securities branches can easily lower their fees with just a few taps on their smartphones. If you ask acquaintances, you will find that surprisingly many people continue to pay unnecessary fees every year simply because they do not know about non-face-to-face conversion. You need the wisdom to carefully inquire about the fee structure with the staff in charge when transferring or bringing in your account. Remember that the lower the fees you pay, the higher your final returns in your account will be. Open your smartphone app right now to check your account’s fee conditions and apply for non-face-to-face preferential benefits.
Switching to a non-face-to-face account significantly lowers management fees, thereby increasing long-term investment returns.
5. Year-End Tax Settlement Strategy to Maximize Tax Deduction Limits
To maximize the amount you can get back during the year-end tax settlement as an employee, you must actively utilize your Individual Retirement Pension (IRP) account. By combining contributions to a general pension savings fund and this account, you can enjoy a substantial tax deduction benefit of up to 9 million won per year. If you set your monthly contribution amount in advance at the beginning of the year and consistently deposit money, you can secure a generous 13th-month bonus. For employees who have felt a heavy tax burden, this account is an essential financial product that offers a two-for-one benefit.
Instead of just envying colleagues who receive millions of won in refunds during the year-end tax settlement, you must take action yourself. If it is difficult to make a large contribution at once, it is best to set up automatic monthly transfers of a fixed amount to reduce the burden. Using the money returned from tax deductions for reinvestment noticeably accelerates the growth of your assets. However, since terminating the account early requires you to return all the benefits received so far, you should determine your contribution amount within the range of your surplus funds. If you want to catch both rabbits of retirement preparation and tax savings, check your contribution limits right now.
By combining pension savings and IRP contributions, you can receive tax deductions of up to 9 million won, maximizing your year-end tax settlement refund.
6. Outlook on Utilizing Retirement Pensions for a Successful Retirement
In the upcoming aging society, how wisely you manage your retirement pension account will completely determine your quality of life in old age. The government is also easing regulations to allow various investment products to be included in pension accounts to help citizens form assets for their old age. It is an era where funds that were previously just left sitting like bank deposits are now actively managed through government bonds and various funds. Only those who understand and implement the changing systems faster than others can welcome a prosperous retirement life.
Starting today, you need to make the small effort to carefully examine where your retirement pension account is invested. Please lower your fees, restructure your portfolio with safe government bonds or high-quality assets, and make sure to take full advantage of tax benefits. Retirement does not come suddenly; it becomes a comfortable sanctuary for those who prepare steadily over a long period. If you start preparing for your old age, which may have felt overwhelming, with this account, you will soon enjoy solid economic freedom. Why not open your smartphone app right now and check the status of your valuable retirement pension?
By actively utilizing the system and organizing your portfolio, you can complete a stable and prosperous retirement life.
Frequently Asked Questions
=